

Intro
When it comes to AI beneficiaries and hardware for AI applications, NVIDIA has gotten all the spotlight. NVIDIA’s share price has significantly contributed to both the S&P500 and the NASDAQ this year and the earnings releases have become a true media spectacle. But today we will not talk about NVIDIA, instead, we will focus on AMD. AMD has long been in the large shadow of Intel but has recently surpassed Intel in both market cap and fundamental performance. At the same time, AMD has taken large steps to become one of the dominant players in the (AI-) data center market and it is time that we take a look at AMD.
For those not familiar with the semiconductor industry a short intro in some terms that are common and which I will also use:
A CPU (central processing unit) is the “brain” of a computer and performs as the name says most of the processing tasks. A CPU usually works in conjunction with a GPU (graphics processing unit) and RAM. A GPU is designed to accelerate the rendering of videos and images. Due to this strength, it is very good at handling multiple processing steps at once it is used these days heavily in machine learning and AI cases.
Invest at your own risk; this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
If you want to go beyond reading and actually invest alongside me, you can invest in my Wikifolio. Every position reflects the same research-driven, long-term investing approach behind these deep dives — including investments such as Arista Networks, Alphabet, ASML, and AMD. You will find it here:
The Company
AMD (short for Advanced Micro Devices) is an American high-tech, semiconductor company based in Santa Clara, California, and employs more than 26,000 employees. AMD was founded in 1969 and already became a public company in 1972.
AMD describes itself like this:
“We are a global semiconductor company primarily offering: server microprocessors (CPUs), graphics processing units (GPUs), accelerated processing units (APUs), data processing units (DPUs), Field Programmable Gate Arrays (FPGAs), Smart Network Interface Cards (SmartNICs), Artificial Intelligence (AI) accelerators and Adaptive System-on-Chip (SoC) products for data centers.”
AMD describes its strategy as follows:
“Our strategy is to create and deliver the world’s leading high-performance and adaptive computing products across a diverse set of customer markets including data center, client, gaming and embedded.”
not surprisingly, AMD focuses on AI
“We believe that AI capabilities are central to products and solutions across our markets and we have a broad technology roadmap and products targeting AI training and inference spanning cloud, edge and intelligent endpoints.”
Writing a deep dive takes me 40+ hours to get a proper understanding of the company and the attributes of the industry it is working in. You will support me a great deal if you a) subscribe to this substack and b) recommend this blog to your friends and family. To all existing subscribers: Thank you for your support! :)
The Industry
The semiconductor industry got the awareness of the public latest with the shortage of chips in 2021. Beforehand many people were not aware, of the fact how many chips are used in all kinds of devices from fridges to cars. The integrated circuit was invented in 1948 and since then the industry only knew one way: Straight and up to the right.
Intel has been struggling in the last years and AMD has been one of the largest profiteers. For the first time since 2006, AMD might go above 40% market share in the CPU market. Notice how Apple started with its M1 chip in 2020.

GPUs have seen tremendous growth in the last years, mostly due to the rise of their usage in AI-related cases. Even more important than the past growth is the expected growth in the years to come. While I am not interested in where exactly the market will be in 2033, I believe this chart gives a good indication of what is bound to happen and why companies such as NVIDIA and AMD are so interesting.

NVIDIA’s stock price serves as a good illustration of the growth of the GPU market in the last few years.

The increase in the share price was driven by the increase in sales and income. It is unheard of, that a company the size of NVIDIA just doubles their net income starting from a basis of $30 billion.

AMD has seriously tackled the server-based GPU market with the release of the MI300 chip (more on that later). The following part of the Q3/2024 earnings call serves as a good intro to the rest of the article. Analyst Harsh Kumar was referring to Nvidia.
“In the coming year, let's say, 2025, your key competitor will take most of the TAM of the AI market, the GPU market, rough count, they'll take in something like $50 billion, $60 billion, you'll get another $5 billion to $10 billion, call it. So the question is, what do you think is the major hindrance? You've got chip level compatibility. So does it boil down to the fact that you're just earlier in the game. You've been doing this just 12 months in a serious manner? Or is there still a rack level of disparity? If you could just help us think about what the hindrances are to you becoming a major player here.”
AMD CEO Lisa Su answered:
“Maybe let me say, I view them as opportunities. If you remember, Harsh, and I think you do, our EPYC ramp from Zen 1, Zen 2, Zen 3, Zen 4 we had extremely good product even back in the Rome days, but it does take time to ensure that there is trust built, there is familiarity with the product set. There are some differences, although we're both GPUs, there are some differences, obviously, in the software environment. And people want to get comfortable with the workload ramp.”
“So from a ramp standpoint, I'm actually very positive on the ramp rate. It's the fastest product ramp that I've seen overall. And my view is this is a multi-generational journey. We've always said that. We feel very good about the progress I think next year is going to be about expanding both customer set as well as workload. And as we get into the MI400 series, we think it's an exceptional product. So -- all in all, the ramp is going well, and we will continue to earn and -- earn the trust and the partnership of these large customers.”
“What I will say is customers are very, very open to AMD. And we see that everywhere we go, everyone is giving us a very fair shot at earning their business, and that's what we intend to do.”
The Business
AMD has 4 reporting segments:
Data Center: these are server CPUs, GPUs, APUs, DPUs, FPGAs, SmartNICs, AI accelerators and Adaptive SoC products
Client segment: CPUs, APUs, and chipsets for desktop, notebook, and handheld personal computers
Gaming segment: discrete GPUs, semi-custom SoC products, and development services
Embedded segment: embedded CPUs, GPUs, APUs, FPGAs, SOMs, and Adaptive SoC products

To go a bit deeper into the different segments:
Data Center
The data center segment has been growing strong and companies like Microsoft, Alphabet, and Amazon have spent billions in the last years to build up their data centers. Data centers have special needs for CPU and GPUs and you cannot just simply reuse a CPU from a laptop and use it in a data center.

The fifth generation of AMD EPYC CPUs is already being built using 4nm and 3nm technology. Sidenote: All these processors are built by Taiwan Semiconductor and Taiwan Semi in turn buys the machines for building these chips from ASML. Check out ASML if you haven’t done so already. You will find some more information on ASML in my Best Buys article:
Best Buys December 2024

In this short format, I want to present to you companies and stocks, which are currently valued at an attractive level. Writing a deep dive takes me many hours and with this format, I can introduce you to interesting ideas as of today.
AI models and their requirements to compute many different instances in parallel make GPUs way better equipped to handle the workload than CPUs. NVIDIA is the best-known provider of GPUs and AMD focuses on GPU accelerators with its Instict MI200 and MI300 series. The MI300 was the fastest product in AMD history to surpass $1 billion in revenue and it took just two quarters after launch to achieve this milestone. In the third quarter after launch, the quarterly revenue already exceeded $1 billion in revenue and for the whole year, AMD expects $5 billion in revenue for the MI300. One big reason was Microsoft, which uses MI300 GPUs for Azure and also ChatGPT. Meta announced, that the most advanced version of its Llama AI runs exclusively on MI300X GPUs. to serve all live traffic. As of 2024, most of the MI300 GPUs are currently used for AI inference but due to rapid training adoption, AMD expects that within a year the mix of inference and training is 50/50.
In case you wonder what exactly inference and training is: Inference is where capabilities learned during deep learning training are applied. Training must happen first and without training, inference can't happen.
The downside of this fast rampup is, that the MI300 margins are now lower than the rest of the portfolio. Over time when the product is more established, AMD’s management believes that it can improve AMD’s margin.

The data center segment is getting ever more important for AMD and combined with the embedded segment contributed more than 50% of total revenue in 2023. AMD has been gaining market share at a rapid pace. Just a couple of years ago, AMD had a low single-digit market share for server CPUs and managed to increase its market share for server CPUs to 34% this year.
“Importantly, Data Center and Embedded segment annual revenue grew by $1.2 billion and accounted for more than 50% of revenue in 2023 as we gained server share, launched our next-generation Instinct AI accelerators and maintained our position as the industry's largest provider of adaptive computing solutions.”
All the large cloud players are customers of AMD as this quote from CEO Lisa Su on the Q4/2023 earnings call illustrates
“Amazon, Alibaba, Google, Microsoft and Oracle brought more than 55 AMD-powered AI, HPC and general-purpose cloud instances into preview or general availability in the fourth quarter. Exiting 2023, there were more than 800 EPYC CPU-based public cloud instances available.”
Next to the obvious cloud providers as mentioned above, companies such as Uber and Netflix also run their cloud instances based on AMD CPUs to handle their customer-facing workloads. Social media behemoth Meta has deployed more than 1.5 million (!) EPYC CPUs in their global data centers to run its social media platforms. CFO Jean Hu elaborated on this topic at the Barclays Annual Global Technology Conference in December 2024:
“when you look at the cloud native workload from Shopee, Amazon, social media, Facebook, WhatsApp to video streaming Netflix or Zoom. All those things are powered by general compute. That's the CPU. So we do see like, okay, AI is going to growing much faster, but the demand for fundamental applications when everybody increasing engagement in their platform is going to be continue to grow.”
“We can provide more performance. So we have been supporting the continued demand increase but overall, it is a very large market. We continue to see strong demand in cloud. We see modernization, we see the limitation on space and the power. So customers actually needed to upgrade. They also see their platform engagement is increasing.”
“They need more CPUs in enterprise, we also start to see the early signs of refreshing cycle. It's the same logic. It's -- you need more compute to support your applications, but you have a data center and the power limitation. So you want to get the best TCO from your suppliers. That's why we do think this CPU market and not only it's going to grow, but also we're going to continue to be able to gain share because of the performance.”
When you read the news about the insane amount of energy needed to power the most recent data centers you know, how important energy efficiency is in the market. AMD states the efficiency of their chips as one of the reasons why customers choose AMD.
“Given our high core count and energy efficiency, we can deliver the same amount of compute with 45% fewer servers compared to the competition, cutting initial CapEx by up to half and lowering annual OpEx by more than 40%. As a result, enterprise adoption of EPYC CPUs is accelerating, highlighted by deployments with large enterprises, including American Airlines, DBS, Emirates Bank, Shell and STMicro.”
The world’s fastest supercomputer “El Capitan” is powered by AMD Instinct MI300A accelerators. Taken from Wikipedia.
“El Capitan uses a combined 11,039,616 CPU and GPU cores consisting of 43,808 AMD 4th Gen EPYC 24C "Genoa" 24 core 1.8 GHz CPUs (1,051,392 cores) and 43,808 AMD Instinct MI300A GPUs (9,988,224 cores).”
This supercomputer can do 2,000 Petaflops or in other words 2,000,000,000,000,000,000 calculations per second.

An interesting side story: AMD names its processors after cities and currently they are named after Italian cities. The most recent CPUs bear the names Genoa, Bergamo, Siena, and Turin.
Client segment
These are the CPUs and GPUs you as an end-consumer will most likely interact with. Your standard laptop has either an Intel or an AMD CPU and quite often a GPU or in some cases an APU (CPU and GPU combined on a single chip). In most cases, the APU is enough since most desktop workers don’t have that much computing power for MS Teams and Outlook, Excel, PowerPoint, etc. AMD has been growing its market share in the desktop market at the expense of Intel since 2016 and is getting close to overtaking Intel.

In comparison to desktop CPUs, notebook CPUs pose a higher demand on energy efficiency so that your laptop doesn’t run out of energy after 2 hours of usage.
Gaming segment
Within the gaming segment, AMD also clusters its professional GPUs, which are mostly used for 3D rendering, design, and manufacturing CAD as well as media and entertainment broadcasting.
That’s how I got to know the names of Intel, AMD, and NVIDIA many years ago. Looking back, I could bite my rear part of not investing in NVIDIA. Back then there was always the discussion whether Intel or AMD was leading in CPUs. These days GPUs have become the most important unit to render images in a faster and better quality than ever before. In the important console market, AMD provides the RDNA graphic architecture for both the PlayStation 5 and the Xbox series S and X. AMD also works closely with Valve to create the semi-custom APU for the Steam Deck handheld device.

According to this ranking from Tom’s Hardware, AMD is eating Intel’s lunch when it comes to the performance of gaming CPUs. The AMD Ryzen CPUs dominate the list, while Intel’s first CPU only shows up at the sixth spot.

While researching for this article I came across this interesting graph: The mobile market has seen insane growth due to all the micro transactions and casual games. With the rise of computing power on mobile phones, handheld devices such as the Gameboy or PlayStation Portable disappeared. The PC has shown a strong comeback partly due to the rise of game platforms such as Steam.

Embedded segment
The embedded segment focuses on processors and systems on chips which are computing devices that perform specific tasks as part of a larger system. This includes automotive, industrial, networking, aerospace, defense, and many more sectors. Depending on the use case, these systems are specialized to be either very small, have low power consumption, or 24x7 runtime.
If you want to read the full article and learn about the management, the composition of the segments, takeovers, risks, fundamental analysis, and a conclusion please subscribe and support my work. To all existing subscribers: Thank you for your support and enjoy the rest of the article!
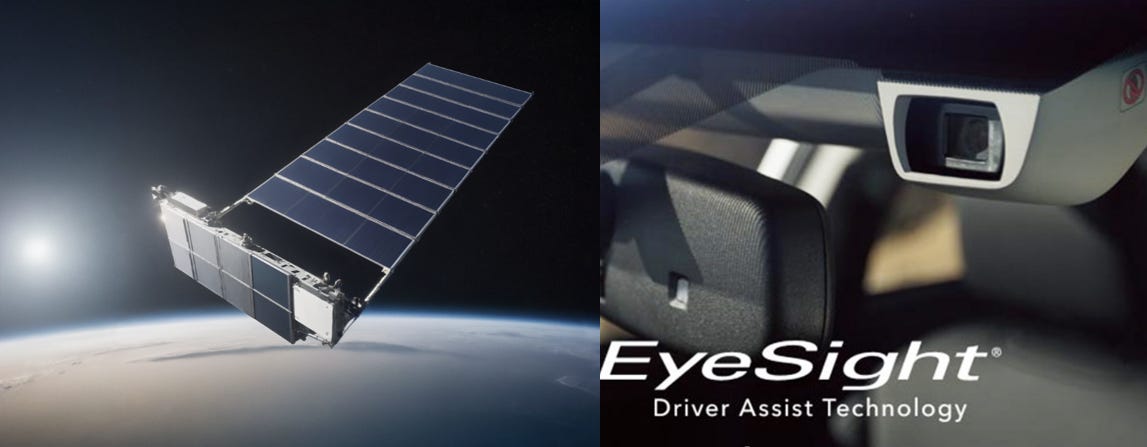
One such use case is the EyeSight ADAS system from Japanese car manufacturer Subaru. These cameras monitor the traffic situation and detect potential obstacles for the car. With AMD chips, computing can be done onboard in a space-saving way. On the other end of the spectrum is SpaceX, which uses Versal AI Core adaptive SoCs for its newest generation of broadband satellites.
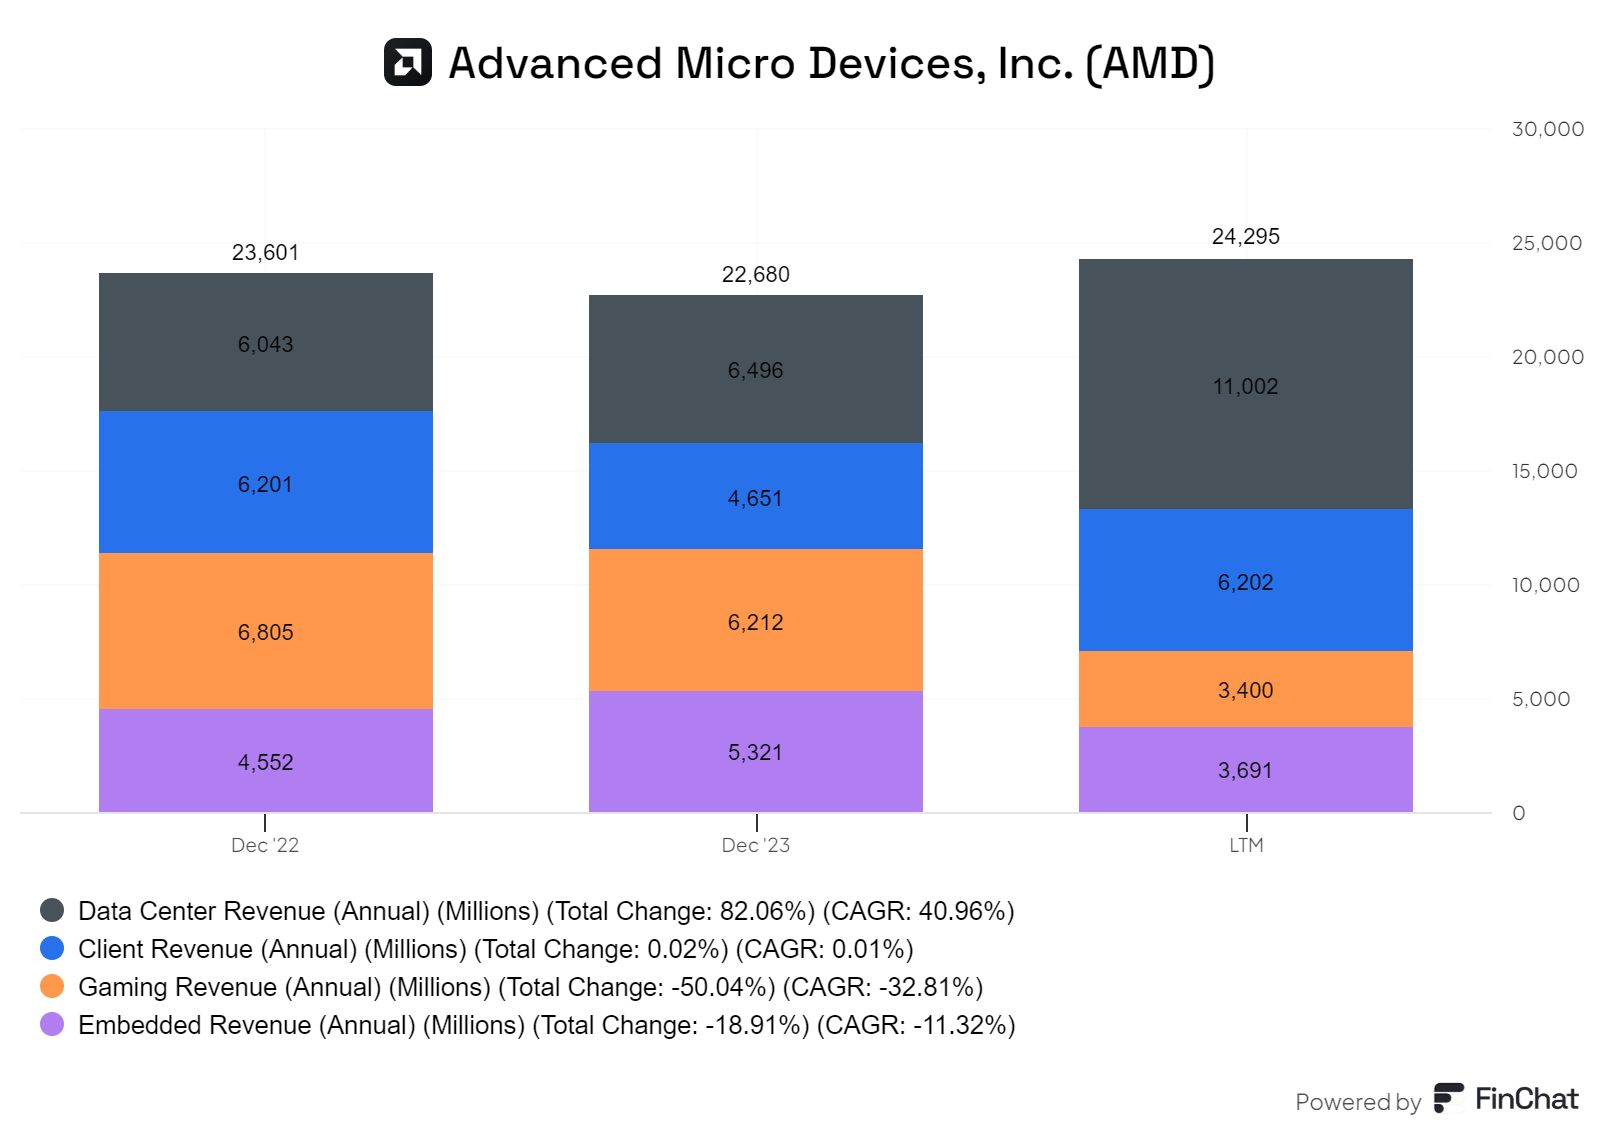
The development of the segments has been very different. Gaming and embedded have been quite weak in the last two years while the data center revenue has been the star of the show. The gaming segment has been weak in comparison to the previous years due to lower demand for PlayStation and Xbox consoles since both consoles are already in year 5 since their launch. You can expect a strong increase in sales once the new generation is released. The embedded segment is down due to high inventories at vendors and distributors. The decline in both the gaming and embedded segment was forecasted by AMD’s management in late 2023 and it is nice to see that the management can anticipate such developments.
CEO Lisa Su shares the view of many other experts, that AI is the next big big thing after the internet.
“We see AI as the biggest inflection point in PC since the Internet, with the ability to deliver unprecedented productivity and usability gains. We're working very closely with Microsoft and a broad ecosystem of partners to enable the next generation of AI experiences.”
“Looking further ahead, AI represents an unprecedented opportunity for AMD. While there has been significant growth in AI infrastructure build-outs, we are still in the very early stages of what we believe is going to be a period of sustained growth, driven by an insatiable demand for both high-performance AI and general purpose compute.”
“We have expanded our investments across the company to capture this large growth opportunity, from rapidly expanding our AI software stack to accelerating our AI hardware road maps, increasing our go-to-market activities and partnering closely with the largest AI companies to co-optimize solutions for their most important workloads. We are very excited about the trajectory of the business and the significant growth opportunities ahead.”
A very welcome benefit of the increased data center revenue is the higher margins that these chips provide compared to the gaming or client segment.
“the major driver is going to be Data Center business is going to grow much faster than other segments. That mix change will help us to expand the gross margin nicely. I think you also are spot on, on the Embedded coming back in second half, which will be a tailwind. With the Data Center GPU, we are at the very early stage of ramp.”
Next to selling hardware in the form of CPUs, GPUs, and embedded devices, AMD makes sure that its users also get the necessary software support to start using the devices seamlessly:
“On the AI software front, we made significant progress enhancing support and features across our software stack, making it easier to deploy high-performance AI solutions on our platforms. We also continued to work with the open source community to enable customers to implement the latest AI algorithms. As an example, AMD support for FlashAttention-2 algorithm was upstreamed, providing out-of-the-box support for AMD hardware in the popular library that can increase training and inference performance on large transformer models.”
AMD sells directly and via independent distributors to the end customers. These end customers can be anywhere between defense manufacturers and data center OEMs. The largest customer contributed 18% of the total revenue in 2023 and said customer was Sony which is getting its system-on-chips from AMD for the PlayStation 5. The remaining top customers of AMD are: Microsoft (Xbox and AI chips), HP (computer and laptop chips), Meta (AI chips), and Oracle (AI chips).
The largest competitor of AMD is Intel, both in data center CPUs and consumer CPUs. In terms of GPUs, NVIDIA is the behemoth to be conquered. The production is mostly outsourced and is done by Taiwan Semiconductor as well as Samsung and Global Foundries.
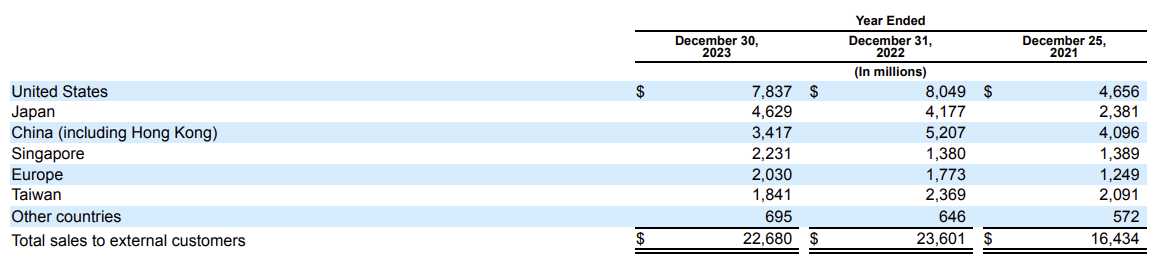
Most of the revenue is generated in the US, followed by Japan (Sony) and China.
The Management
Chair and CEO Lisa Su was born in Taiwan and moved to the US as a child. She joined in 2012 and was appointed CEO in 2014. Apart from a great track record as CEO of AMD, Lisa Su has a stellar academic track record and contributed to the development of the silicon-on-insulator semiconductor manufacturing technology. Before joining AMD she worked for 13 years in leading positions at IBM.
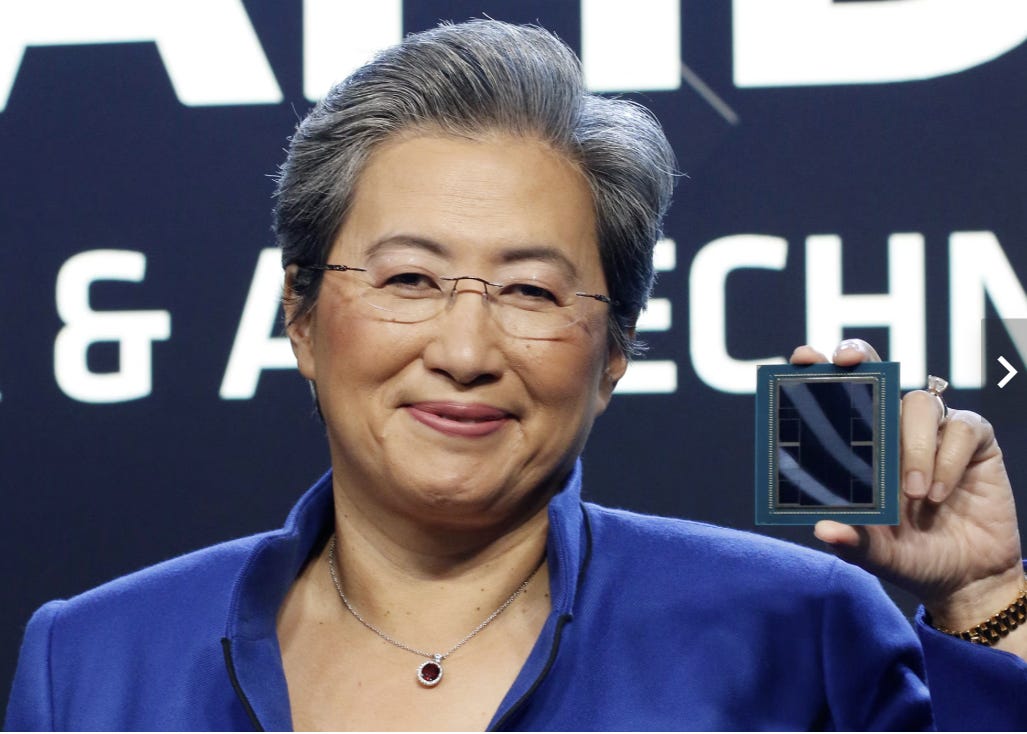
You can say that she achieved a thing or two based on her recent awards and accolades.
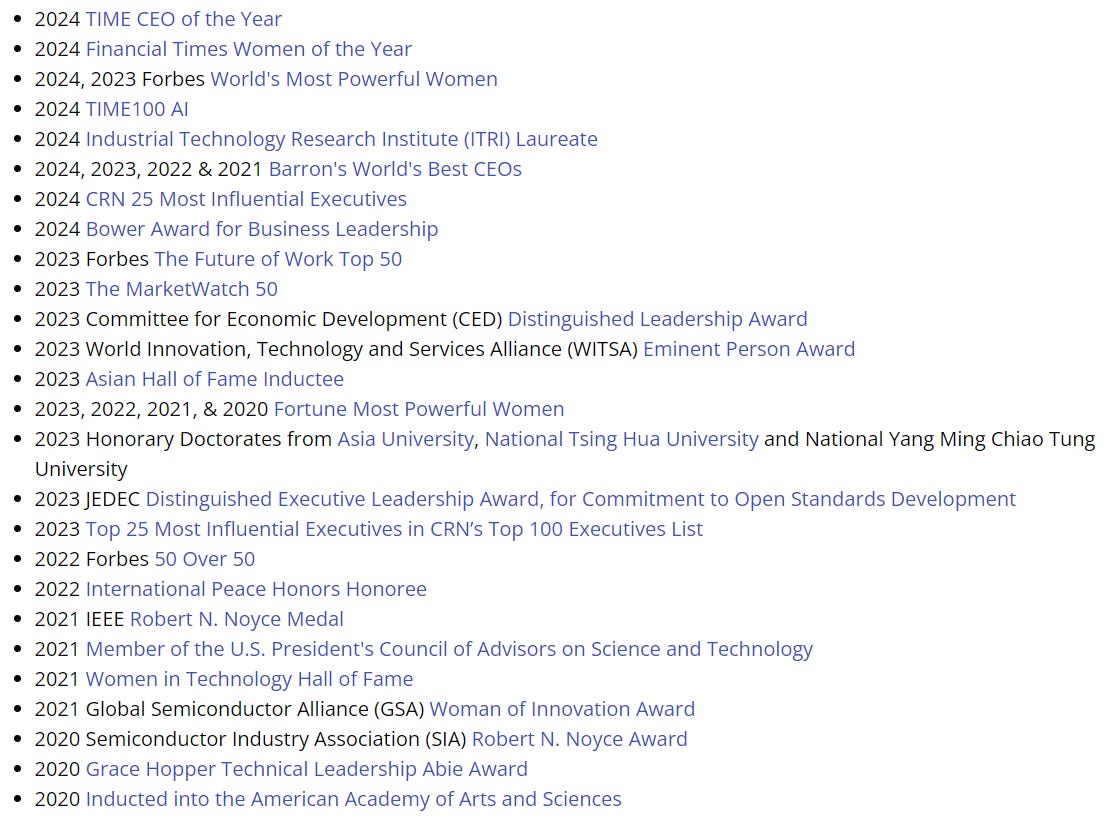
One of her main contributions was diversifying AMD away from pure computer chips. I like the fact that she has been in the industry for so long and has a fundamental understanding of the technology on which AMD is based, compared to some other CEOs who are far away from the actual product. During her tenure as CEO, the market cap of AMD increased from $3 billion to more than $200 billion today. She owns 0.25% of AMD and her shares are worth more than $600 million.
That’s how she describes her mission:
“AMD is at our best when we are taking bold, calculated risks and aggressively pursuing the leading-edge technologies that change the world.”
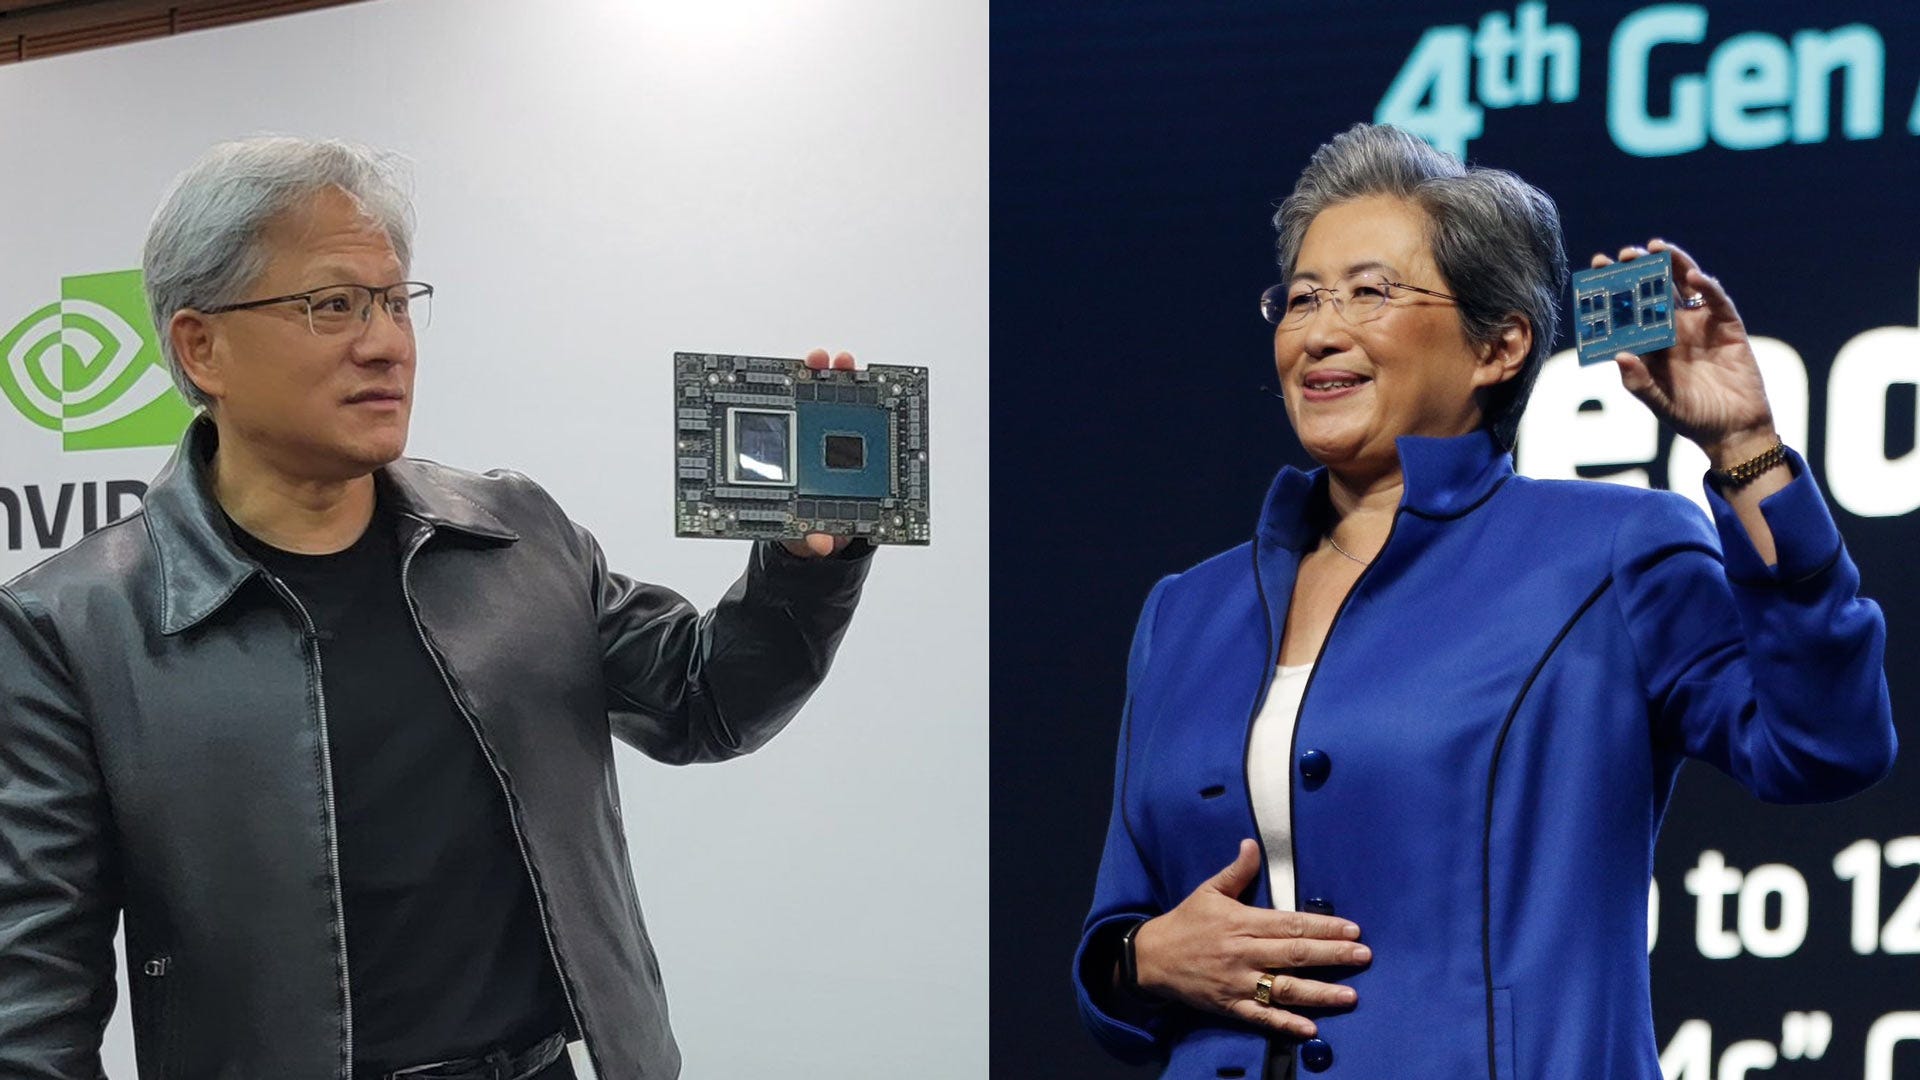
A crazy fact: Lisa Su is a first cousin of Jensen Huang, CEO and founder of NVIDIA. Talk about a successful immigration story.
Takeovers
AMD doesn’t shy away from large takeovers as the takeover of Xilinx in 2022 has shown. Recently the takeovers have been more focused on AI-related topics.
In July 2024, AMD announced that it is acquiring Silo AI for $665 million in cash. Silo AI is Europe's largest private AI lab that has experience in developing customized AI solutions for enterprise and embedded customers. Apart from buying Silo AI, Mipsology, and Nod.ai, AMD has invested more than $125 million across a dozen AI companies in the last 18 months to expand its own AMD AI ecosystem.
The largest takeover of AMD was Xilinx in February 2022 for $48.8 billion, which was mostly financed by stock issuance. Xilinx is a leading provider of adaptive computing solutions and also invented the first commercially usable FPGA (field programmable gate array). With the acquisition of Xilinx, the Company now offers FPGAs, Adaptive SoC products, and ACAP products. AMD gave the reason for the acquisition as follows:
“Over the next decade, high-performance computing will increasingly be at the center of nearly every major trend shaping the future. While CPUs and GPUs will remain critical engines for those devices, in a world where algorithms are always advancing and new standards are continually emerging, we see demand growing for adaptive computing capabilities that will be critical to accelerate these emerging and evolving workloads.”
Apart from offering a brand new field of technology, the Xilinx takeover added 15,000 engineers to AMD’s workforce.
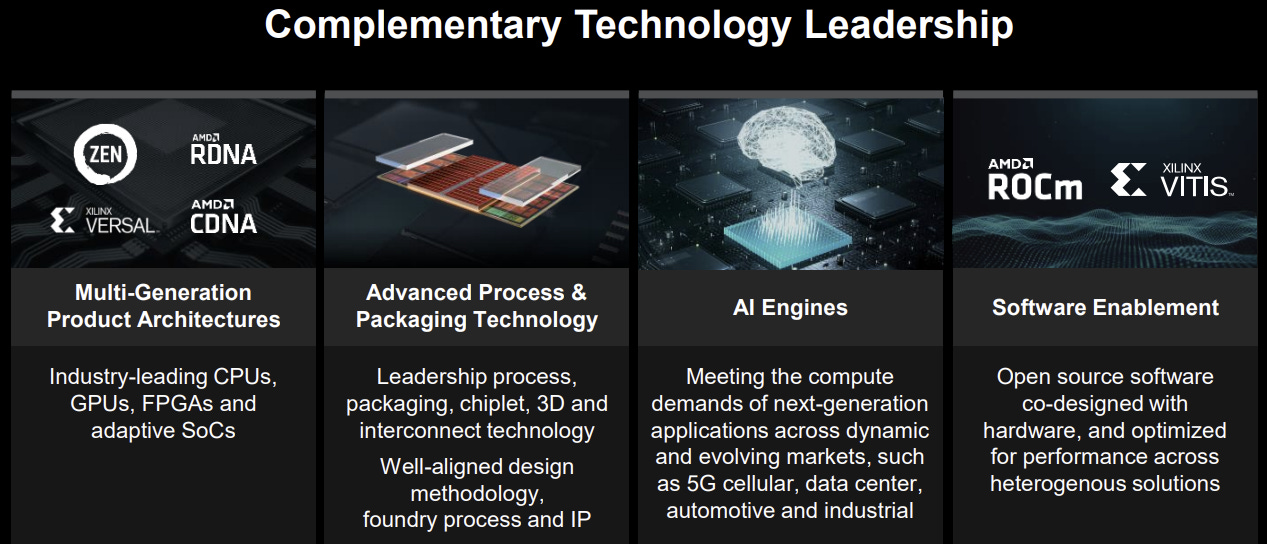
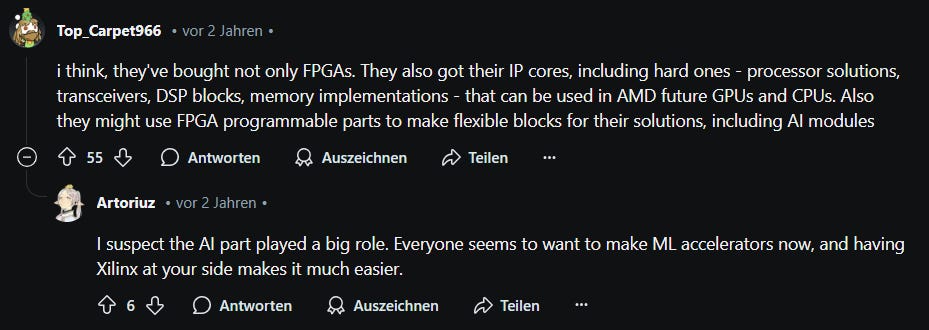
It all comes down to being better positioned in the data center and AI market. In one Reddit thread, the users were discussing why AMD paid so much for Xilinx. These two comments summarized it very nicely:
In 2022 AMD acquired Pensando for $1.9 billion to expand AMD’s data processing unit portfolio. Lisa Su commented on the acquisition below:
“Pensando’s leadership DPU complements our data center product portfolio, enabling AMD to offer solutions that can significantly accelerate data transfer speeds while providing additional levels of security and analytics that will play a larger role in defining the performance of next-generation data centers.”
To further strengthen AMD's foothold in the server market, AMD is in the process of buying ZT Systems in a deal worth $4.9 billion and the deal is expected to close in the first half of 2025. ZT Systems is one of the leading providers of AI infrastructure for hyperscale computing companies. This deal will help AMD to sell more than just CPUs and GPUs for data centers but instead offer the whole data center AI infrastructure to its customers. These data centers are then obviously powered by AMD CPUs and GPUs; therefore increasing the revenue in these two product lines. Lisa Su gave the reason for the acquisition:
“ZT adds world-class systems design and rack-scale solutions expertise that will significantly strengthen our data center AI systems and customer enablement capabilities. This acquisition also builds on the investments we have made to accelerate our AI hardware and software roadmaps. Combining our high-performance Instinct AI accelerator, EPYC CPU, and networking product portfolios with ZT Systems’ industry-leading data center systems expertise will enable AMD to deliver end-to-end data center AI infrastructure at scale with our ecosystem of OEM and ODM partners.”
As you can see, AMD is clearly focused on strengthening its position in the data center and therefore AI market. All these acquisitions help to achieve this goal. That being said, these acquisitions were very expensive and the success of the acquisitions can only be seen in a couple of years if AMDs strategy is successful.
Risks
Cyclicality! The semiconductor industry is highly cyclicality and booms follow busts and vice versa a lot faster than in many other industries. You can see this in the fluctuating revenue of AMD. Downturns like the one from 2015-2016 are followed by rapid expansions.
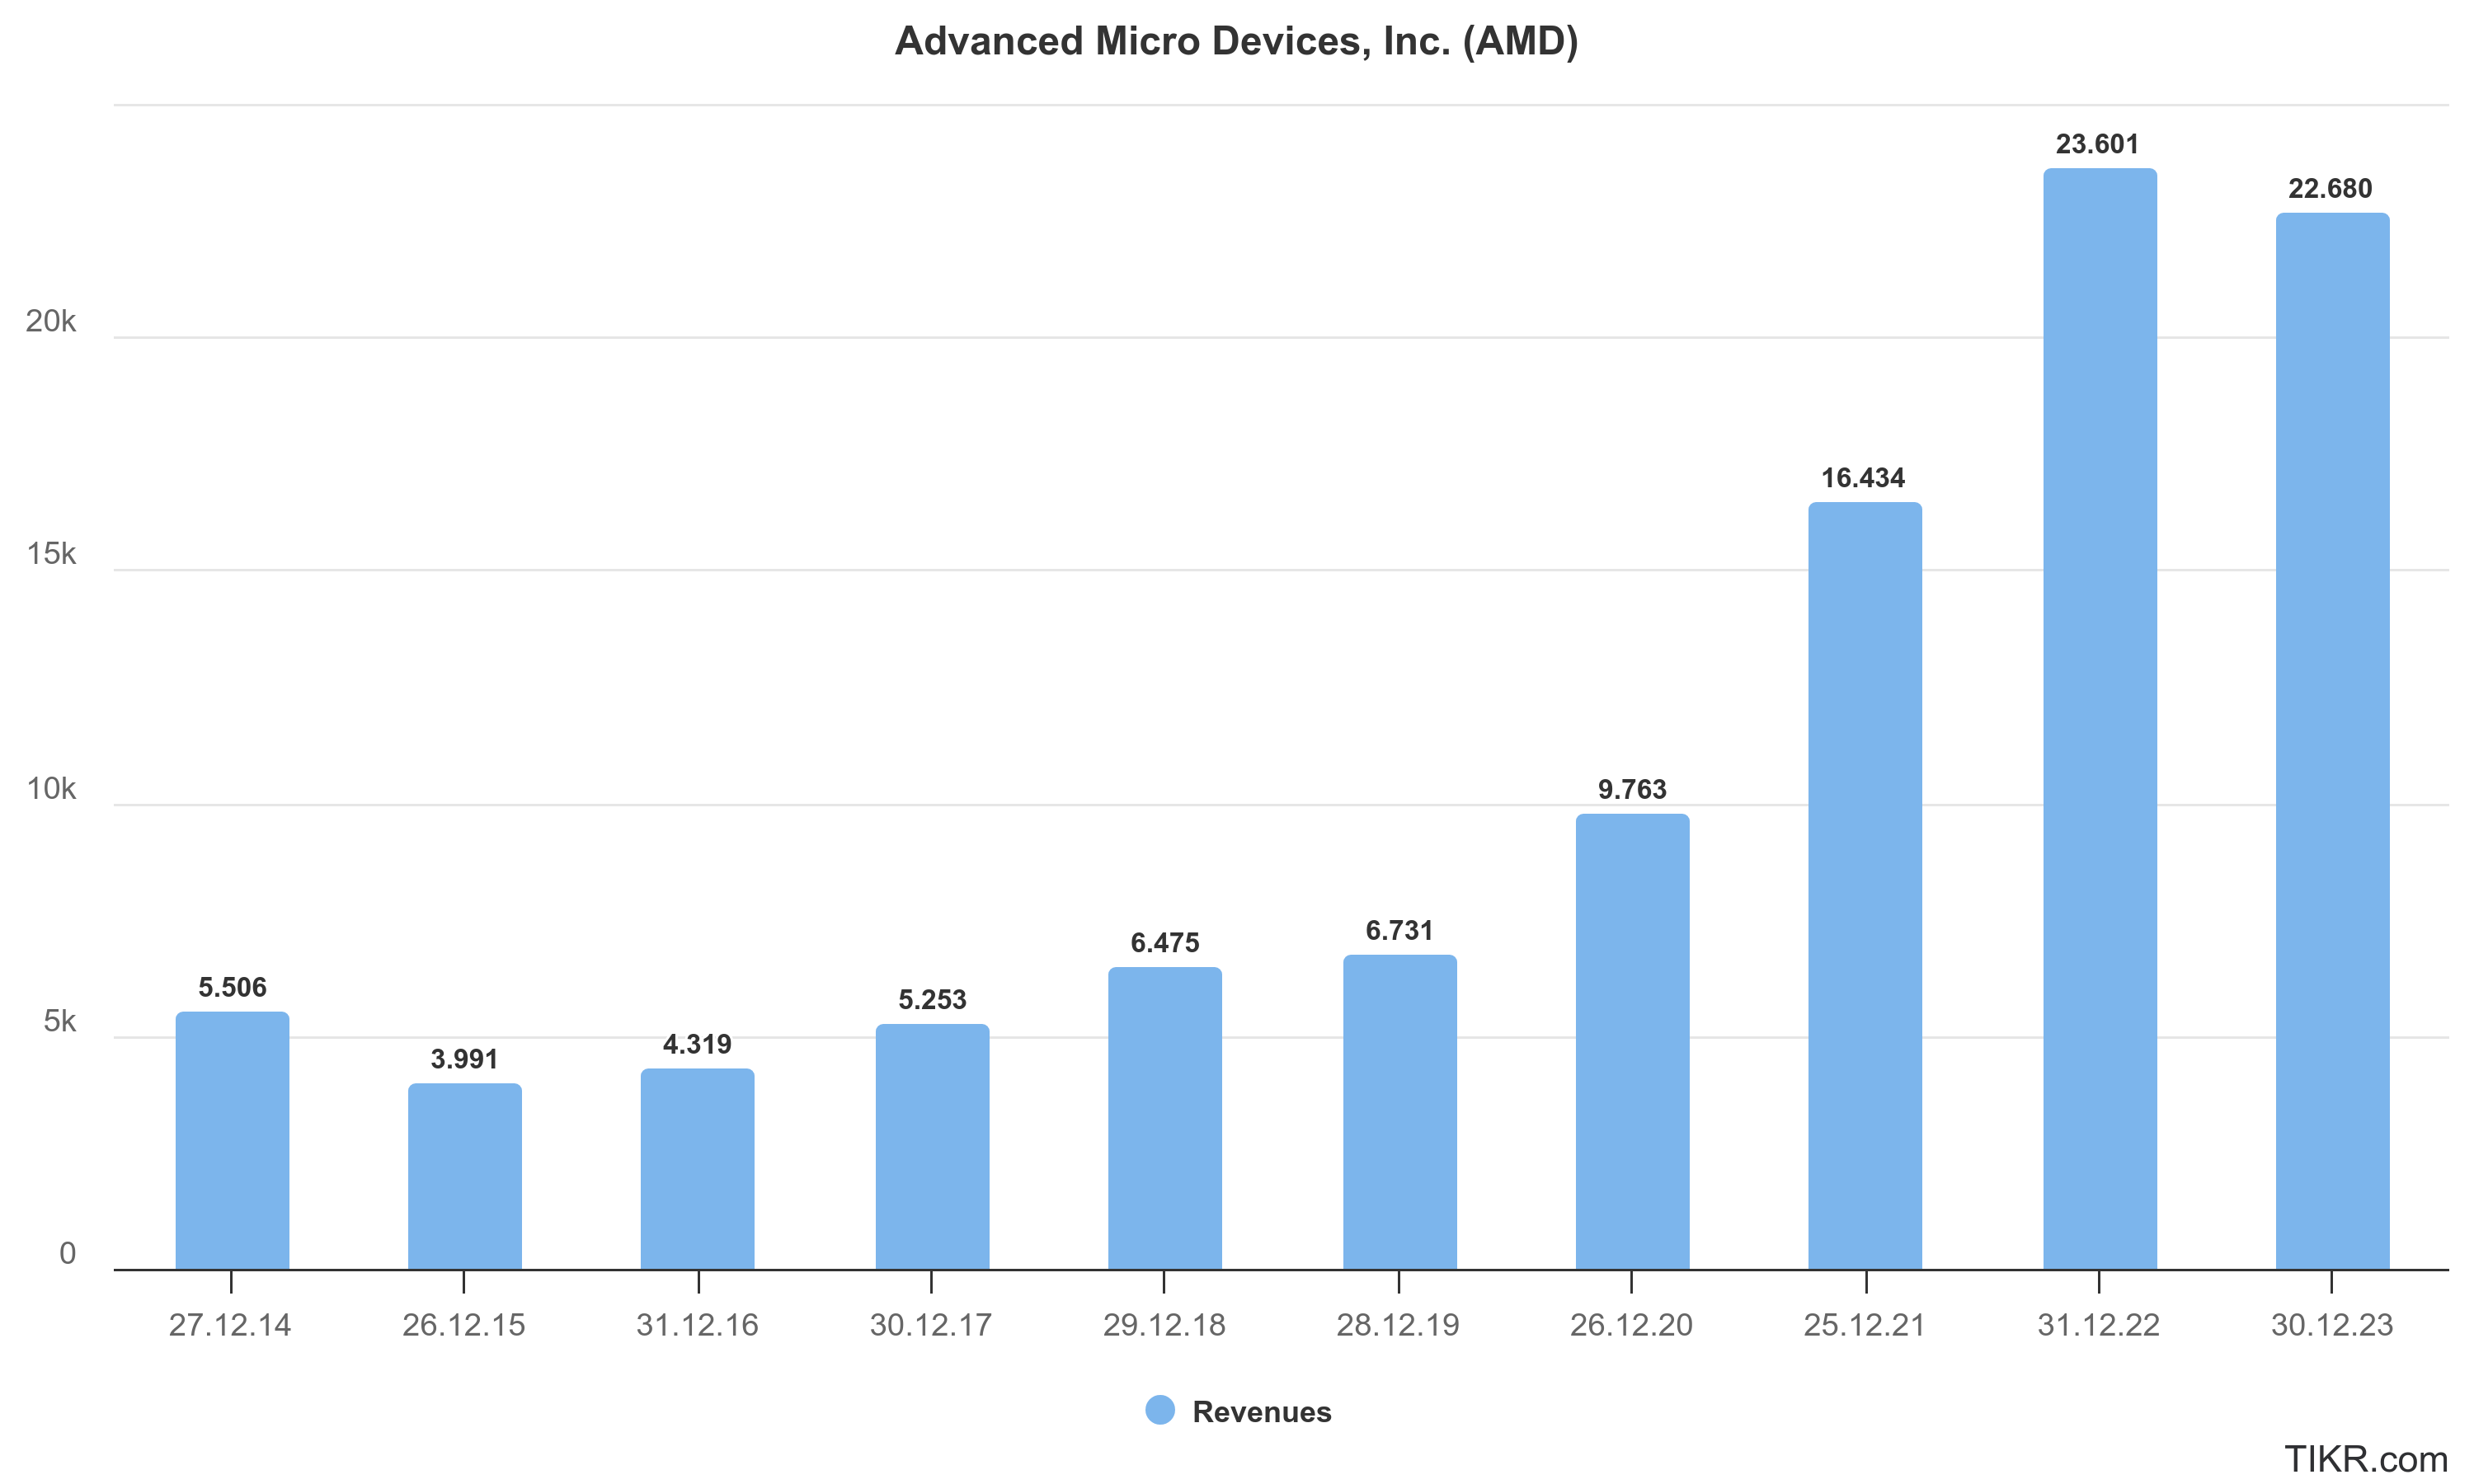
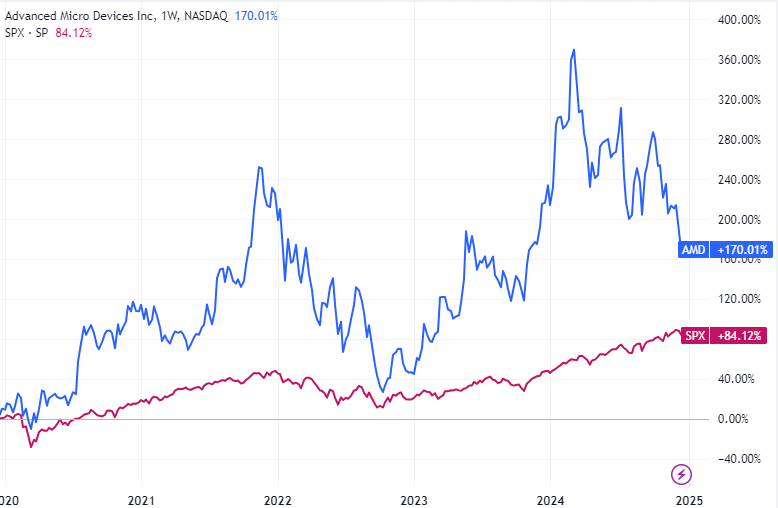
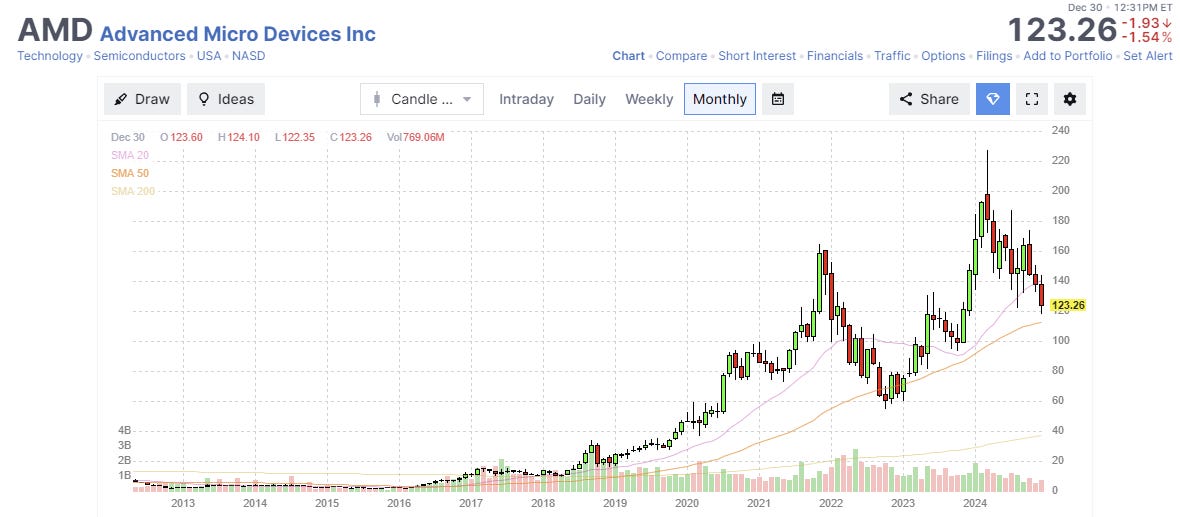
Talking about volatility: The share price of AMD resembles a rollercoaster with all its fun and terror. You are in for a ride when you invest in AMD.
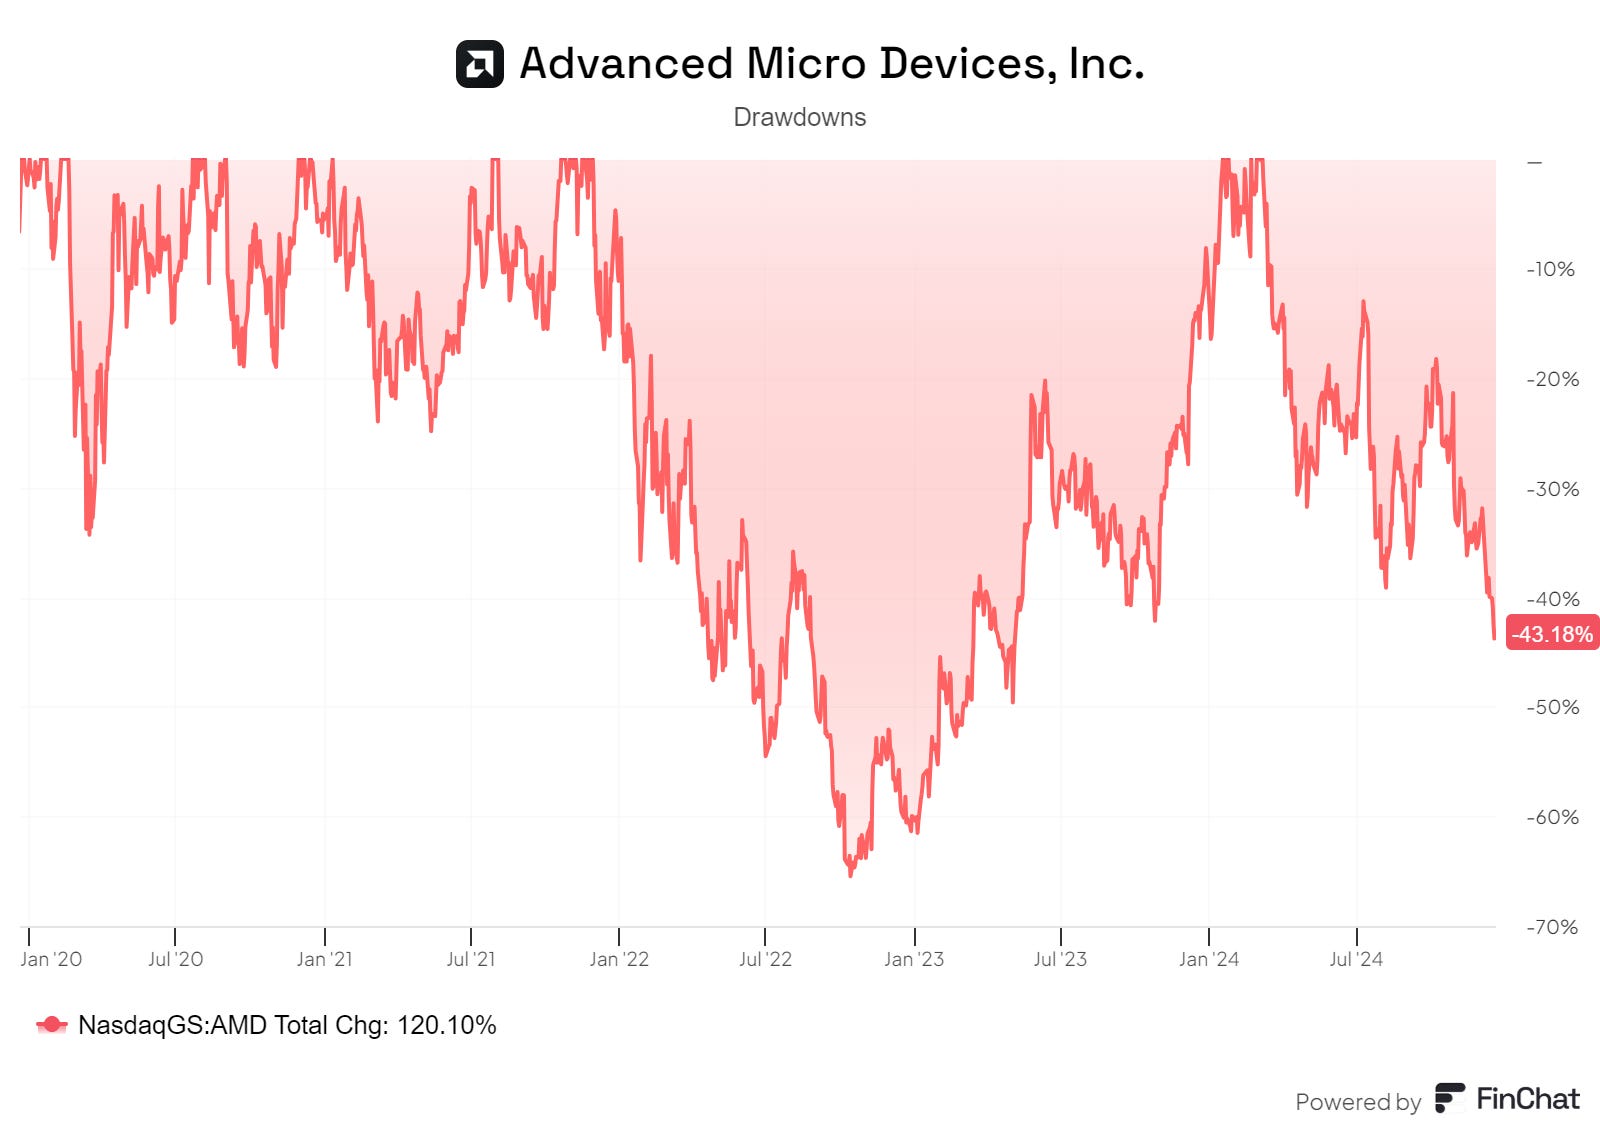
Large drawdowns are common. You as the investor therefore pose a risk to yourself, if you sell during one of these drawdowns. That’s why it is so important to know why you invest in a certain company and that is also the reason why I write these articles.
As with most advanced semiconductor companies, AMD is highly dependent on Taiwan Semiconductor. Should China invade Taiwan, the production of AMD products will collapse. This will be most likely one of the lesser worries that we will have if there is a Taiwan invasion…
CEO Lisa Su also addressed this topic in one earnings call. Supply is very critical for AMD.
“From a supply chain standpoint, our goal is always to build more supply.”
Another risk is the fact that companies such as Alphabet, Amazon, and Meta are working on their own AI chips to decrease their dependence on suppliers, especially NVIDIA. This increased competition will also impact AMD. However, I believe the market is so large, that these companies will first and foremost work on satisfying their hunger for chips and the market is large enough for AMD, NVIDIA, and others to co-exist.
Lastly: AMD has a couple of large customers. Should Sony suddenly decide that the PlayStation 6 will use Intel chips instead of AMD chips, this will lead to a large negative effect on AMD’s revenue (as of today reports say, that AMD won the deal for the new SoC for the PlayStation 6 over Intel).
The Fundamentals
Income Statement
Revenues have been growing at a stellar pace and are up six-fold since 2015. The gross margin has improved over the years and hovers around 50% these days. The gross margin is expected to increase in the upcoming years.
The increase in revenue came at a cost of increased operating expenses and especially the R&D expenses have been rising rapid pace, due to higher headcounts and increased focus on AI investments. The takeover of Xilinx in 2022 added a large block of operating expenses. The operating margin has been fluctuating strongly in the last years and largely depends on what grows faster: Revenues or expenses.
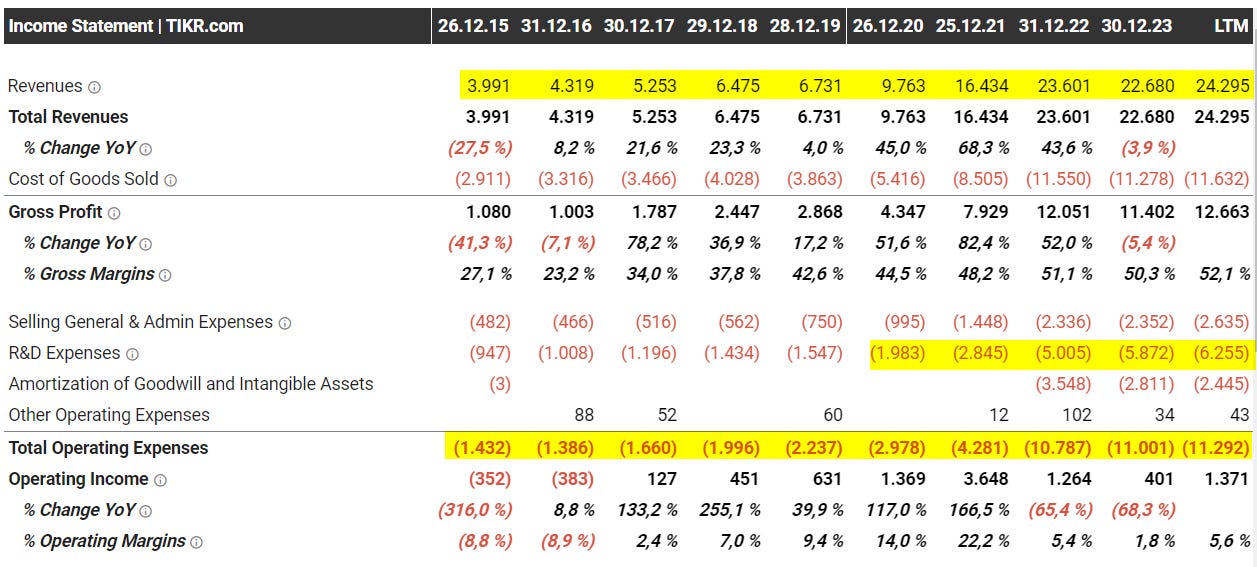
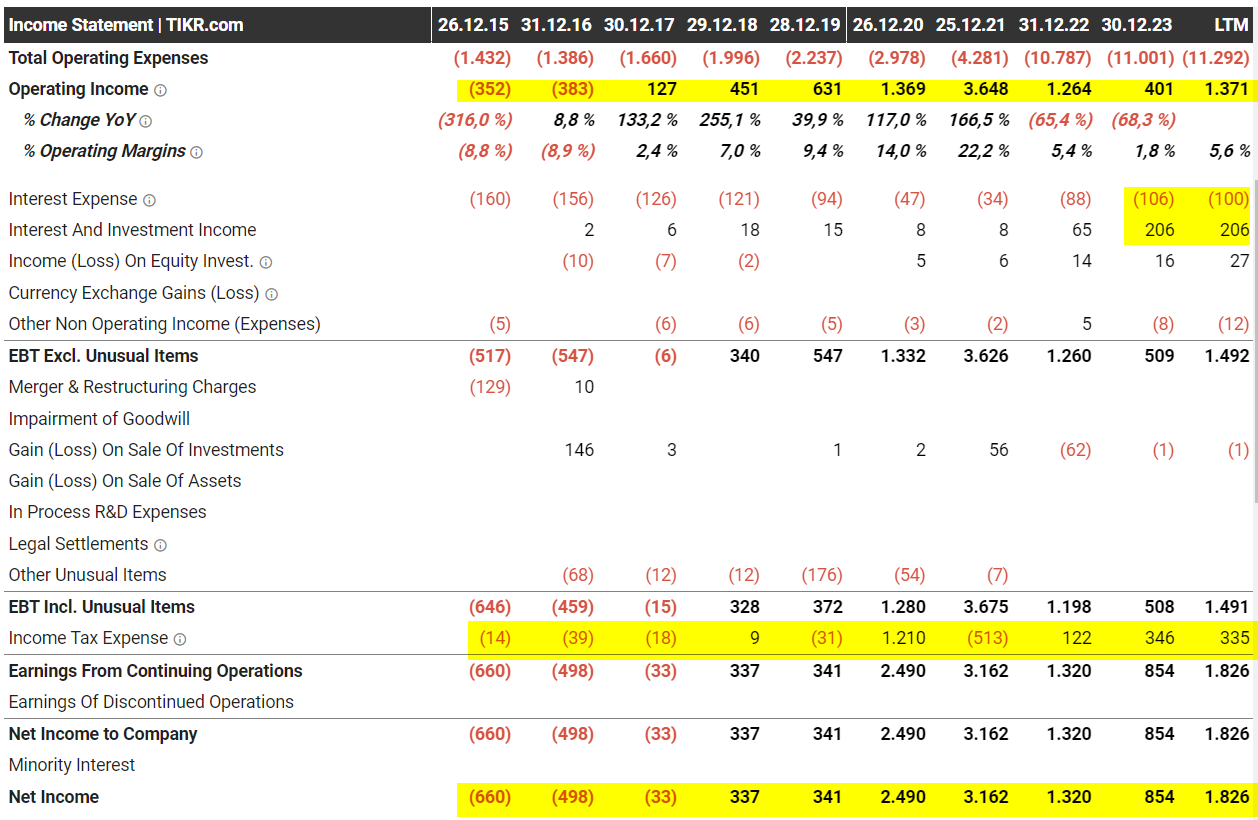
AMD’s income statement is interesting since its net income is higher than its operating income. In 99% of the cases, it is the other way around. Here the reasons are: higher income from interest than interest expenses in the last two years and positive (!) effects from income tax expenses in most of the last years. The large positive tax effect in 2020 was due to a tax benefit from valuation allowance releases in the US.
The $346 million of tax benefit in 2023 resulted from foreign-derived intangible income tax benefits and $169 million of research and development tax credits.
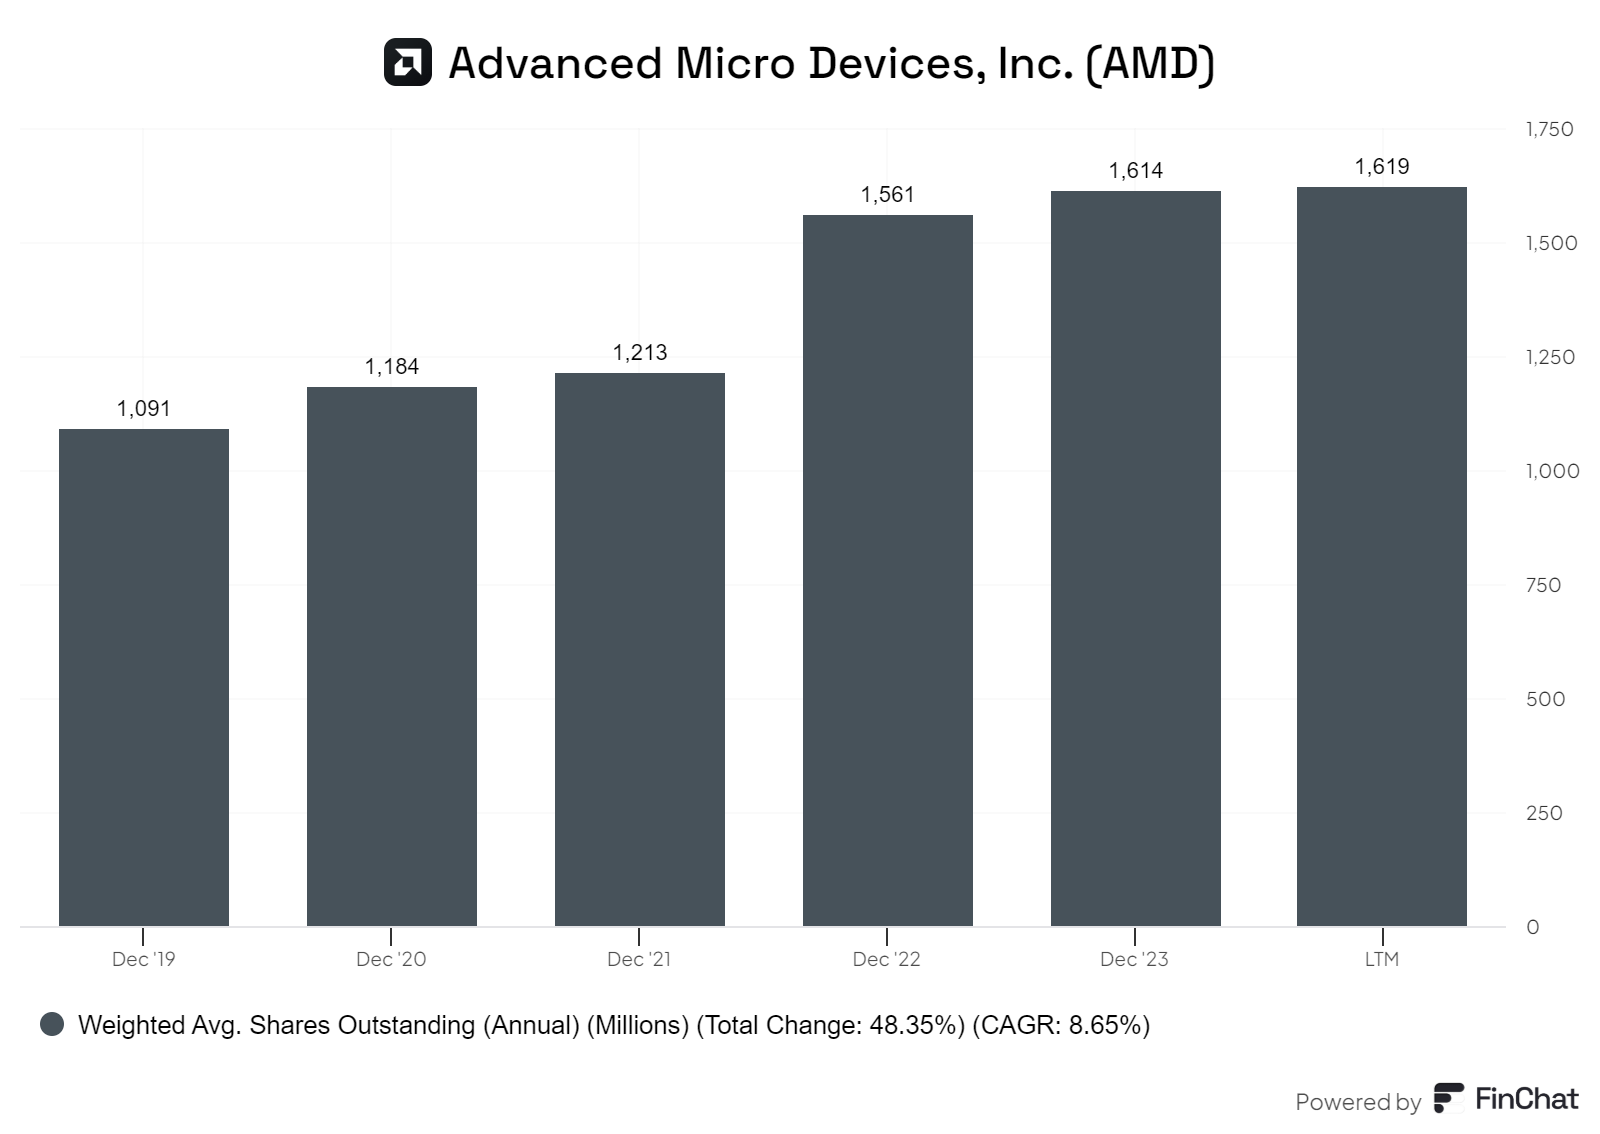
One point of criticism: I don’t like the development of outstanding shares at AMD. The large increase came from the Xilinx takeover since a part of the deal was paid in shares. The generally high amount of stock-based compensation (SBC) keeps diluting current shareholders. More ob SBC later.
Balance Sheet
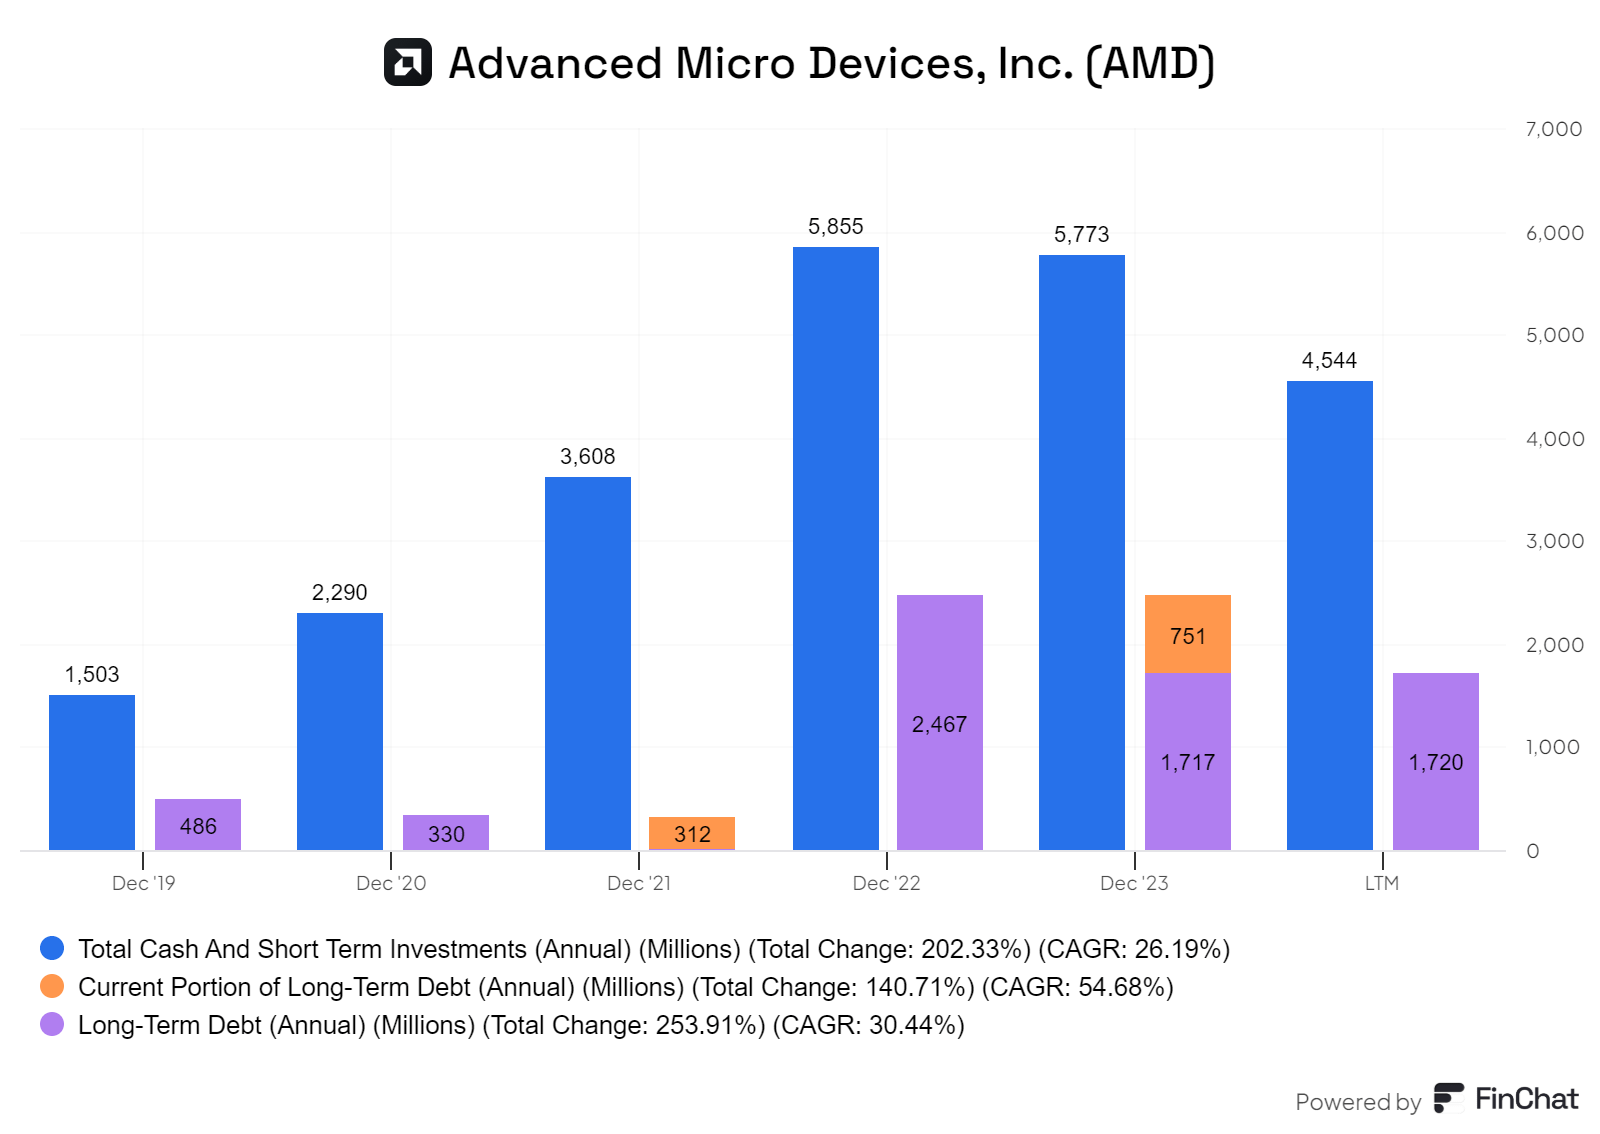
The balance sheet is healthy with more cash and short-term investments than debt. This surplus of cash over the debt was also the reason for the higher positive income from interest compared to the interest rate expenses for the debt.
Most of the $24.8 billion in goodwill carried on the balance sheet is from the Xilinx takeover, which contributed $22.8bn in goodwill.
Cash is held in money market funds and directly in US government securities. The outstanding debt is due far in the future
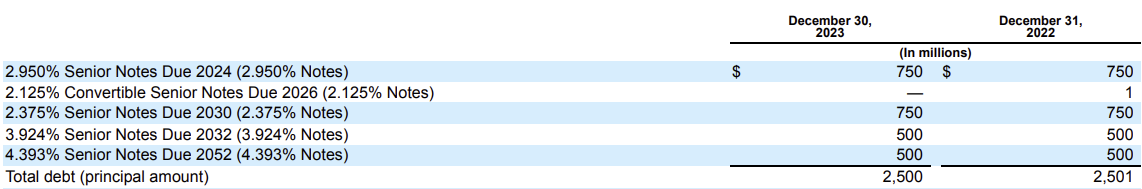
Cashflow statement
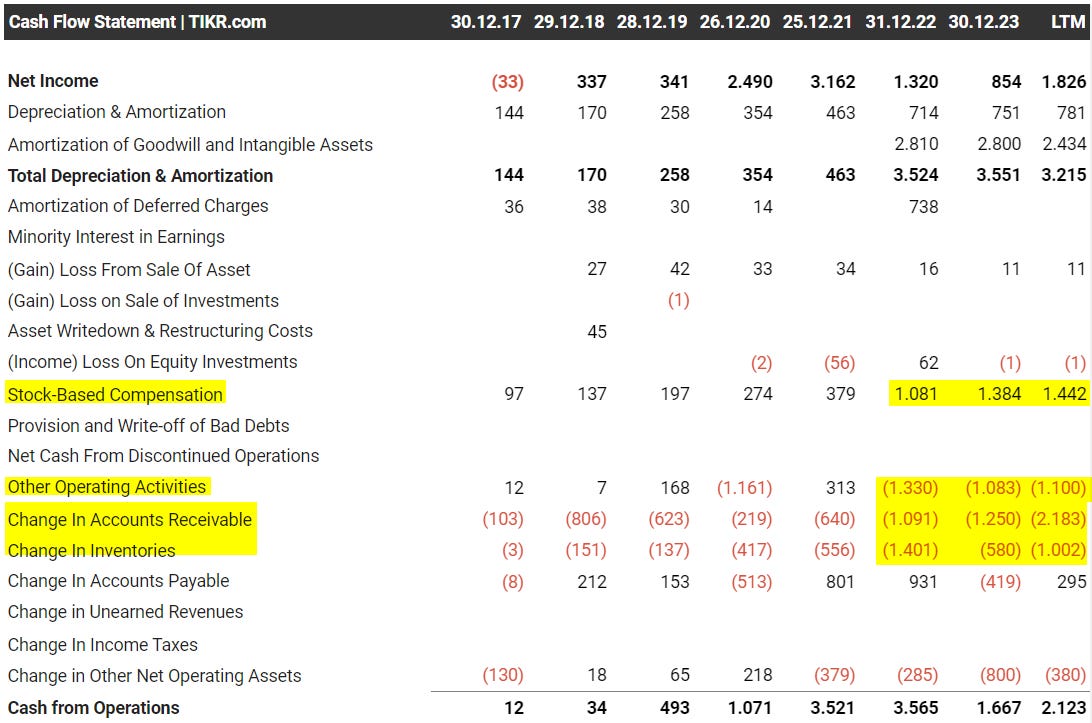
AMD’s cash flow is driven up by the high amount of depreciation and amortization as well as the (unfortunately) very high SBC. The increase in accounts receivable as well as inventory build hurt the cash flow. I wouldn’t worry about these two items since they are normal when a business, just as AMD, is growing at such strong rates.
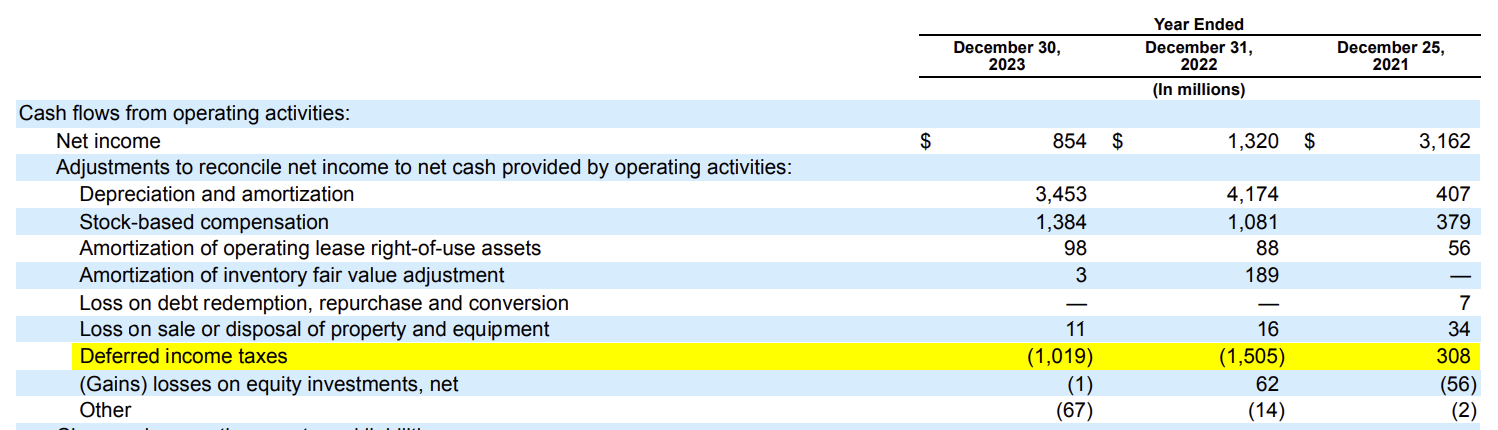
One interesting line here is dubbed “other operating activities”. I went through the annual report to discover what is hiding behind this term. These are mostly the changes in deferred income taxes. These are deducted from the net income since these are funds that have never flown.
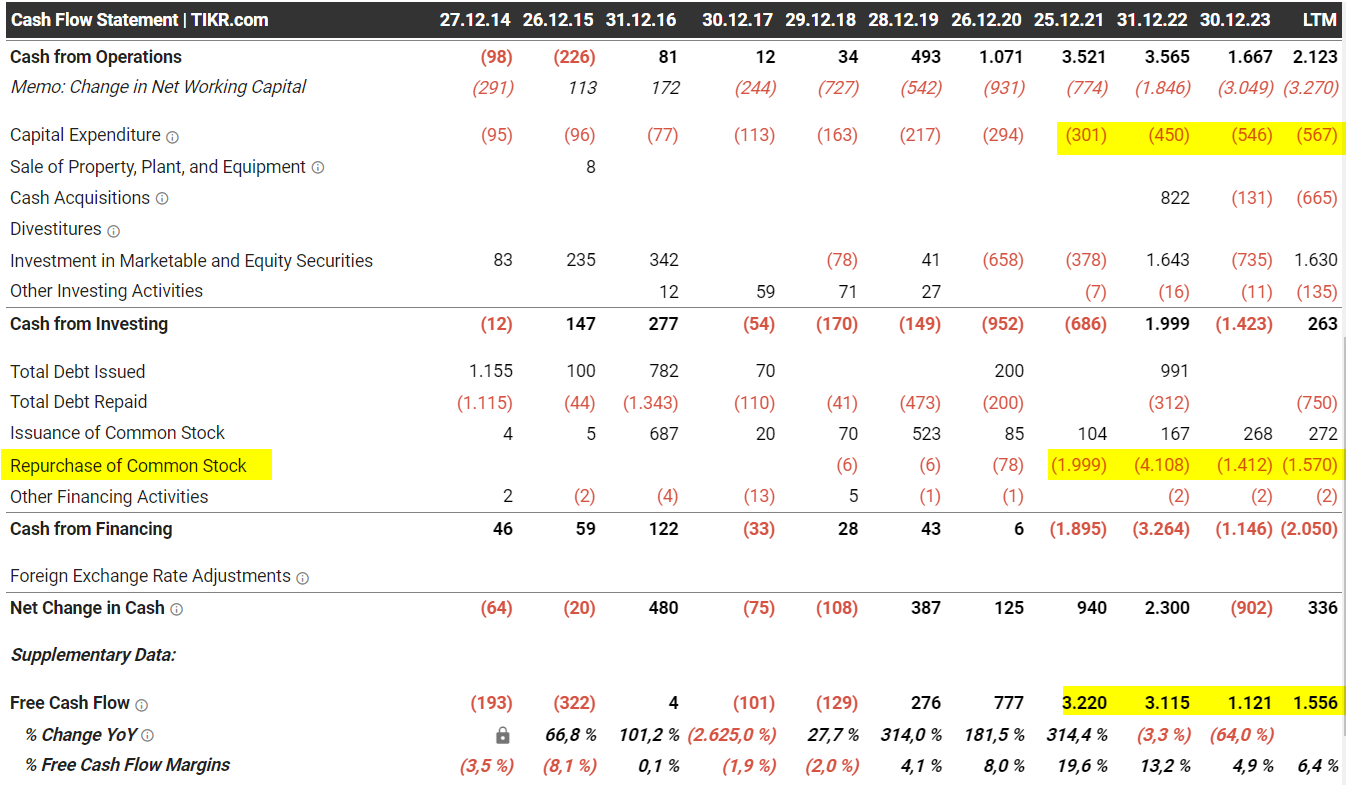
Capital expenditures increased in the last years and free cash flow has been positive since 2019 but fluctuating strongly. As you see, since 2021 AMD spent ~$9 billion on share buybacks to keep the excessive SBC partially in check. As of October 2024, $4.9 billion in share buyback authorization was still open.
Valuation
Coming now to the tricky part of this article. Based on the outlook for the industry, accelerated AI developments, and AMD’s positioning this company has everything that I am looking for as an investor. The current valuation however is far away from anything that I would normally write about.
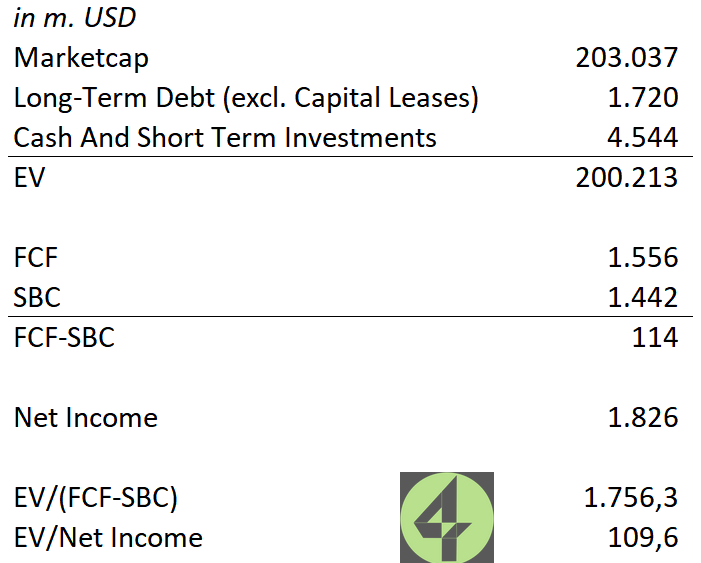
As of today (the 28th of December 2024) we are looking at an EV/(FCF-SBC) of 1756 and an EV/net income of 110.
Now that you have read the article I can hear some of your thoughts like “Hey 41, you always talk about buying great companies at a reasonable price. AMD is currently priced at a P/E of 112, the SBC that you quite often criticize is also fairly high, and on top of that AMD is very active in takeovers which adds certain risks. So why exactly is this interesting now?!”
Good that you ask, dear reader! The expected (very high) growth combined with improving margins in a market that is poised to grow makes AMD very interesting today. The strategy to be the provider of whole AI data centers instead of just providing the chips is very compelling and so far AMD’s track record has shown that the company is following a clear vision instead of just randomly buying companies.
CEO Lisa Su is very bullish on the demand for AI accelerators:
“In the Data Center alone, we expect the AI accelerator TAM will grow at more than 60% annually to $500 billion in 2028. We -- to put that in context, this is roughly equivalent to annual sales for the entire semiconductor industry in 2023.”
Q4/2024 revenue is expected to be $7.5 billion based on strong growth in the data center and client segments. FY 2025 revenue is expected to further increase based on strong data center revenue growth and a rebound in the embedded segment.
Here are the revenue estimates for the next two years. Revenue is expected to grow in the high 20s.
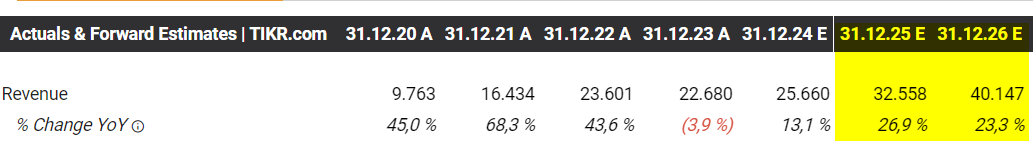
The new MI325 GPU was launched in Q4/2024 and the MI350 will follow in 2025. The increase in revenue is further supported by the increase in the gross margin. This leads to an estimated revenue in 2026 which is 5x the revenue of 2024
FCF is also expected to grow at high rates.
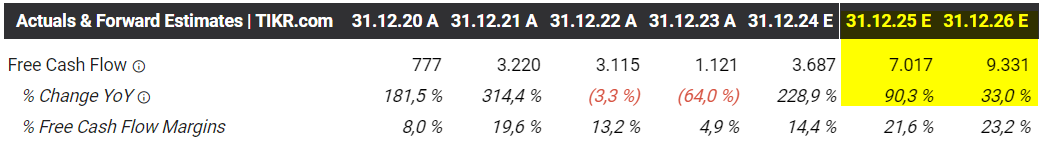
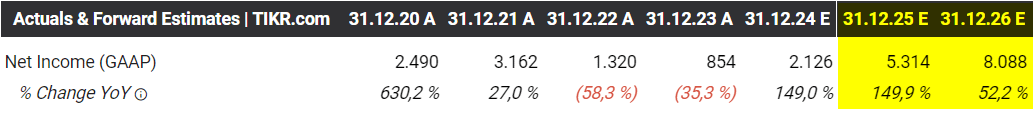
Using the valuation above and plugging in the net income and FCF for 2026, we suddenly arrive at an EV/FCF of 21.8 (SBC is not deducted) and an EV/net income of 25. Quite a few estimates already expect EPS of $5.1 for 2025 and therefore a P/E of 24.5 for next year. This seems very reasonable given AMDs positioning and the strong underlying growth of the industry.
Conclusion
Given the strong fundamental development of the company, a growing market, and its relatively cheap forward P/E I believe that AMD is very interesting at these levels.
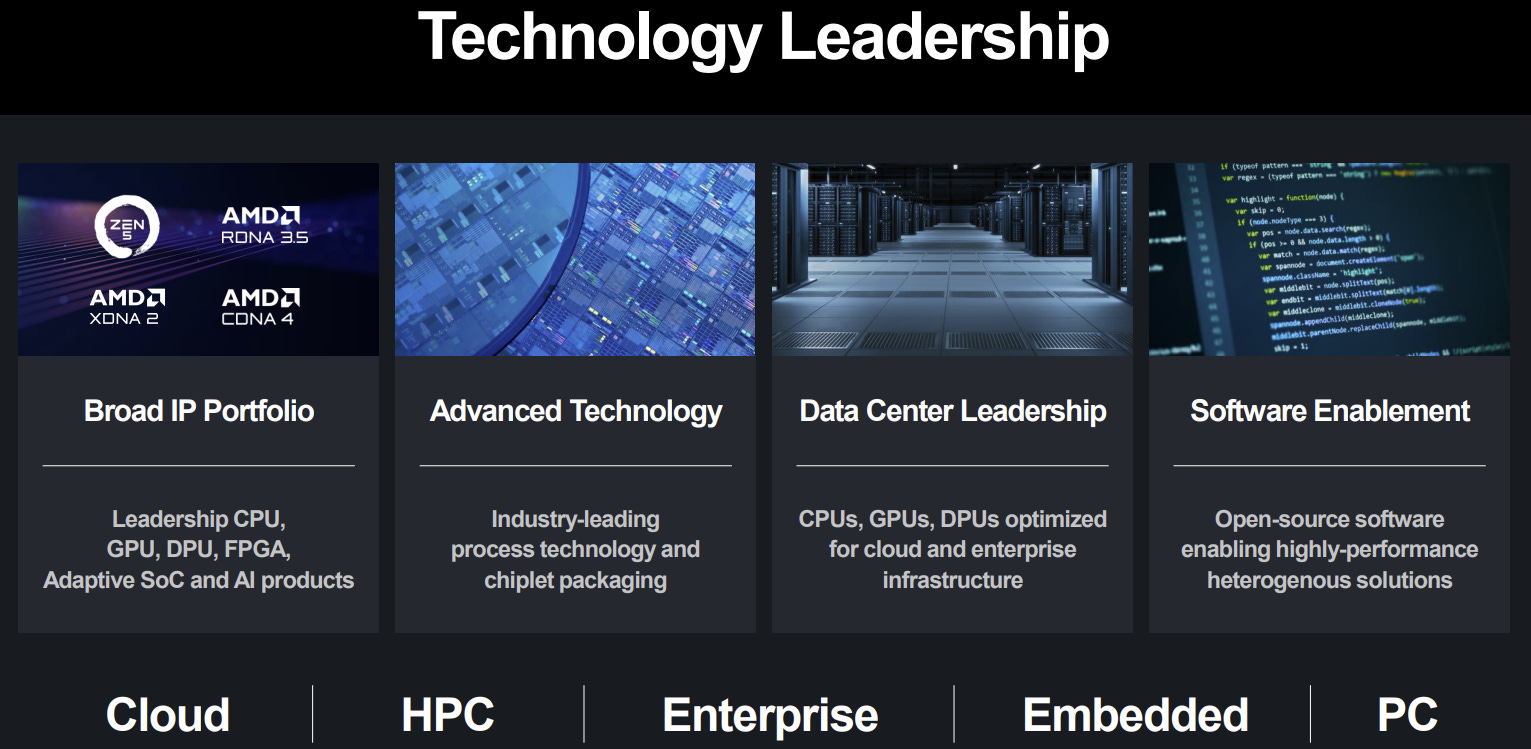
Many market observers have yet to realize how strong AMD is going in the GPU market. The launch of the new MI325X is directly aiming to take market share from NVIDIA’S newest Blackwell GPU. NVIDIA has seen gross margins of 75% and the MI325X might put some pricing pressure on NVIDIA’s GPUs and convince some customers to opt for the cheaper AMD chips. Keep in mind, that NVIDIA has more than 90% market share for AI data center chips. Just taking an additional 5-10% of that market share will add tremendous revenue to AMD’s topline. At the same time, the market keeps growing at a rapid pace. On top of that, you can expect the gaming and embedded segment to contribute to the growth in the upcoming years.
Once the momentum changes and the expectations are adjusted, AMD will look cheap at these current levels. Even AMD’s management was surprised by the strong data center GPU revenue. Data Center GPU revenue was expected to be $2 billion for 2024 at the start of the year and AMD expects it now to be roughly $5 billion. These are the kind of surprises you are looking for as an investor.
Writing a deep dive takes me 40+ hours to get a proper understanding of the company and the attributes of the industry it is working in. You will support me a great deal if you a) subscribe to this substack and b) recommend this blog to your friends and family. To all existing subscribers: Thank you for your support! :)
Stocks in this article:
AMD 0.00%↑ NVDA 0.00%↑ MSFT 0.00%↑ AMZN 0.00%↑ GOOG 0.00%↑ TSM 0.00%↑ ASML 0.00%↑ NFLX 0.00%↑ META 0.00%↑ EA 0.00%↑ INTC 0.00%↑ HPE 0.00%↑ ORCL 0.00%↑ AAPL 0.00%↑ TSLA 0.00%↑
Please subscribe to my substack and follow me on Twitter/X if you like my work: https://twitter.com/41investments
If you like this post, check out my previous deep dives on
Adobe: https://41investments.substack.com/p/adobe-fundamental-deep-dive
American Express: https://41investments.substack.com/p/american-express-deep-dive
Axcelis: https://41investments.substack.com/p/axcelis-stock-analysis-deep-dive
Evolution: https://41investments.substack.com/p/evolution-ab-deep-dive
Expedia: https://41investments.substack.com/p/expedia-deep-dive
Fortinet: https://41investments.substack.com/p/fortinet-stock-analysis-and-deep
InMode: https://41investments.substack.com/p/inmode-deep-dive
Markel: https://41investments.substack.com/p/markel-deep-dive
MercadoLibre: https://41investments.substack.com/p/mercadolibre-deep-dive
Texas Pacific Land: https://41investments.substack.com/p/texas-pacific-land-deep-dive
British American Tobacco: https://41investments.substack.com/p/british-american-tobacco
Invest at your own risk, this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
41
I am sharing my dcf tomorrow. Shares trading at slight discount to intrinsic value.
I started a 10-k analysis on AMD, so maybe you’ll be interested to check it out?