

Invest at your own risk; this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
In this short format, I want to present to you companies and stocks, which are currently valued at an attractive level. Writing a deep dive takes me many hours and with this format, I can introduce you to interesting ideas as of today.
I will only recommend high-quality businesses and I am not interested in cheap, but mediocre companies. Always keep in mind, that the quality of the company is the first filter. If it does not possess a very good business model, I am not interested in the company, even if it is dirt cheap. With that being said, let’s start!
Both companies presented today are among the largest holdings in my portfolio and I have added to both in the last weeks.
If you say this looks familiar to the best buys of October, you are certainly right. Most companies that I keep track of are too expensive at the moment and only those two stand out.
Alphabet
Investing doesn’t have to be hard. I bet all of you know and have used Google for the last 15+ years. Compared to that, most people kept searching for the next star instead of just buying Alphabet. Consider me one of these investors, before I finally saw the light and bought Alphabet shares in 2018 as a long-term holding and not just as a trading position.
To google has become a synonym for searching for information online. Now add YouTube, Google Maps, etc and you will find many apps that you can’t imagine living without. That’s a great fundament for a company and therefore an interesting investment.
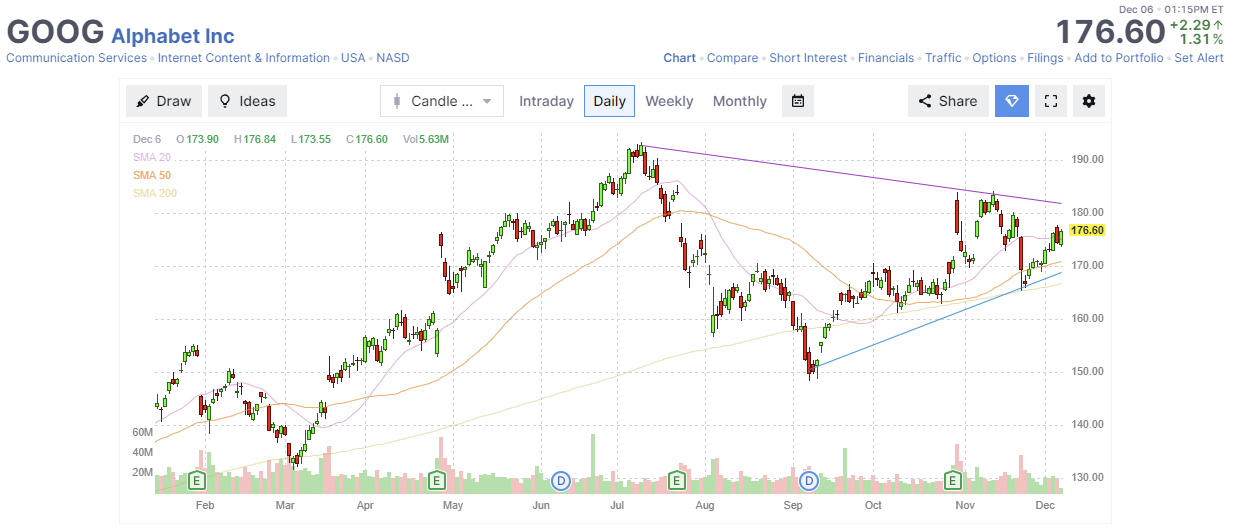
Where it gets interesting is the fact, that the stock of Alphabet, the holding company of Google is significantly cheaper than the broad market, even though it is one of the very best companies. The forward P/E of Alphabet is 19.6 vs a P/E of 24 for the S&P500. That does not even include the large cash pile of Alphabet.
The US Justice Department is pondering a breakup of Alphabet and this has put pressure on the stock. I would not worry too much, since a) such a breakup would take many years and b) the individual parts of Google might be worth more than the sum.
Alphabet’s self-driving subsidiary Waymo is doing extraordinarily well and keeps expanding into new cities. As of today, San Francisco, Austin, Los Angeles, and Phoenix are served by Waymo with Miami starting soon.

Google Cloud keeps growing both on a revenue level and even more important, the business is now contributing billions in profit to Alpahebt. Many companies would kill for owning such a cash-generating machine.

And then there is YouTube. YouTube keeps growing and I am a paying subscriber since you can’t use it anymore without being a paid subscriber due to all the ads. From Alpahbet’s point of view this is intentional: Either generate money through advertisements or make recurring revenue from paying subscribers. What a fantastic business model.
Compared to Amazon Prime, Disney+, Netflix, etc, Alphabet pays a fraction for the content. The content is generated for free by the many users and the payouts to these users are minimal compared to the revenue they generate for Alphabet.
YouTube (black) is consistently gaming market share in streaming hours of US TV time.

At the same time, YouTube even overtook the OG of podcasts, Spotify, to become the most-used platform for podcast listeners. The podcast industry keeps growing and so does YouTube’s relative and therefore absolute share.

All of this combined leads to an ever-increasing advertising revenue for YouTube. Considering that Google paid back in 2006 $1.65 billion for YouTube, this must be counted as one of the steals of the century.

If you sum it all up and reflect on the strength of the business and the moat of the company you would guess, that Alphabet must be quite expensive. The good news is: that the valuation is very cheap. Alphabet is currently trading at an EV/net income of 22 and forward P/E of just 19. I am aware that an EV/(FCF-SBC) of 63 does not look cheap. The current high spending on capex (most of it is AI-related) has a huge toll on the FCF. I believe, however, that this spending will increase the moat of Alphabet even further.
On a forward P/E level Alphabet is fairly cheap.

I believe in a couple of months a lot of investors will look back and will be surprised, that they missed buying Alphabet at such a great price.
ASML
Moving on to a company with an even larger moat than Alphabet. ASML is yet another marvelous company. Finally, a high-tech company from Europe, to be more precise the Netherlands. Without ASML you would not have the modern chips in your smartphone, computer, or any top-notch GPU. ASML is one of these companies that I followed for years before finally buying shares in the second half of 2022.
This video gives a good overview of ASML. Even if you know the company, it is worth your time.
ASML has a monopoly on EUV technology and is the only company in the world that can produce 5 nanometers (nm) and 3 nm process nodes. Even if a Chinese company could get its hands on all the building plans for this machine, the process of manufacturing and sourcing the individual parts is so complex (maybe even impossible), that they are not able to just build one of their own.
The newest high-NA EUV machines cost around $380m per piece and the foundries can’t wait to get their hand on one of these. ASML has a very long runway and it is the most important company many people have never heard of. Luckily for us, we can buy shares in this fantastic company. Even better yet, the shares are at an attractive level at the moment.
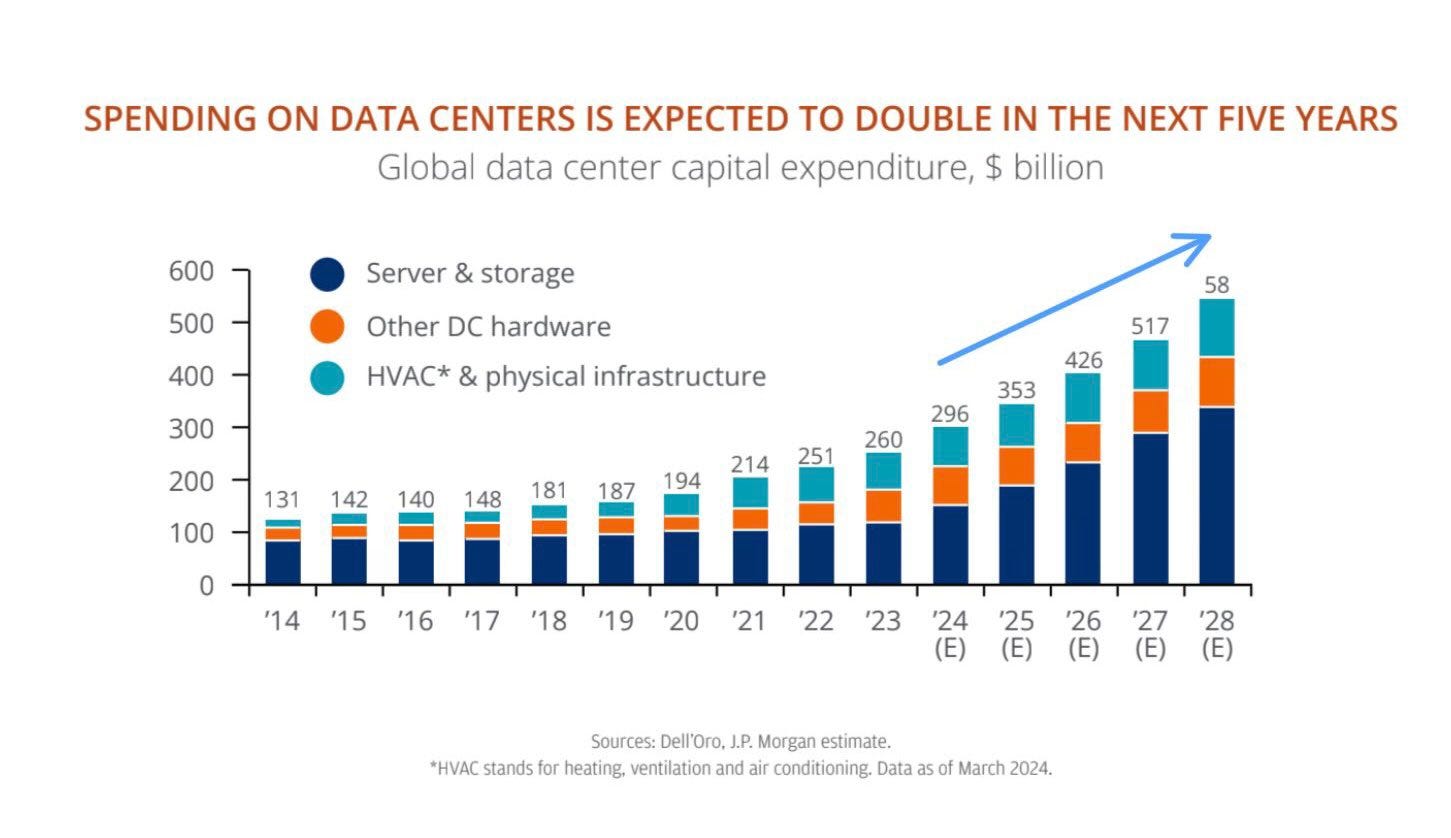
Meta, Alphabet, Microsoft, and Amazon keep spending massive amounts of money on data centers, and indirectly a lot of this spending will benefit ASML, since ASML provides the machines that manufacture these chips. The trend will accelerate in the upcoming years. These two graphs give you a good indication of what is happening in this field.

With a forecasted EV/Net income of just 23 in 2 years and an EV/FCF of 51 in 2 years I am a happy buyer at these levels. Companies like ASML rarely come cheap, but there are moments of relative undervaluation. If you have missed those in the past, now is your chance to buy some ASML.
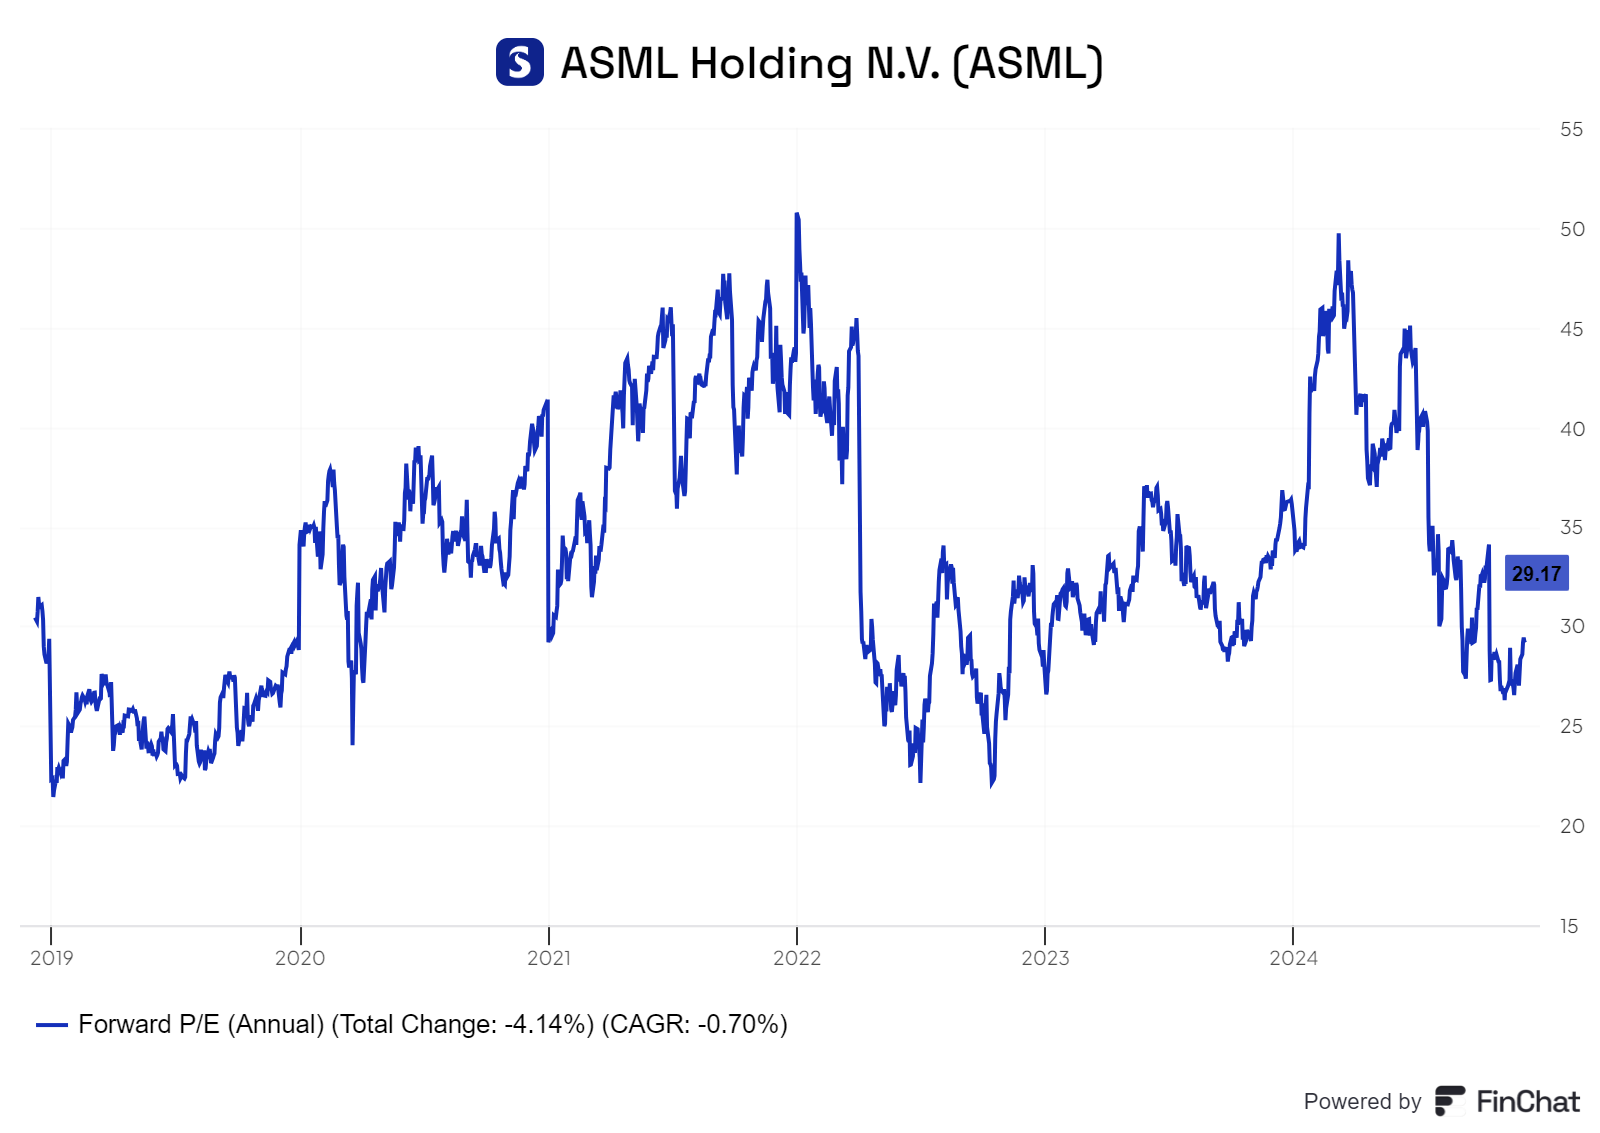
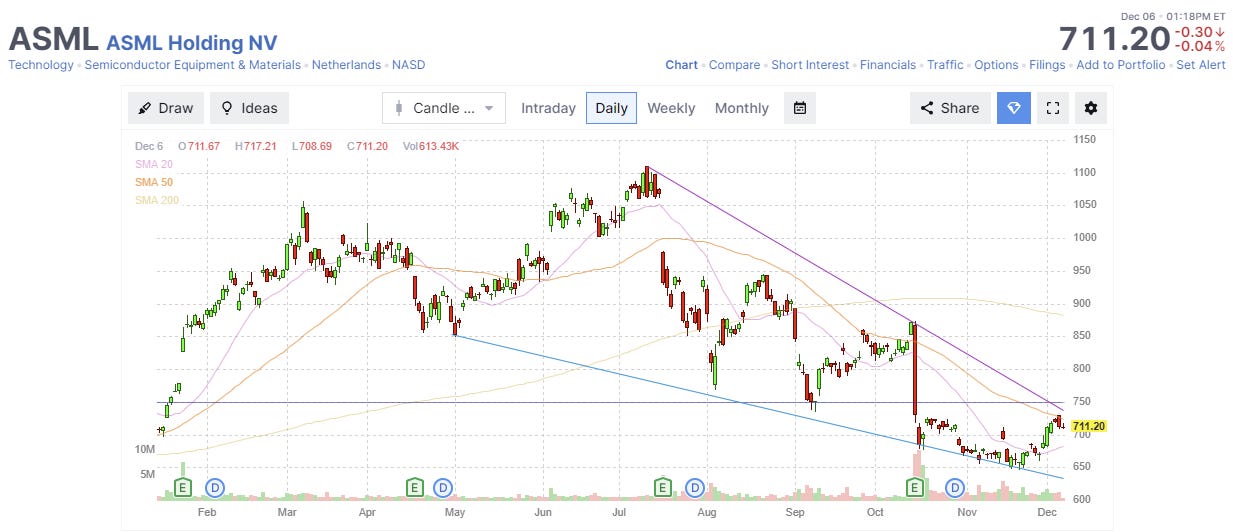
The best part: Since I wrote about ASML in October, the stock price has come down further and now you can buy this fantastic company at an even better valuation. Black Friday indeed.
Cleaning up
This is not your typical buy, but I am using the chance of the record highs in the broad market to clean up and streamline my portfolio. As part of this, I am selling holdings, where the position is either too small for me to invest significant time in tracking it or it is a position which I don’t intend to hold for the long run. Maybe this applies to you as well.
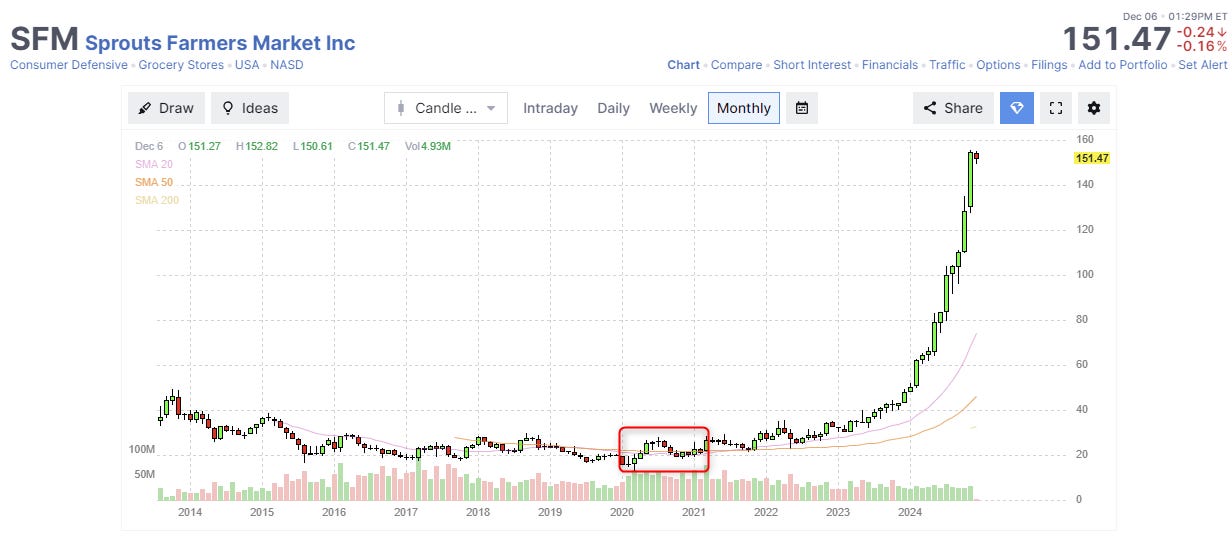
Personally, one of these cases for me was Sprouts Farmers Markets. I have sold a portion of my holding because the valuation reached a crazy point. The chart gives you a good indication of this run. I bought my shares back in 2020 and I am more than happy with the outcome.
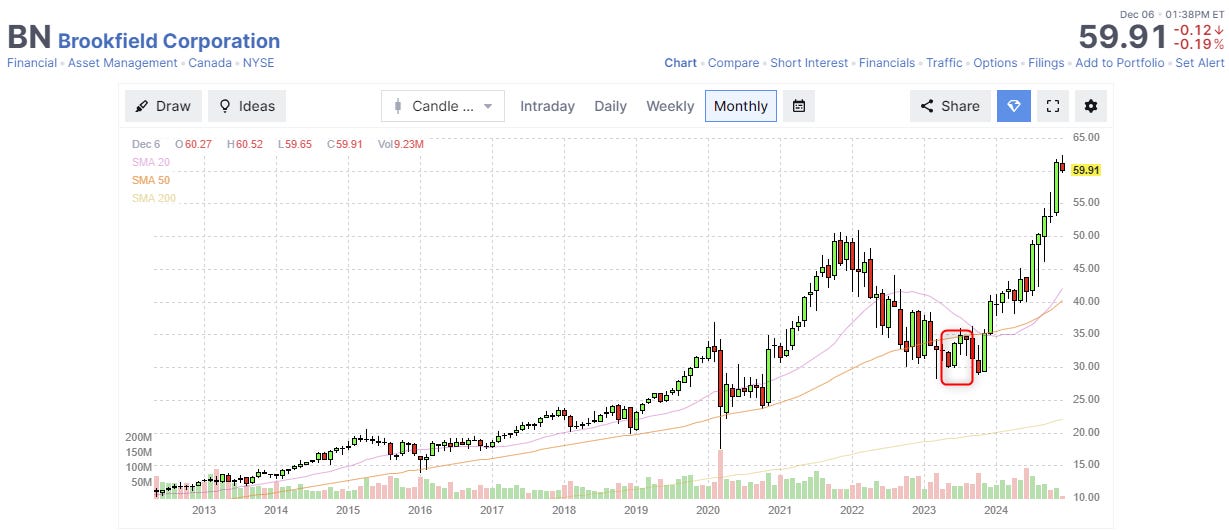
Another company that I completely sold was Brookfield. Brookfield is a fantastic company and I bought my shares in May/June 2023. After the recent run, I decided to sell my shares at $59. Due to the nature of the business, it is very hard to value the business itself and I rather invest my time in companies where I have a better grasp of the business. I might come to regret this at some point in the future but there is only so much available and I believe I can use it in a more sensefull manner.
Did you sell any companies recently? If so, which companies were those and why did you sell them?
That’s it for today. Let me know if you own any of these companies and which stocks you are looking into right now.
If you haven’t done so already, please follow me on twitter/x and reshare this post so it can reach more people.
Invest at your own risk, this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
41