

Invest at your own risk; this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
PayPal released its Q3 earnings on the 29th of October. Let's dig in:
Management’s summary
That’s how PayPal describes its results:
“PayPal delivered strong financial and operating results during a highly productive third quarter. We are making solid progress in our transformation as we bring new innovations to market, forge important partnerships with leading commerce players, and drive awareness and engagement through new marketing campaigns. We are raising our full year non-GAAP guidance and are pleased with the strength we are seeing across the business. We’ve built a solid foundation in this last year that will serve us in the years to come.”
Income Statement
The growth in revenue is slowing down (bad), while the gross margins are increasing (good). Combined this leads to an increase in Gross Profit, which is partially offset by rising operating expenses and leads to a small increase in operating income. The interest income from funds held on behold of customers rose again to $183 million in the quarter, but at the same time, the interest that is paid on the company’s debt also rose.
Together we arrive at the effects from FX losses and losses on the sale of investments at a net income that is slightly below last year’s Q3. I was hoping to see better traction here.

Balance Sheet
Cash and short-term investments decreased to $11.9 billion and net debt (cash minus debt) was -$517 million. Other current liabilities (these are mostly funds held on behalf of customers) were mostly flat at $41.2 billion and have the lovely characteristic, that PayPal keeps the interest paid on those cash balances.

Cash Flow Statement
The effects from the originating and selling effect of the BNPL (buy now, pay later) portfolio largely occurred from Q2 2023 to Q4 2023. The amount of Stock-based compensation is declining (great news) and the operating cash flow has been ok. Keep in mind, that Q4 is always the strongest quarter of the year to do the shopping season for Christmas and Black Friday.

Capital expenditures are still quite high for a software company.
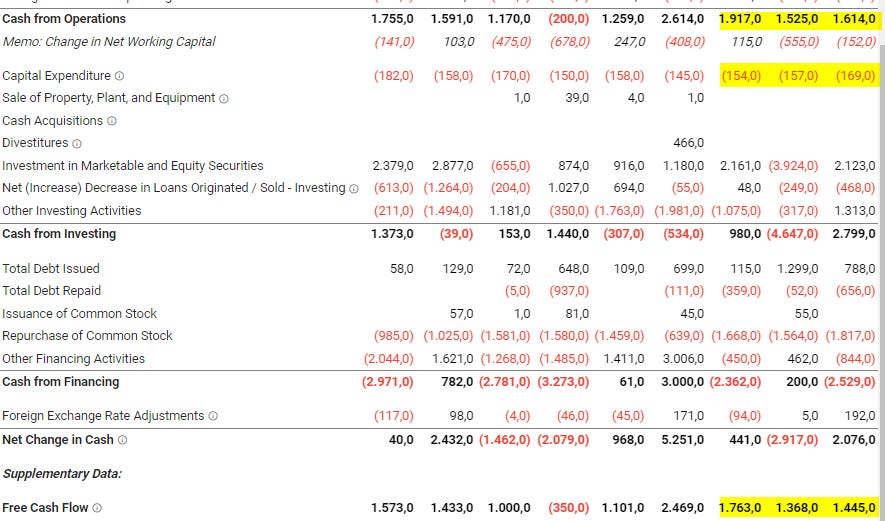
$1.8 billion in share buybacks in Q3 and a total of $5.4 billion in the last twelve months. That is huge! To be fair, these massive buybacks were partially offset by still high SBC, which was $1.3 billion in the last 12 months. Net buybacks of $4.1 billion were still quite something.
Operational metrics
If you want to read the full article and learn about the management, the composition of the segments, takeovers, risks, fundamental analysis, and a conclusion please subscribe and support my work. To all existing subscribers: Thank you for your support and enjoy the rest of the article!
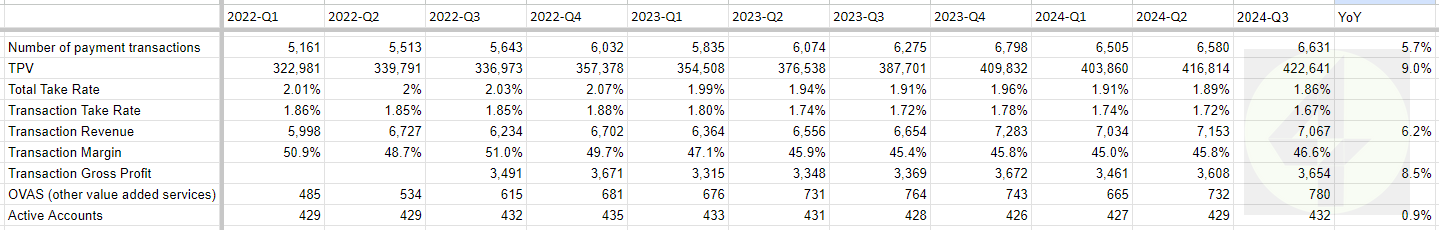
These are the metrics I keep an eye on when analyzing PayPal’s business. The number of payment transactions was growing, as well as the total payment volume (TPV). Unfortunately, the take rate keeps going down and therefore the transaction revenue grew slower than the TPV. In Q3/2024 the transaction revenue was even lower than in the previous quarter, even though the TPV rose. A good sign is the stabilizing transaction margin, which in turn led to a slightly increased transaction gross profit.
TPV (+9%), transaction revenue (+6.2%), and transaction gross profit (+8.5%).
The number of active accounts has been mostly flat in the last quarters.
The reason for the decrease in the take rate was given by the management:
Transaction take rate declined by 4 basis points to 1.67% compared to a 3 basis point decline last quarter. Improvements in Braintree and Venmo monetization benefited transaction take rate. These were offset by large enterprise and marketplace growth within branded checkout, foreign exchange and faster payouts growth.
Guidance
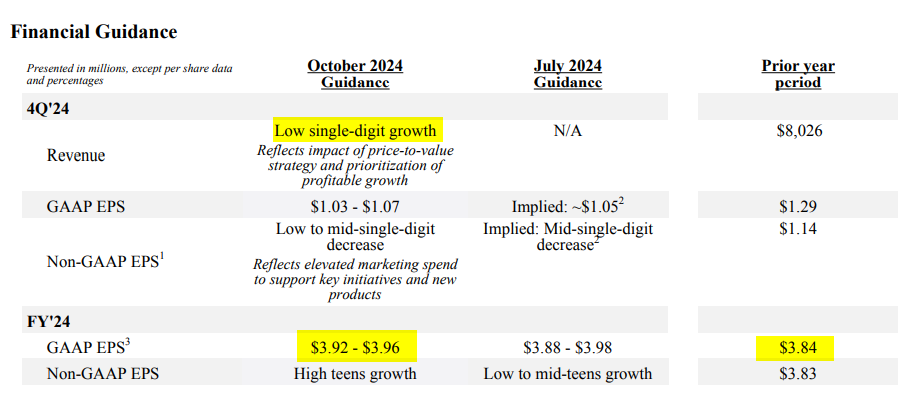
The given guidance is quite disappointing. Only low single-digit growth is expected for Q4 Revenue vs Q4 last year. The EPS is expected to rise at the midpoint jof ust 2% for 2024 vs 2023. Considering that the amount of outstanding shares has actually fallen by 7% in the last four quarters, the operating business is making less money in absolute dollar terms. The earnings per share are only going to rise because the net income is divided by fewer shares (due to the buybacks)
Here are some quotes from the earnings call regarding the guidance:
For the fourth quarter, we expect revenue to grow by a low single-digit percentage. This is directly related to Braintree merchant negotiations and ongoing efforts to drive quality, profitable growth.
As I mentioned earlier, this is a deliberate action and a continuation of the strategy we've articulated throughout the year, where we have accepted a lower near-term Braintree revenue profile in exchange for better margins as we have renegotiated agreements
We expect higher non-transaction OpEx growth in the fourth quarter as we have intentionally concentrated more of our discretionary investment spend, particularly in marketing, during the back half of the year and in the holiday season. This is strategically timed to support key initiatives, including the go-to-market of new products and innovation, as well as ongoing marketing and brand campaigns for PayPal and Venmo.
Through the first 3 quarters of the year, growth in interest on customer balances and improvements to transaction loss were an approximately 4-point percentage benefit to transaction margin dollars. Beginning in the fourth quarter, we expect minimal benefit from growth in interest on customer balances and then a headwind beginning in 2025 due to interest rate cuts
The part which I put in italics is very crucial for PayPal. PayPal has been profiting massively from the high interest rate they were earning on customers balances and this interest income is one of the reasons why the transaction margin dollars have been rising nicely. Without this, the growth will be a lot slower.
But the way to think about it when you're thinking about '25 is, a 25 basis point rate cut equivalent to about $40 million of transaction margin.
This means, that each 25bp interest rate lowers the transaction margin dollars of PayPal by roughly 1%.
Product
More partnerships, interestingly also with direct competitors such as Adyen.
As we shift from a payments company to a commerce platform, more of the world's leading commerce players have partnered with us to add value for our mutual customers. In just over 2 months, we've announced partnerships with Fiserv, Adyen, Amazon, Global Payments and Shopify, and we're actively discussing more collaborations across the industry. These new and expanded relationships are a clear demonstration that our brand, innovations and momentum are resonating.
We also recently announced a partnership with Amazon to bring PayPal Checkout to SMBs offering Buy with Prime. Next year, we will expand our work together to give Prime members the option to link their Amazon and PayPal accounts so that consumers can receive Prime shipping benefits when they use PayPal while shopping with Buy with Prime. While it will take time to realize, there is significant opportunity here, and more we can do to better serve the needs of small businesses.
The scale of consumers who are primed to spend with PayPal puts us way ahead of other guest checkout solutions, and it is one of the reasons why so many platforms are choosing to partner with us. We can't wait to get Fastlane into the hands of more merchants, not only on Braintree and PPCP, but also through our partnerships with Fiserv, Adyen and Global Payments next year.
PayPal is working on new features so that consumers interact more often with PayPal directly and therefore drive further adoption.
…launch of PayPal Everywhere. This initiative builds on PayPal's established brand position as an online shopping powerhouse to position PayPal as the go-to solution for spending, sending and earning rewards, whether online or offline. We're doing this through cashback incentives on the PayPal debit card, a marketing campaign with the goal of reintroducing our capabilities to consumers who may never have thought about PayPal as more than an online payment option. We're starting to shift perceptions of PayPal and beginning to drive adoption of our suite of complementary products which all drive back to branded checkout.
With Venmo, we're making progress in executing our strategy to shift from solely a P2P service to a central part of consumers' financial lives. Our new leadership team is taking a fresh look at Venmo, and we're completely transforming and upgrading the user experience. We know that we inherited one of the strongest P2P brands and see an opportunity to prioritize innovations that unlock Venmo's value. We believe that Venmo will eventually have multiple monetization levers.
…innovation is the most durable competitive advantage we have. And what you've seen for us in the last few quarters is really starting to drive innovation, both on the consumer PayPal app, not just in branded checkout, but actually putting real innovation into the app with PayPal Everywhere launch, giving consumers the opportunity to now have an offline experience, which is driving habituation back into online, an enhanced rewards platform.
This last point I found quite amusing. Scheduled payments sound like an absolutely basic feature, but is now mentioned as an innovation.
And then on the Venmo side, leading in with innovations that, to be honest, customers have been asking for, for years with scheduled payments and groups and adding direct deposit.
Summary
I was hoping for better guidance, especially after the transaction margin finally improved. Unfortunately, the competition in the field is still strong and players like Adyen and others fight for market share. Therefore I expect the transaction margin to decline further in the upcoming years. Interest income on customer balances will be flat to slightly declining.
The years of super high growth for PayPal are over and given the characteristics of the market, I believe that you will find better companies elsewhere.
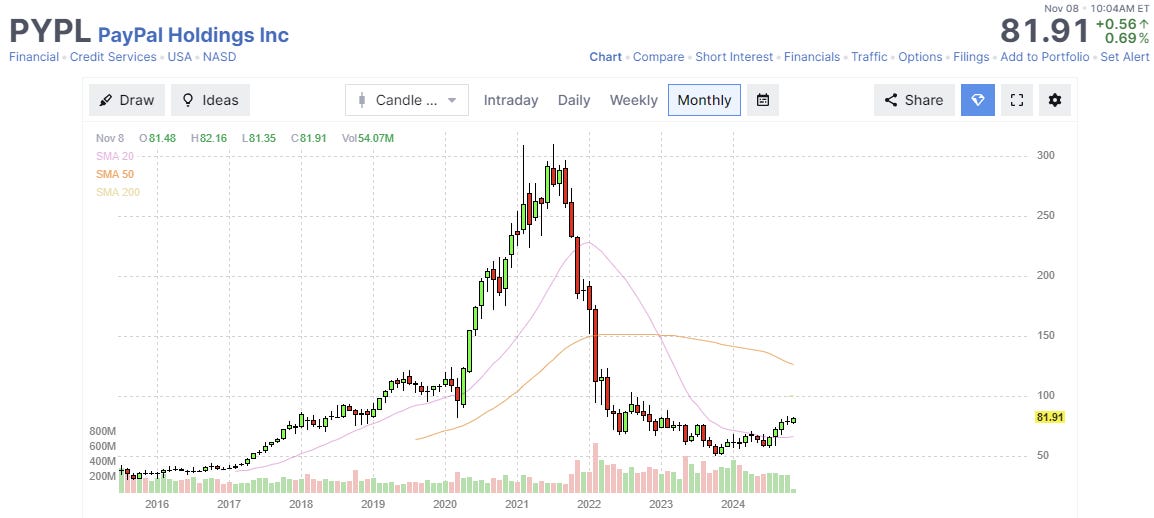
All of this does not mean, that the stock will now go down. The chart is looking better by the day and I would not be surprised if we see the $100 by early next year. The valuation is fair to cheap with an EV/net income of 18.3 and an EV/(FCF-SBC) of 14.2
If you haven’t done so already, please follow me on twitter/x and re-share this post so it can reach more people.
Please subscribe to my substack and follow me on twitter/x if you like my work: https://twitter.com/41investments
Invest at your own risk, this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.