

Invest at your own risk; this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
Hi and welcome to a new format.
I will write here a short summary and my thoughts on the most earnings call of some selected companies. Over the time I will add more summaries, so be sure to come back.
Adobe
New 25bn sharebuyback program is sufficient for 11% of all shares. 12% growth YoY. Firefly is now also used by enterprise clients such as IBM. 1bn breakup fee for the Figma deal. Management feels well prepared for AI for Creative and Documents.
Airbnb
Sales in 2023 +17% YoY. Very strong increase in G&A costs in Q4/23 due to one-off tax withholding (Italy). Interest income brings 720m of the 2.1bn operating income. One-off effect of provision from income taxes drives up earnings. New share buyback program of up to $6bn. A completely new product category is to be launched in the course of 2024
Alphabet
Google Cloud is profitable for the first time for the year. Almost the entire FCF was used for share buybacks. YouTube continues to grow strongly. Costs are now to be more tightly controlled. YouTube is the leader in U.S. streaming watch time.
At the current valuation Alphabet is very interesting. How often can you buy on of the best companies for an EV/Earnings of 25.6 with an expected EPS growth of 16%?
British American Tobacco
Dividend increases, debt decreases and shares are bought back. New Category profitable for the first time. Low single-digit sales growth for 2024. The average remaining debt term is 10 years. Debt to be further reduced and part of the ITC stake to be sold.
Expedia
7.5% of all shares redeemed in 2023 and a record result. CEO steps down after only 3 years. OneKey launch was successful. 30% fewer FTEs than in 2019. Debt stable at 6.3bn with 3.7% interest rate. Shares to be bought back further. Booking is the much better company
Fortinet
Billings growth weakens. Net income grows and outstanding shares fall. For 2024 hardly growing billings and +8% revenue expected. Service revenue continues to grow strongly (very good). Hardware is currently in a down cycle, which should end at the end of 2024. 2024 seems to be a transition year and I guess the guidance was defensive as usual and there is potential for positive surprises.
Kontron
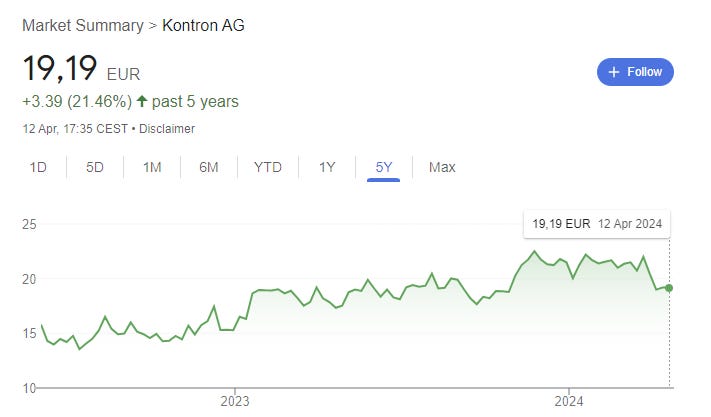
Strong sales growth and very strong outlook. If the targets set are achieved, Kontron is really cheap. I am somewhat cautious, as the share has been moving sideways for 6 years now
Palo Alto Networks
Continued strong billings & revenue growth. 1.5bn positive one-time tax effect this quarter, makes comparability difficult going forward. PANW sees further consolidation of the market (good for the big players like PANW). PANW wants to make the introduction phase easier for new customers in the future and these customers pay very little in the first few months; this will have an impact on billings growth in the next 12-18 months. After that, billings will increase more strongly again. Despite the changes, PANW is sticking to its EPS and FCF targets. For the time being, the impact will only be on billings. PANW sees AI as a major demand driver for cybersecurity
Paypal
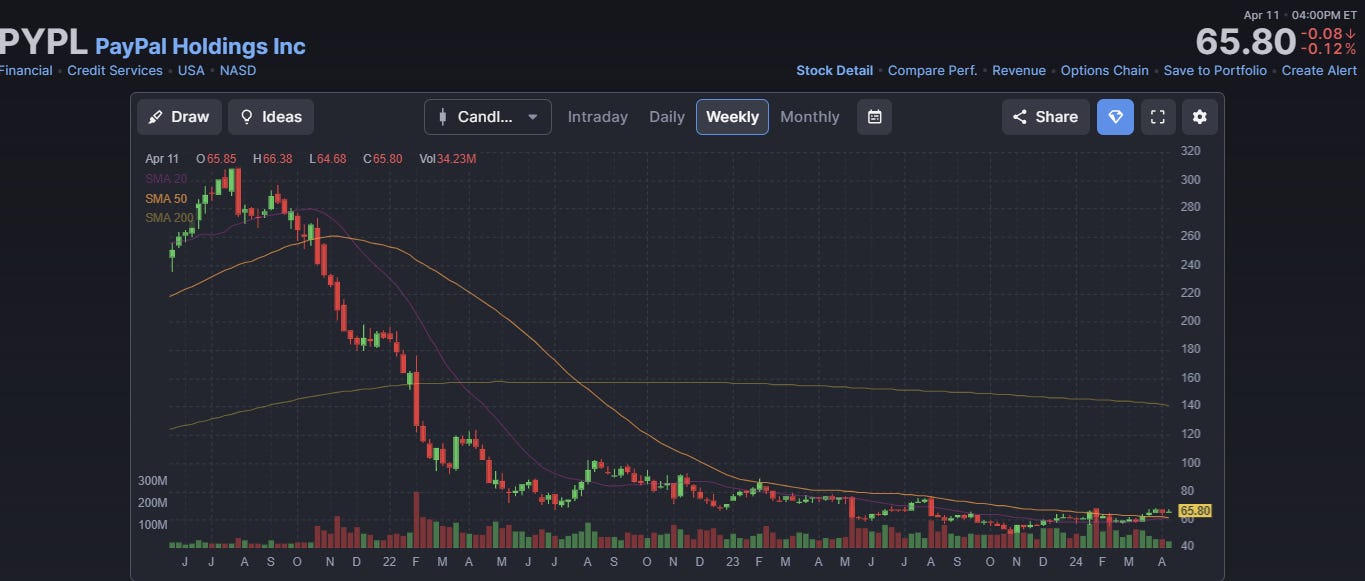
Revenue increases, but hardly any Gross Profit remains. Costs fall and net income rises due to strong interest income. Stagnating EPS expected for FY24, although approx. 8% of shares will be retired. With an EV/net income of 14.2, Paypal is still favorable, but earnings are hardly expected to grow. I don't like it that much. Then again the valuation is quite low and the chart finally seems to bottom out.
Texas Pacific Land
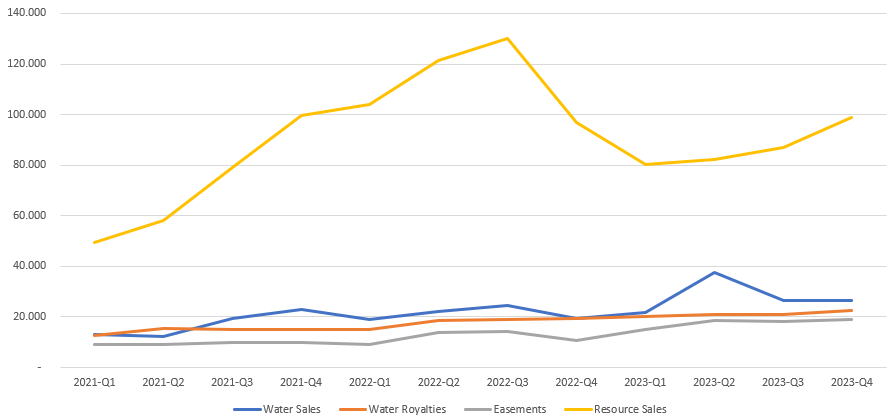
Water sales continue to rise sharply, as does the volume of oil produced. TPL wants to continue buying back shares as long as the price is attractive. If the share price is too high, dividends will be paid instead.
If you haven’t done so already, please follow me on twitter/x and reshare this post so it can reach more people.
Please subscribe to my substack and follow me on twitter if you like my work: https://twitter.com/41investments
If you like this post, check out my previous deep dives on
Adobe: https://41investments.substack.com/p/adobe-fundamental-deep-dive
American Express: https://41investments.substack.com/p/american-express-deep-dive
Evolution: https://41investments.substack.com/p/evolution-ab-deep-dive
Expedia: https://41investments.substack.com/p/expedia-deep-dive
Fortinet: https://41investments.substack.com/p/fortinet-stock-analysis-and-deep
InMode: https://41investments.substack.com/p/inmode-deep-dive
Markel: https://41investments.substack.com/p/markel-deep-dive
MercadoLibre: https://41investments.substack.com/p/mercadolibre-deep-dive
Texas Pacific Land: https://41investments.substack.com/p/texas-pacific-land-deep-dive
British American Tobacco: https://41investments.substack.com/p/british-american-tobacco
Amadeus FiRe: https://41investments.substack.com/p/amadeus-fire-deep-dive
Datagroup: https://41investments.substack.com/p/datagroup-deep-dive
Invest at your own risk, this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
41