
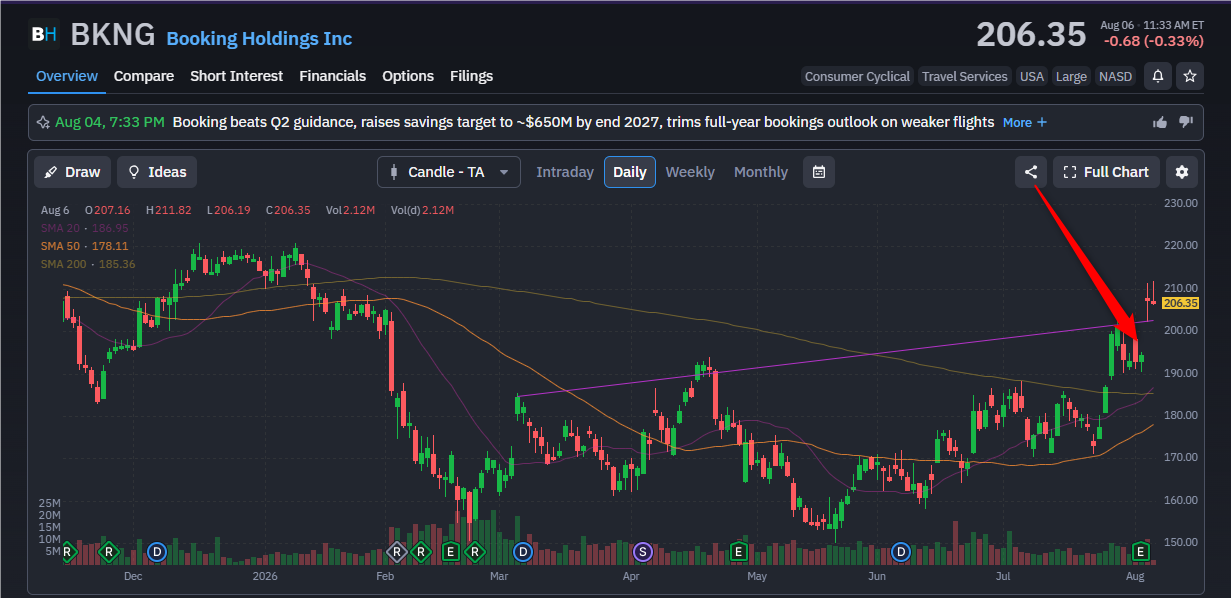
Summer is in full swing, and I assume some of you are on holiday right now (hopefully justified). I tend to book quite a large share of my trips through Booking, and Booking is also part of my portfolio. Booking released its Q2 earnings on the fourth of August. The numbers were well received; time to have a look at whether the +7% jump in the stock price was justified.
Before we jump into Booking, have a look at my take on Adobe’s most recent earnings release.
About the title image
The world is one big travel opportunity, and Booking connects it all. I have used Booking in almost every continent, and I keep coming back as a customer.
Talking about earning reviews: Find my Adobe earnings review here:
Adobe's Q2/2026 Earnings Review

It’s that time of the quarter again: Adobe posts numbers and the stock goes down. Only this time, it had already dropped even before the earnings release. At least that is a new pattern. Let’s explore what happened.
And my Best Buys for August, if you are interested in attractive opportunities:
Best Buys August 2026 | Buying quality while the market looks elsewhere

It is summertime, and it is hot outside. So are the markets. At least most of the days, unless there is a casual 8% drop in ASML and AMD, as happened on the 27th of July, or the casual 13% jump for AMD yesterday. That is why I chose a rollercoaster as the title image. Rollercoasters can be great fun or cause sheer terror depending on your personality. The same is true for investors. Some see volatility as their friend - you can buy great companies at a discount, while others freak out if one of their beloved holdings drops double digits in a single trading session.
Invest at your own risk; this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
Management’s summary
That’s how the management described the results:
Despite continued geopolitical and macroeconomic uncertainty during the second quarter, the underlying desire to travel remained resilient, and we are pleased with our results, which reflect the strength of our global platform and the disciplined execution of our teams.
We also increased the expected annual run-rate savings enabled by our Transformation Program, creating additional capacity to invest in our strategic priorities. We remain focused on what we can control– building better experiences for travelers, creating greater value for our partners, and strengthening our business for the long term.
Before going into the details: If you haven’t done so already, read my deep dive on Booking to learn all you need to know to evaluate the opportunities and risks of this company:
AI won’t kill Booking - it might make it stronger

Intro It’s that time of the year again, and my annual trip to Omaha and the Berkshire Hathaway annual meeting was due. I’ve been looking forward to this for months. In Omaha, I attended an investors’ meeting where I was also pitching an idea. Last year I chose Arista Networks, and boy, that was a home run. In the last year, the stock is +106%. I am certainly happy with the addition to my portfolio, and I hope you have joined me on this magnificent ride. You will find the deep dive here:
Income Statement
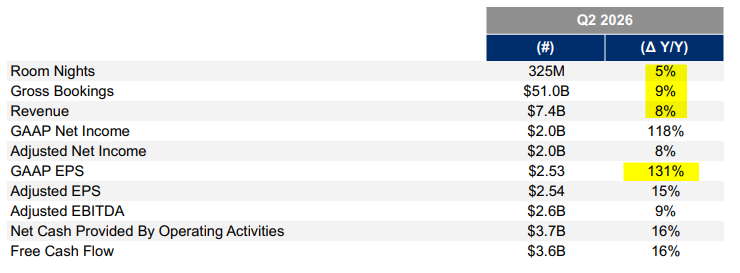
Room nights booked and Gross Bookings were up, and so was revenue compared to Q2 last year. The biggest jump, however, was in EPS (+131%)
The large jump was due to a one-time effect in Q2 last year. In Booking’s words: “Foreign currency transaction losses (gains) on the remeasurement of Euro-denominated debt”. I touched upon this in my deep dive: these one-time effects do not matter for a long-term investor. Especially if they are not impacting the cash flow, as is the case here.
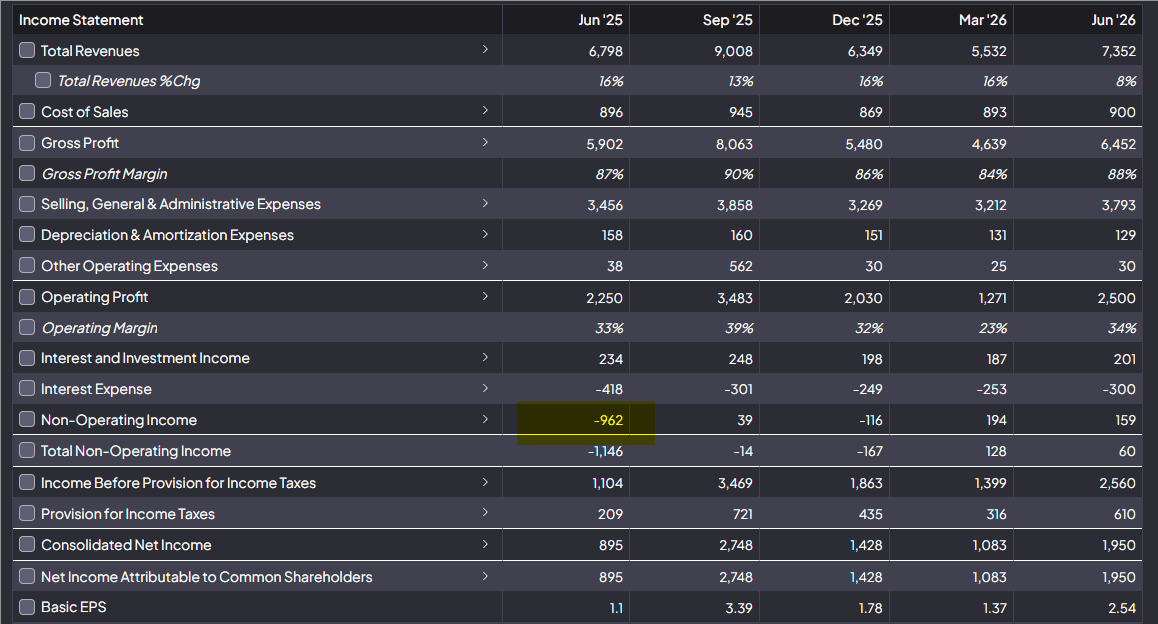
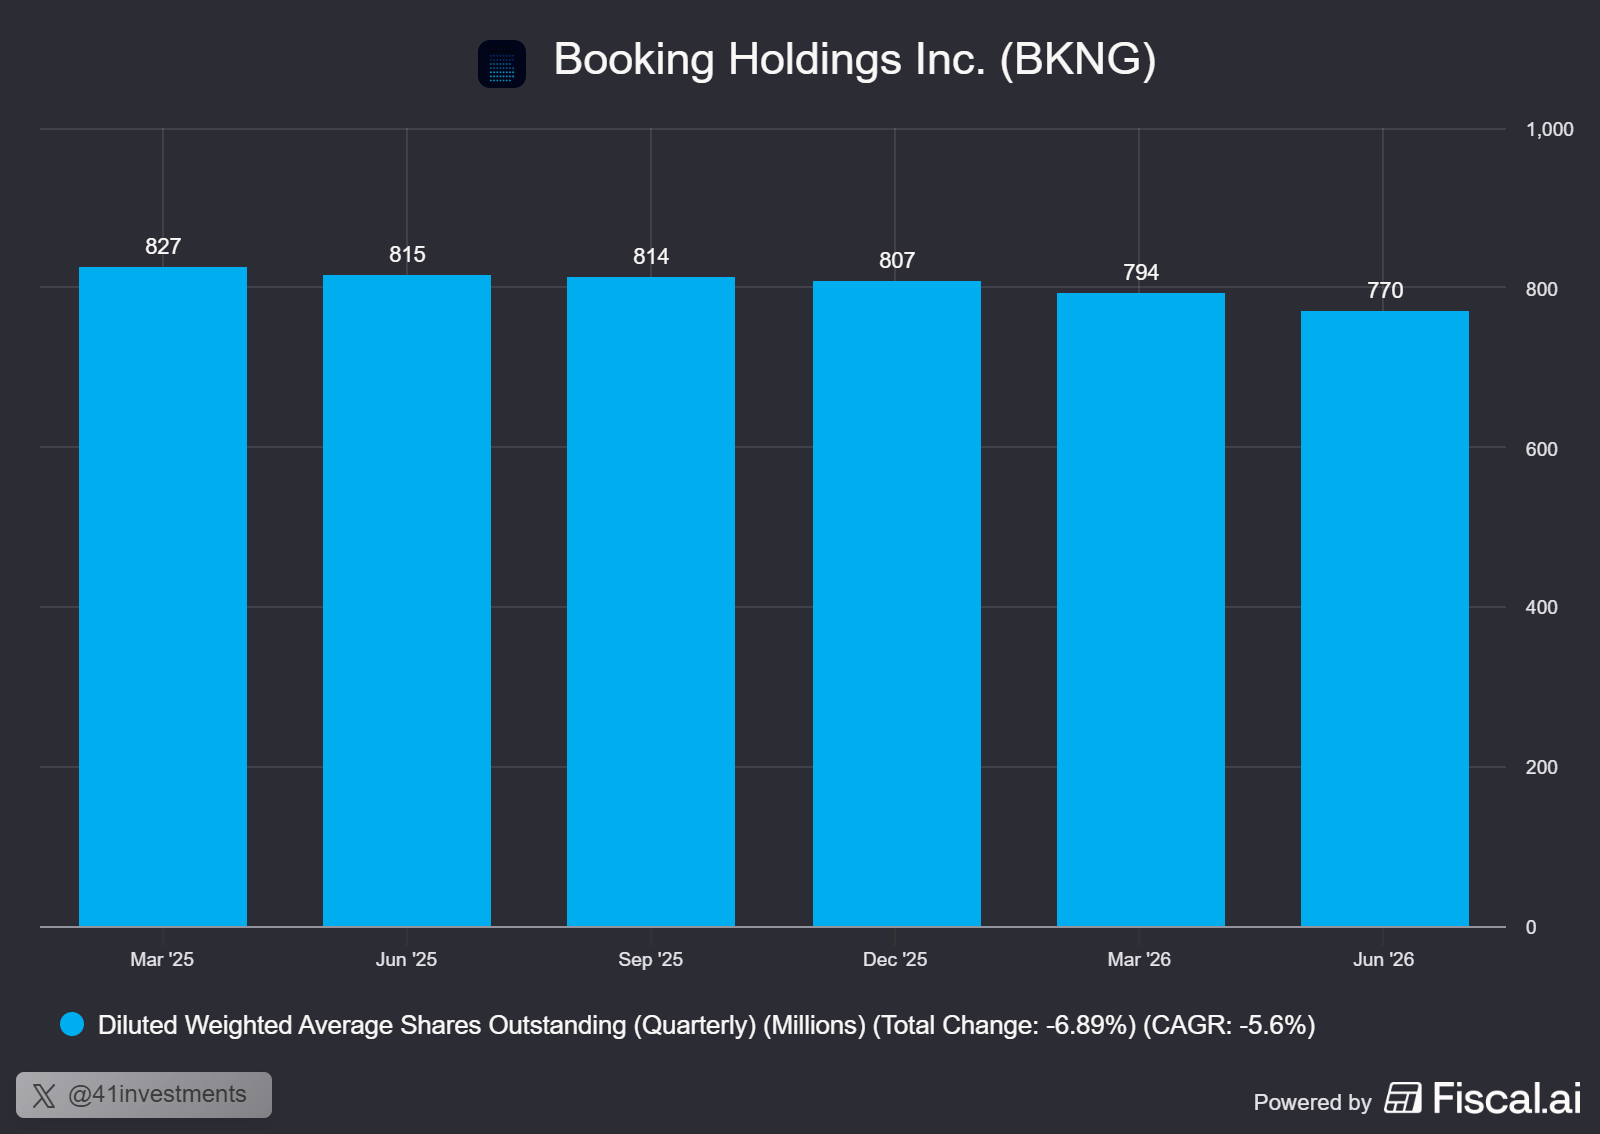
While the net income was +117, the EPS increased by 131% due to the continous buy backs. Booking reduced the number of outstanding shares by 7% since Q1/25 and by 3% alone last quarter. Thank you, management; my ownership of Booking keeps increasing without me having to do anything. As of the end of June, the remaining share buyback authorization was $14.5 billion, which is enough to buy back 9% of outstanding shares.
"Glenn Fogel was asked directly whether AI tools are sending bookers straight to hotels instead of through Booking. His answer wasn't a denial."
This is the end of the free section. If you want to
✅ Read the full earnings call breakdown — what Booking's management actually said about AI traffic, cost per merge request, and whether bookers are going direct to hotels
✅ Get my exact valuation: 14.7x FY28 P/E, 19x forward P/E, 17x EV/FCF — and whether that's still cheap enough to buy
✅ Get full access to every past deep dive, immediately — not just what I write going forward
Or if you
✅ have profited from previous picks (AMD, Arista Networks, Texas Pacific Land, and many more…)
✅ want to support the work behind articles like these
Then become a paid subscriber. 9€/month or 99€/year — less than one bad trade and a fraction of the gains.
To all existing paid subscribers: You rock! 🙏
