

Invest at your own risk; this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
In this short format, I want to present to you companies and stocks, which are currently valued at an attractive level. Writing a deep dive takes me many hours and with this format I can introduce you to interesting ideas as of today.
I will only recommend high-quality businesses and I am not interested in cheap, but mediocre companies. Always keep in mind, that the quality of the company is the first filter. If it does not possess a very good business model, I am not interested in the company, even if it is dirt cheap. With that being said, let’s start!
Both companies presented today are among the largest holdings in my portfolio and I have added to both in the last weeks.
Alphabet
Investing doesn’t have to be hard. I bet all of you know and have used Google for the last 15+ years. Compared to that, most people kept searching for the next star instead of just buying Alphabet. Consider me one of these investors, before I finally saw the light and bought Alphabet shares in 2018 as a long-term holding and not just as a trading position.
To google has become a synonym for searching for information online. Now add YouTube, Google Maps, etc and you will find my apps which you can’t imagine living without. That’s a great fundamental for a company.
Where it gets interesting is the fact, that the stock of Alphabet, the holding company of Google has not been doing that well in comparison with the S&P500 in the last year.
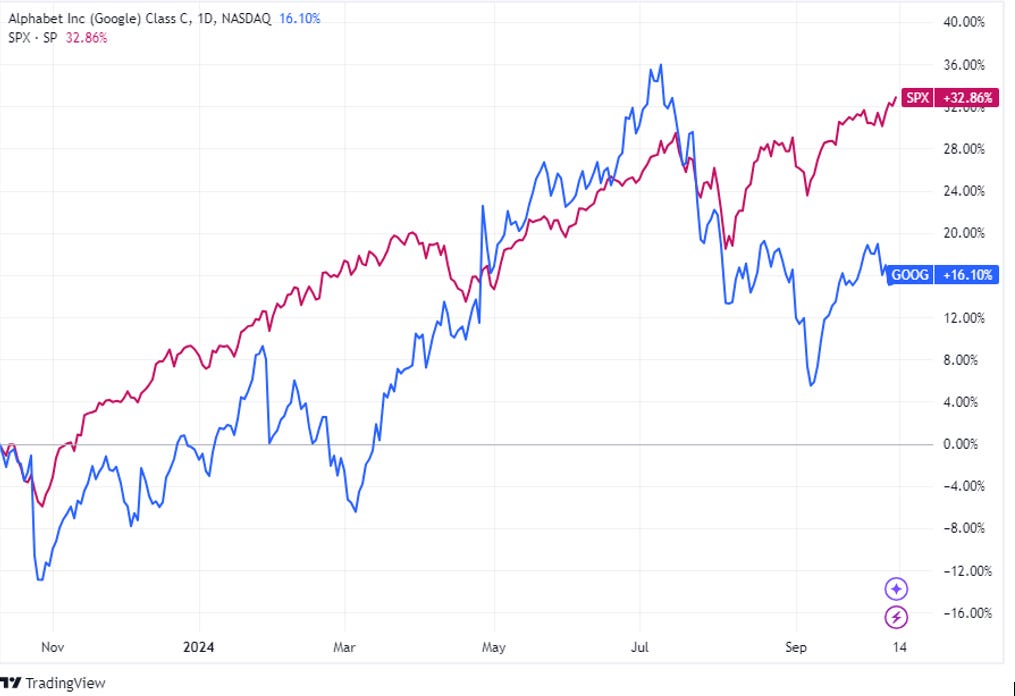
The US Justice Department is pondering a breakup of Alphabet and this has put pressure on the stock. I would not worry too much, since a) such a breakup would take many years and b) the individual parts of Google might be worth more than the sum.
Alphabet’s self-driving subsidiary Waymo is doing extraordinarily well and also Google Cloud started to bring in a large surplus.

Considering the strength of the business and the moat of the company the valuation is very cheap. Alphabet is currently trading at an EV/net income of 22 and forward P/E of just 19. I am aware that an EV/(FCF-SBC) of 50 Alphabet does not look cheap. The current high spending on capex (most of it is AI-related) has a huge toll on the FCF. I believe, however, that this spending will increase the moat of Alphabet even further.
On a forward P/E level Alphabet is fairly cheap.

I believe in a couple of months a lot of investors will look back and will be surprised, that they missed buying Alphabet at such a great price.

ASML
If you want to read the full article and learn about the management, the composition of the segments, takeovers, risks, fundamental analysis, and a conclusion please subscribe and support my work. To all existing subscribers: Thank you for your support and enjoy the rest of the article!
Staying with the letter A, ASML is yet another company which is marvelous. Finally, a high-tech company from Europe, to be more precise the Netherlands. Without ASML you would not have the modern chips in your smartphone, computer or any top-notch GPU. ASML is one of these companies that I followed for years before finally buying shares in the second half of 2022.
This video gives a good overview of ASML.
ASML has a monopoly on EUV technology and is the only company in the world that can produce 5 nanometers (nm) and 3 nm process nodes. Even if a Chinese company would get its hands on all the building plans for this machine, the process of manufacturing and sourcing the individual parts is so complex (maybe even impossible), that they are not able to just build one of their own.
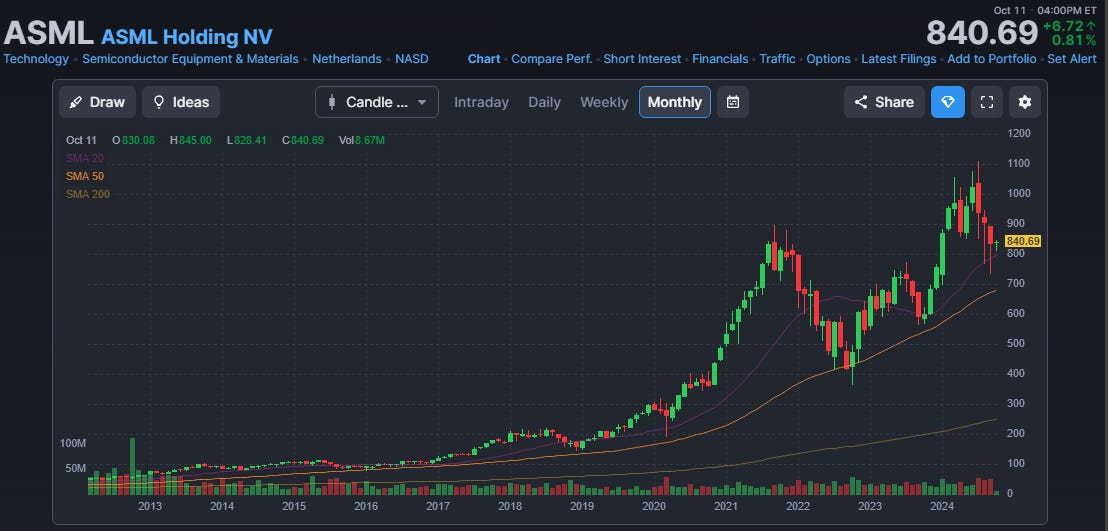
The newest high-NA EUV machines cost around $380m per piece and the foundries can’t wait to get their hand on one of these. ASML has a very long runway and it is the most important company many people have never heard of. Luckily for us, we can buy shares in this fantastic company. Even better yet, the shares are at an attractive level at the moment.
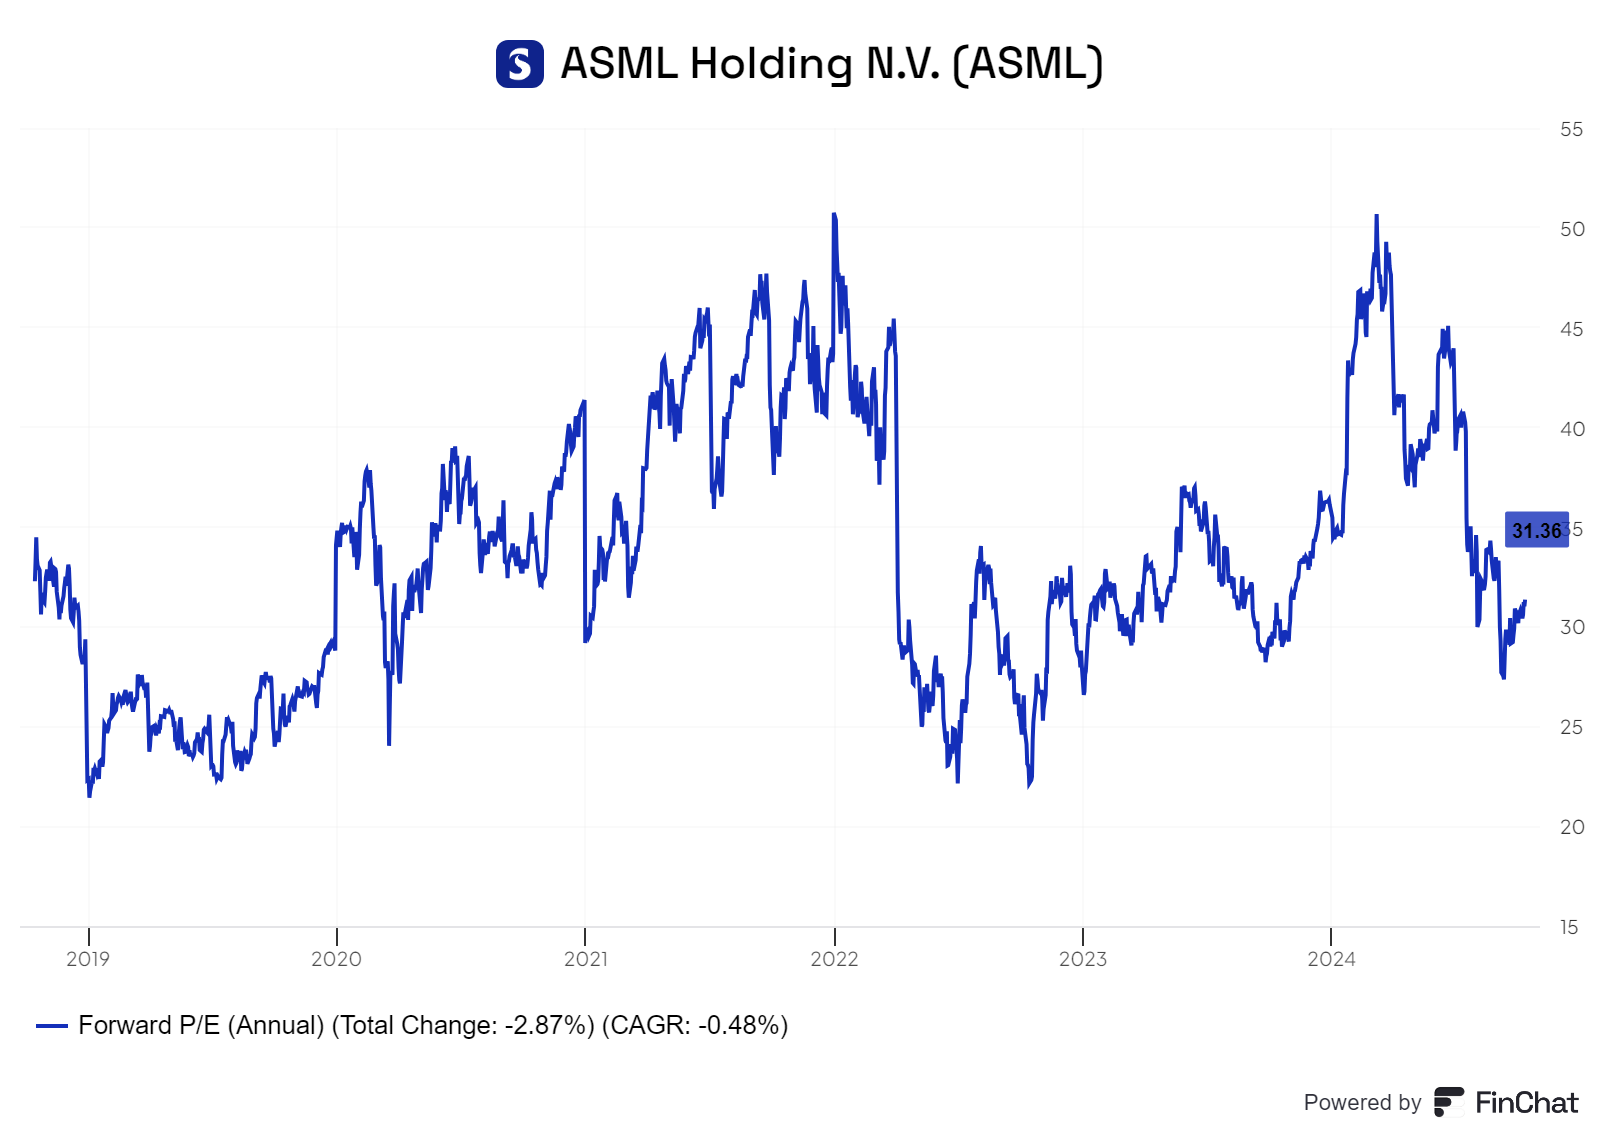
With a forecasted EV/Net income of just 21 in 2 years and an EV/FCF of 43 in 2 years I am a happy buyer at these levels. Companies like ASML rarely come cheap, but there are moments of relative undervaluation. If you have missed those in the past, now is your chance to buy some ASML.
Cleaning up
This is not your typical buy, but I am using the chance of the record highs in the broad market to clean up and streamline my portfolio. As part of this, I am selling holdings, where the position is either too small for me to invest significant time in tracking it or it is a position which I don’t intend to hold for the long run. Maybe this applies to you as well.
That’s it for today. Let me know if you own any of these companies and which stocks you are looking into right now.
If you haven’t done so already, please follow me on twitter/x and reshare this post so it can reach more people.
Invest at your own risk, this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
41