

It is summertime, and it is hot outside. So are the markets. At least most of the days, unless there is a casual 8% drop in ASML and AMD, as happened on the 27th of July, or the casual 13% jump for AMD yesterday. That is why I chose a rollercoaster as the title image. Rollercoasters can be great fun or cause sheer terror depending on your personality. The same is true for investors. Some see volatility as their friend - you can buy great companies at a discount, while others freak out if one of their beloved holdings drops double digits in a single trading session.
The Iran war is still going on, despite all the hopes for a fast resolution, and the world is as complicated as ever before. This shall not stop us from searching for the best investments and the satisfying feeling when the markets prove you right.
The YTD performance feels like a rollercoaster, and I was surprised to see that some of the largest stocks such as Nvidia, Alphabet, Berkshire, and Amazon all barely moved since the beginning of the year. The S&P500 is +8% YTD, and some stocks like AMD or Micron shot the lights out this year.
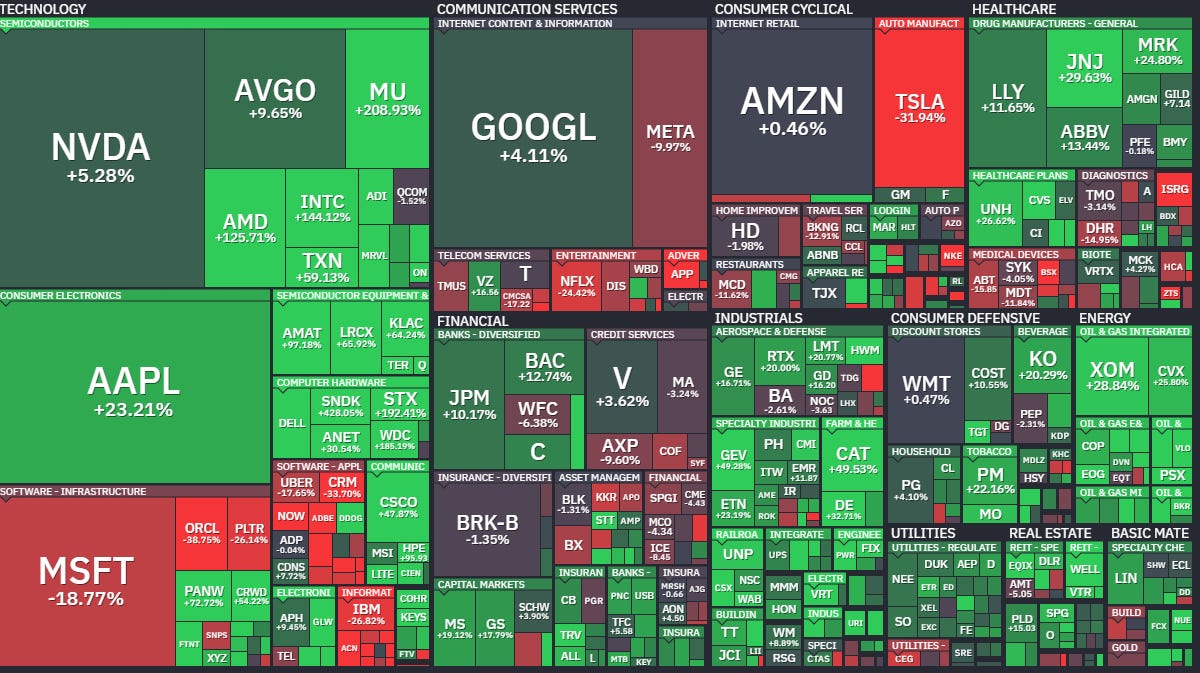
Talking about AMD: I hope you read my article in late 2024 and took action. You will find it here:

Invest at your own risk; this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
AI is still the fashion of the day, and I wrote two pieces that summarize the current state of AI and showcase some notable developments. Make sure to read both to get a better understanding of the rapid-paced world that we live in today:
AI Observations – June 2026 (Part 1): The Boom Continues

This is a follow-up to my AI Eats the World post from November. Roughly half a year later, AI is still the dominant topic of the day, and the new models from Anthropic and OpenAI are another major jump. This is part 1, covering the newest slide deck from Ben Evans and some more interesting observations. Part 2 will move beyond the data, and I will discu…
AI observations – July 2026: The biggest AI trends you should know

The current AI boom and AI buildout are both deeply fascinating and causing headaches at the same time. In this article, I will explain some trends that I am seeing and topics that you should be aware of. Among these are rising inference costs, exploding energy costs, Chinese AI models, and geopolitical restrictions, which have a major impact on the world.
Best Buys today
I will just link to my deep dives for Adobe (-31% YTD) and Salesforce (-34% YTD) and will not reiterate my thesis, since I did so in the last Best Buys article from February. The only thing that changed: Both stocks got even cheaper.


You will find the Best Buys article for February here:

Booking
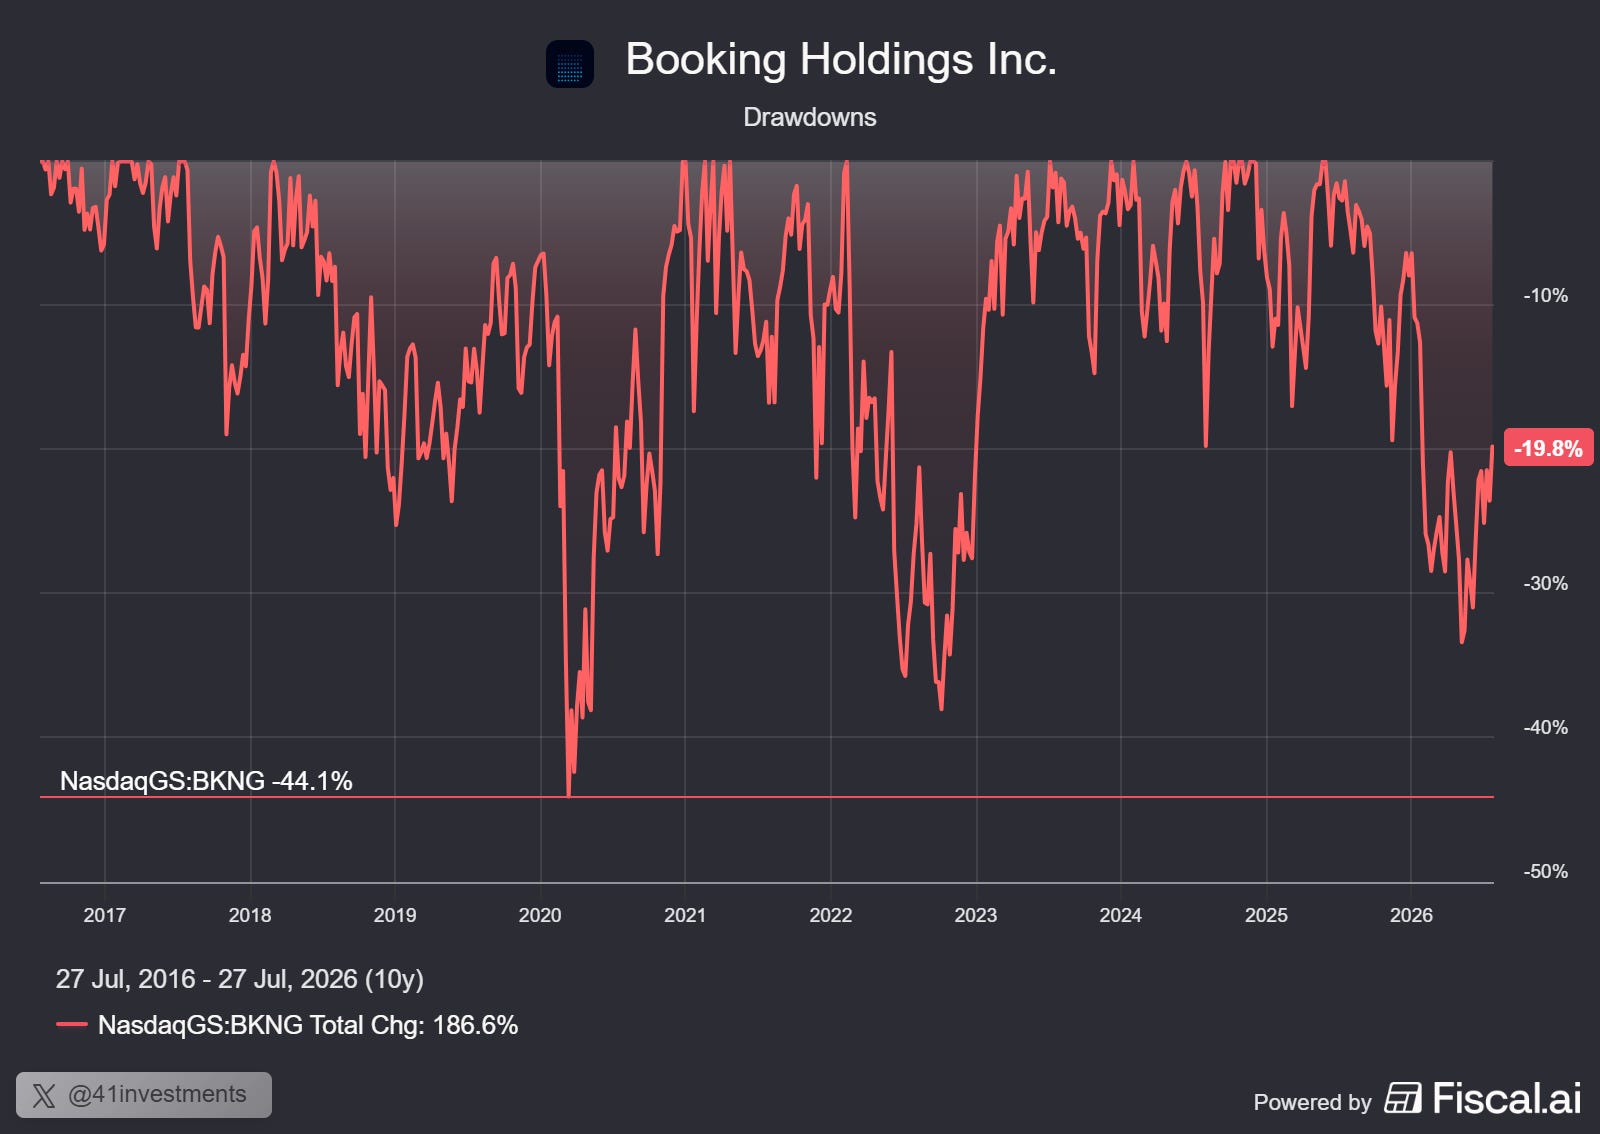
Booking is the best company in the travel sector. A sector that keeps growing year in, year out, and at the same time the move from traditional offline travel agencies to online travel agencies is still happening. Both trends help Booking grow revenue.
The Iran war was one of the reasons for the sell of, the other one (what else could it have been): AI. The fear of AI is overblown IMHO, and I believe AI will instead help Booking to ship new product developments fast and cheaper (less development costs) and significantly improve customer service.
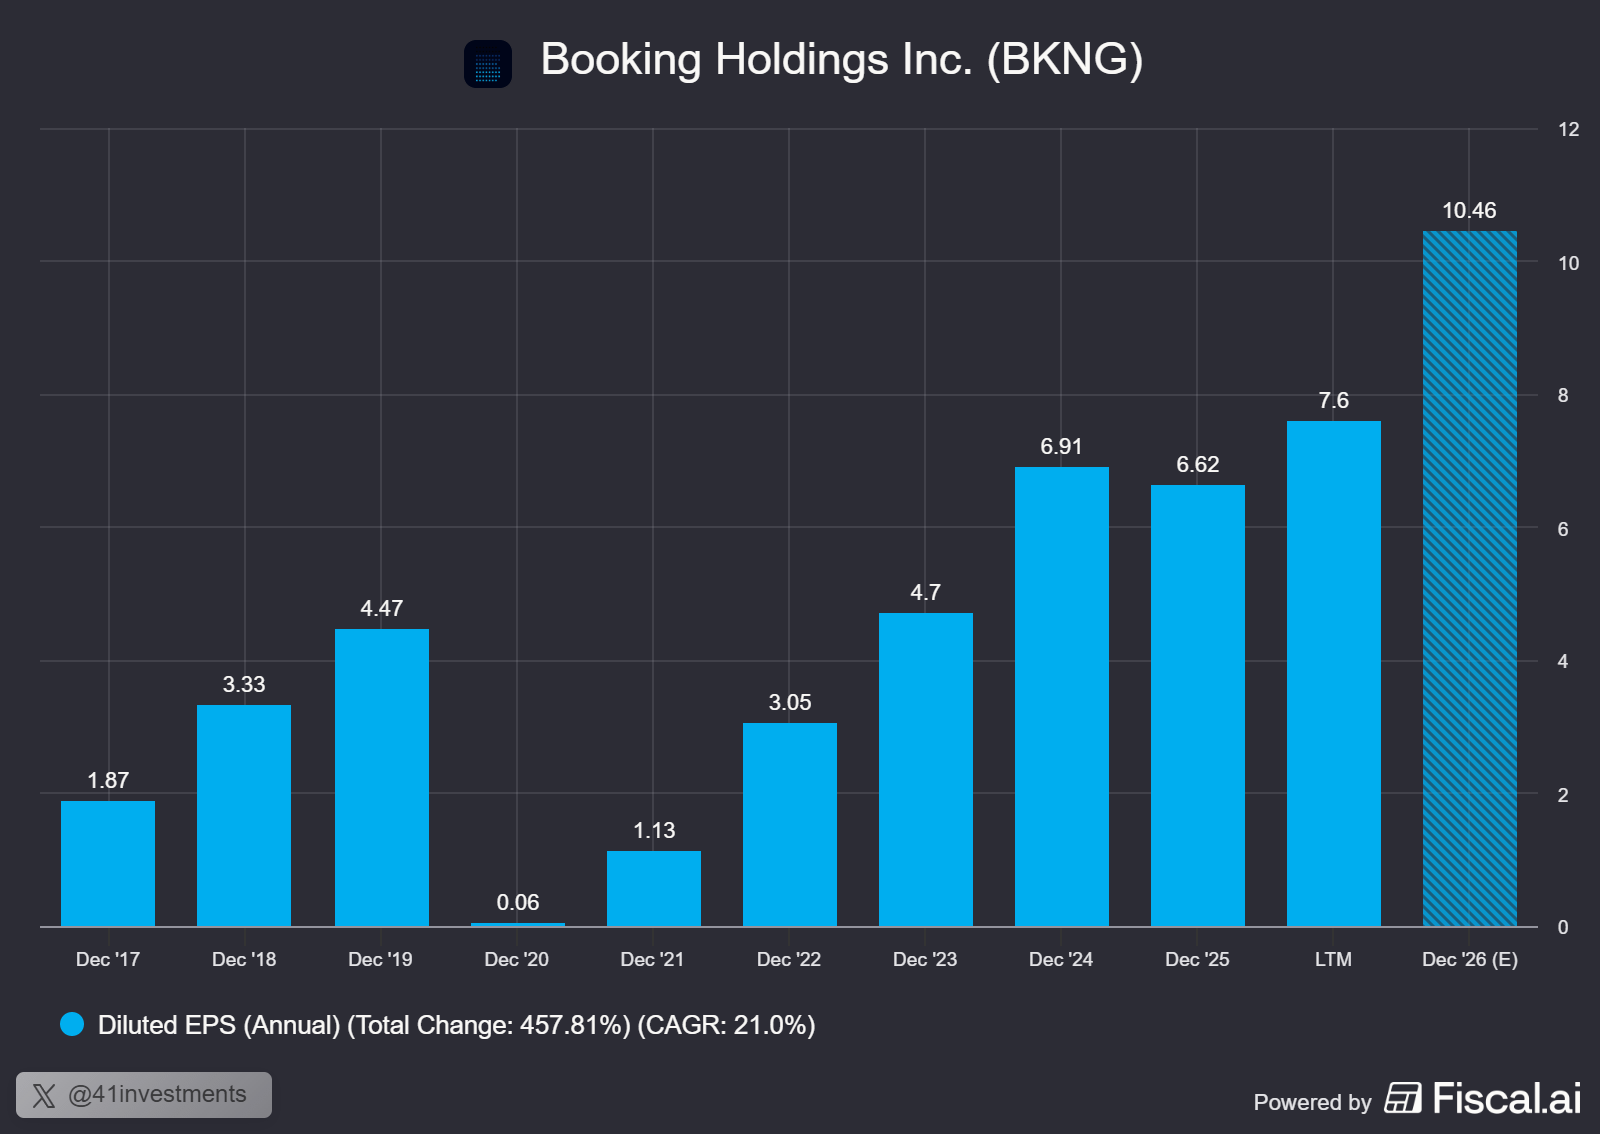
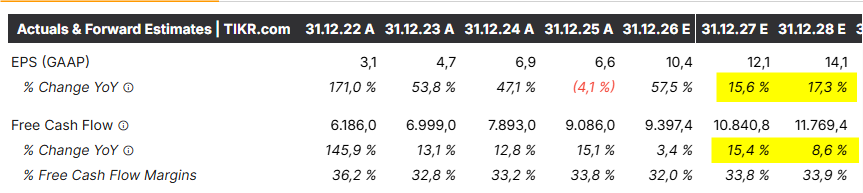
Fiscal year 2025 saw some special effects which had a negative impact on the net income. One was the FX adjustment for EUR-dominated debt, which is just an accounting topic and does not reflect anything meaningful for Booking, since Booking does the majority of the business in Europe. The other one was a goodwill impairment on KAYAK, its meta search engine for flights. This one is also more of an accounting issue and did not affect the cash flow. You can see how much higher the expected EPS are for this fiscal year (+38%).
Due to these two factors, Booking looks kind of expensive based on the trailing earnings per share, but the free cash flow tells the true story: Booking is very attractive at this level.
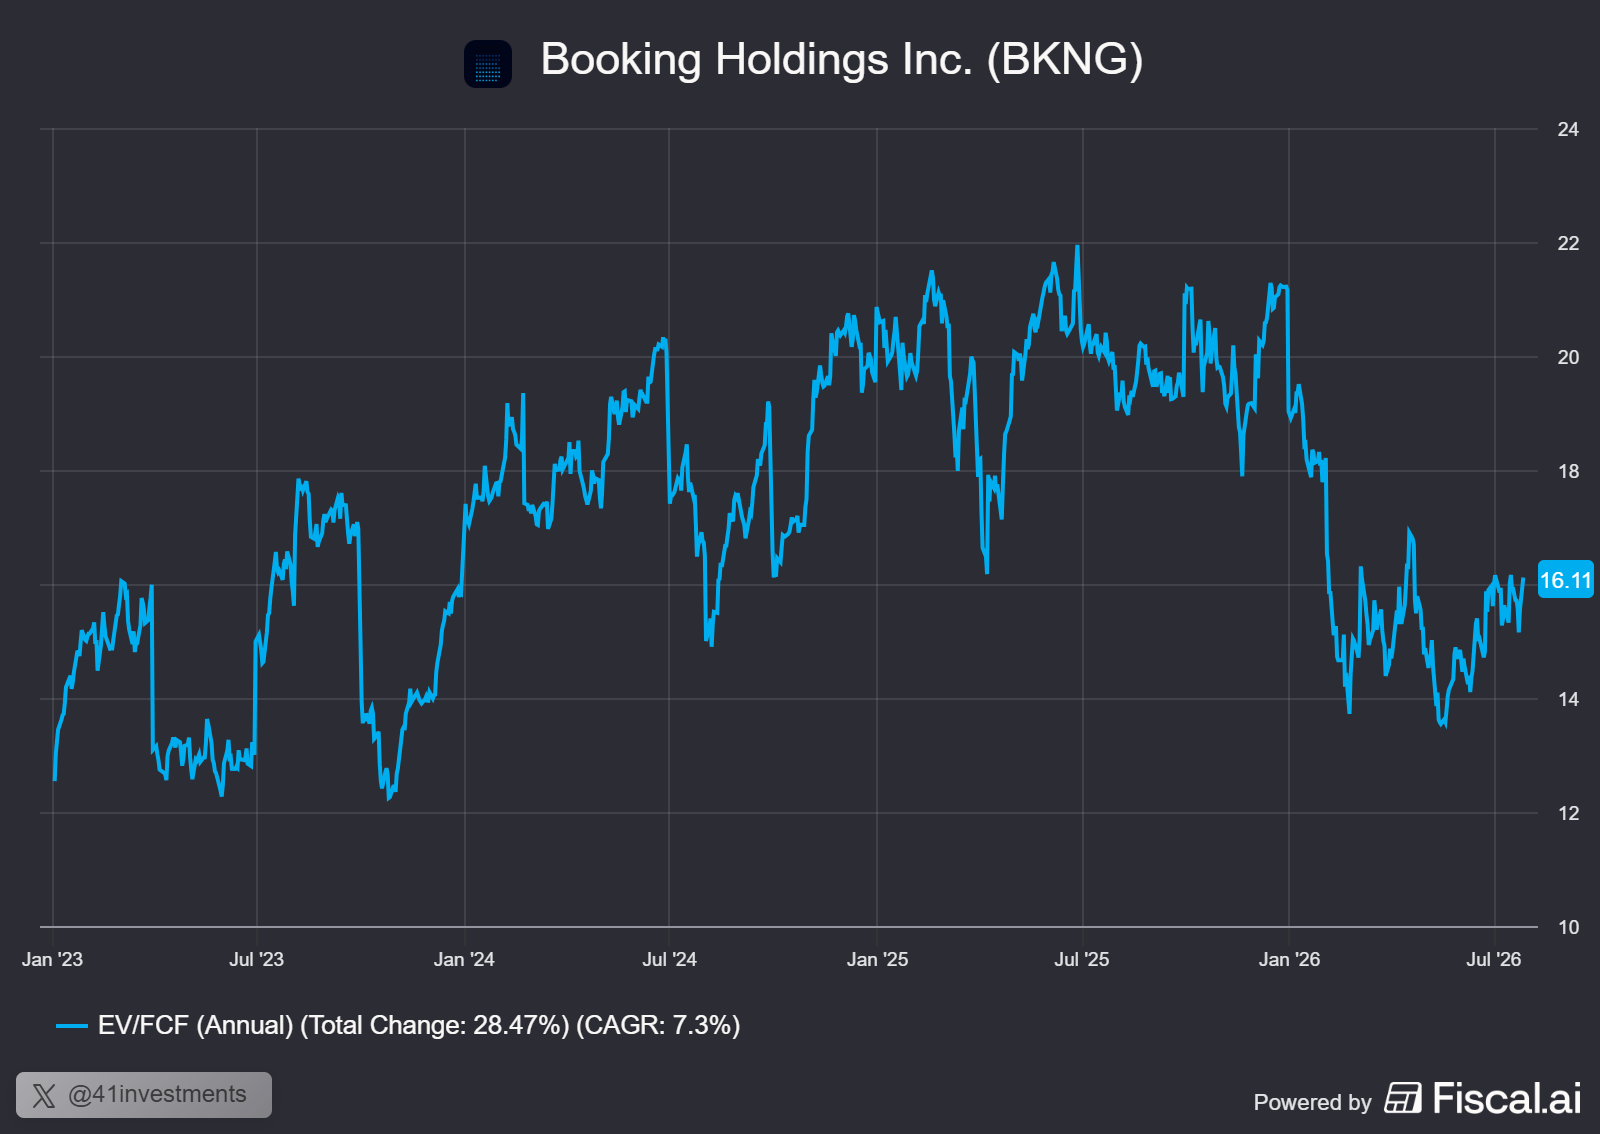
If Booking just gets back to its historical EV/FCF ratio of 21 before Covid, you are looking at a nice +30%.
The growth rates for the next two years are very attractive as well.
You will find my deep dive on Booking here, and you will learn everything you need to know about the company and the opportunity here:
AI won’t kill Booking - it might make it stronger

Intro It’s that time of the year again, and my annual trip to Omaha and the Berkshire Hathaway annual meeting was due. I’ve been looking forward to this for months. In Omaha, I attended an investors’ meeting where I was also pitching an idea. Last year I chose Arista Networks, and boy, that was a home run. In the last year, the stock is +106%. I am certainly happy with the addition to my portfolio, and I hope you have joined me on this magnificent ride. You will find the deep dive here:
META
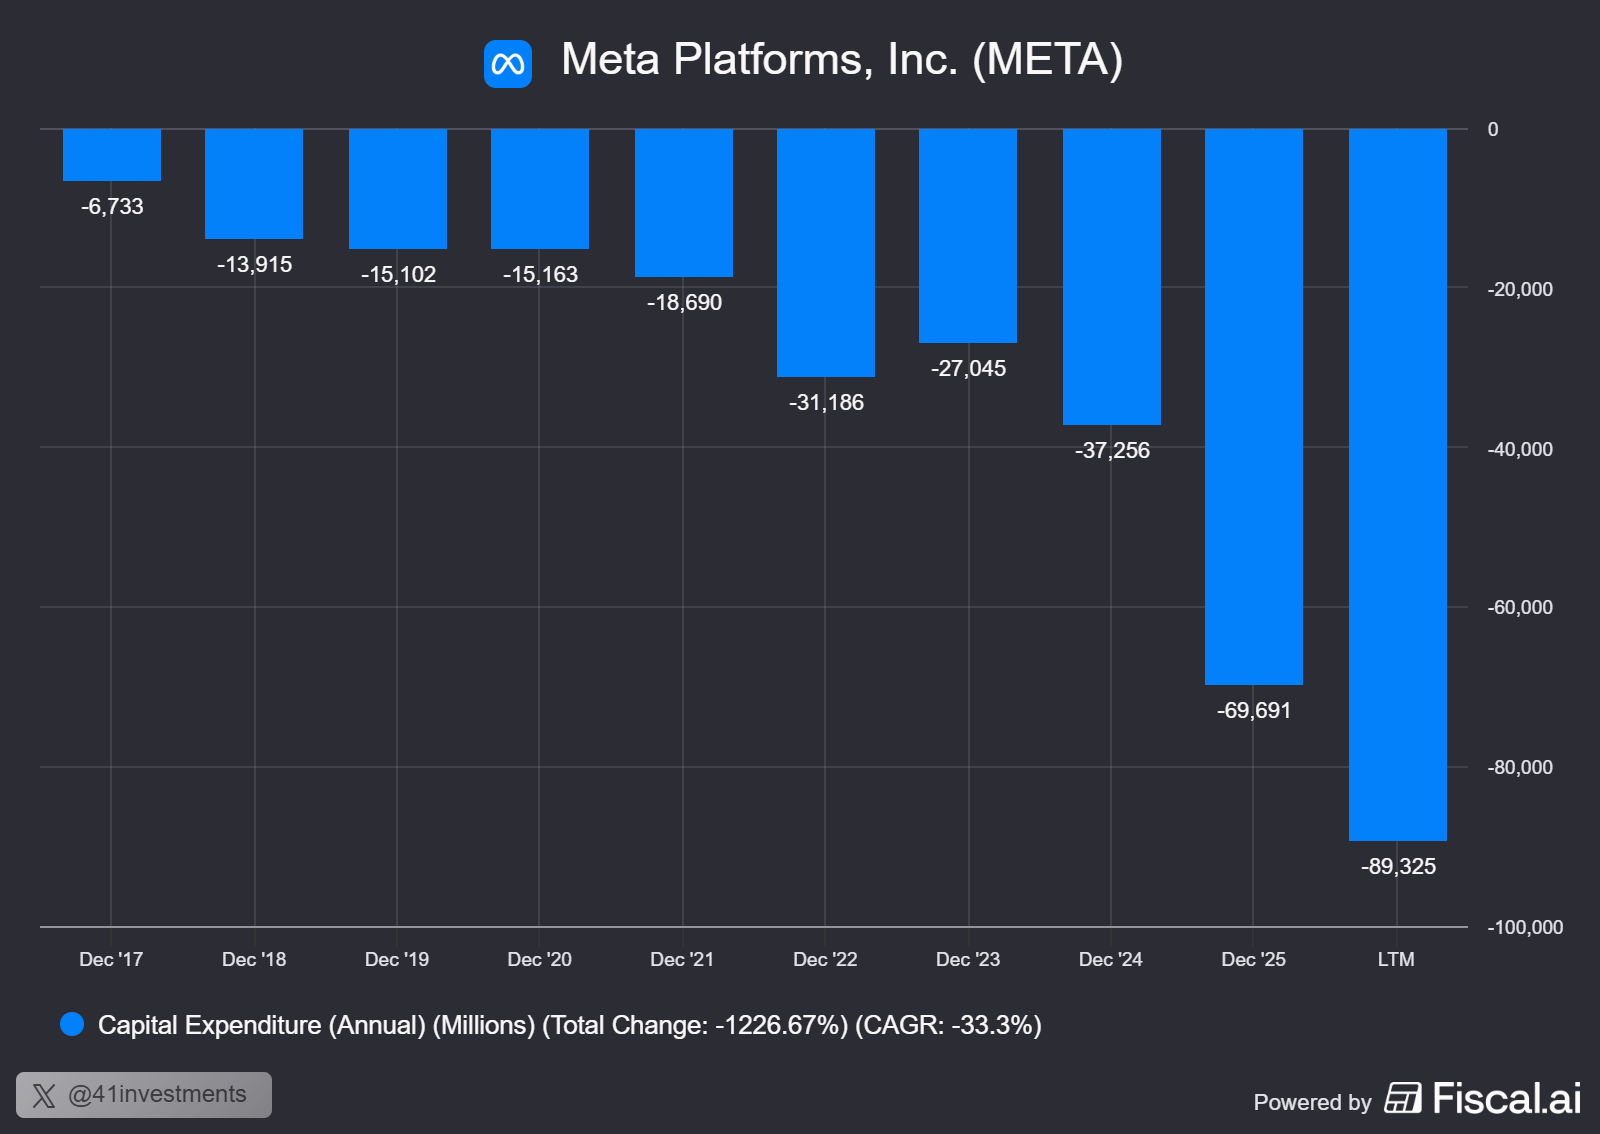
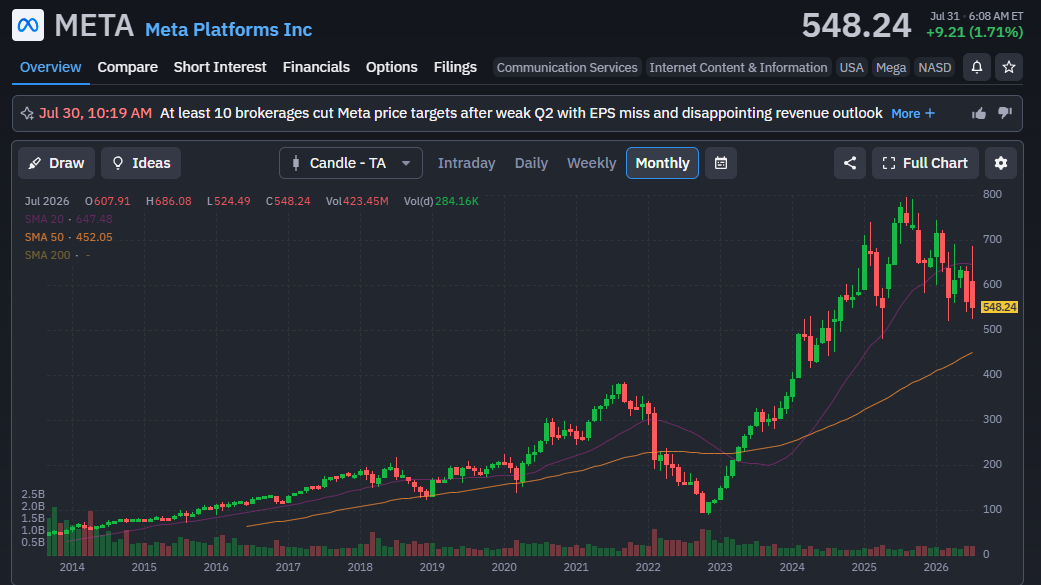
When I started working on this article, META had not yet released the Q2 numbers. And guess what: The growth is still impressive, and META got even cheaper. The stock dropped 10% due to the increased capital expenditures.
META has everything that makes for a great long-term investment. A fantastic business, faced with short-term issues. First and foremost, META (formerly Facebook) has a fantastic business.
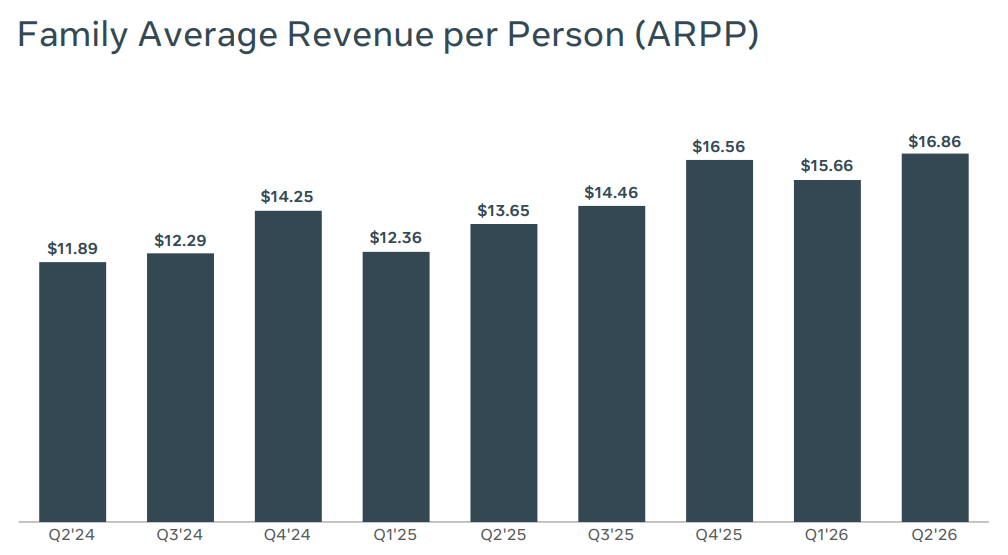
While META’s revenue per person is not crazy high, the fact that it is averaged among so many people makes for a large absolute number.
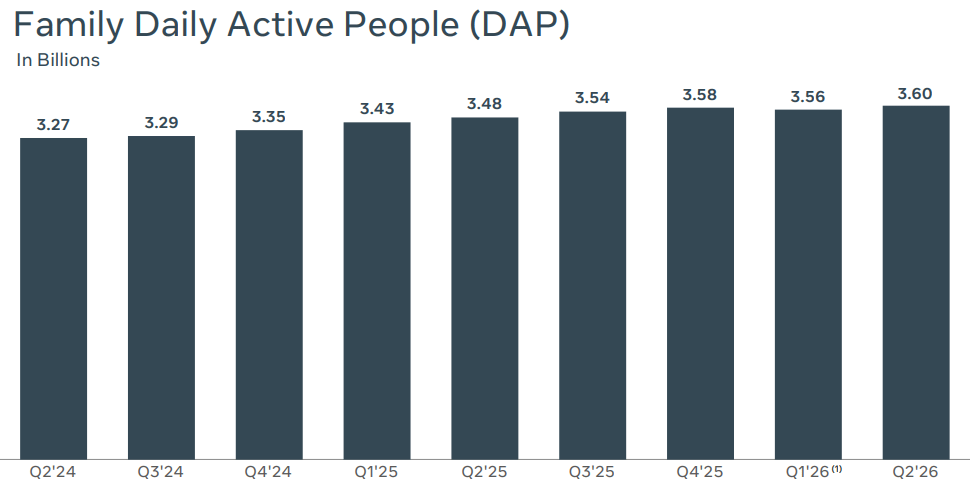
3.6 billion people are daily active users of one of the main products. The best-known ones are Facebook, Instagram, and WhatsApp. The numbers just keep going up, and the slight decrease in Q1 was due to internet outages in Iran and WhatsApp restrictions in Russia.
CEO Mark Zuckerberg is not afraid to make big bets since he does not want to miss the next platform change. The last one from desktop to mobile has been mastered by META, also through the fantastic acquisitions of Instagram and WhatsApp, two of their main drivers today.
META sunk a gigantic sum of $88 billion in its Reality Labs VR division and is now pivoting into wearables, since VR does not seem to be the next big thing. You can now argue two ways:
How on earth can a company set so much money on fire? or
This is amazing: META is not afraid to make large bets and can easily afford to do so.
I lean slightly towards the latter. Like most of the other Magnificent 7, META is currently investing heavily in AI, and the large capital expenditures are nothing short of breathtaking. While the outcomes are entirely open, META controls a large share of the crucial customer access. Distribution will be key.
In terms of numbers, both revenue (blue bars) and earnings per share growth have been nothing short of sensational.
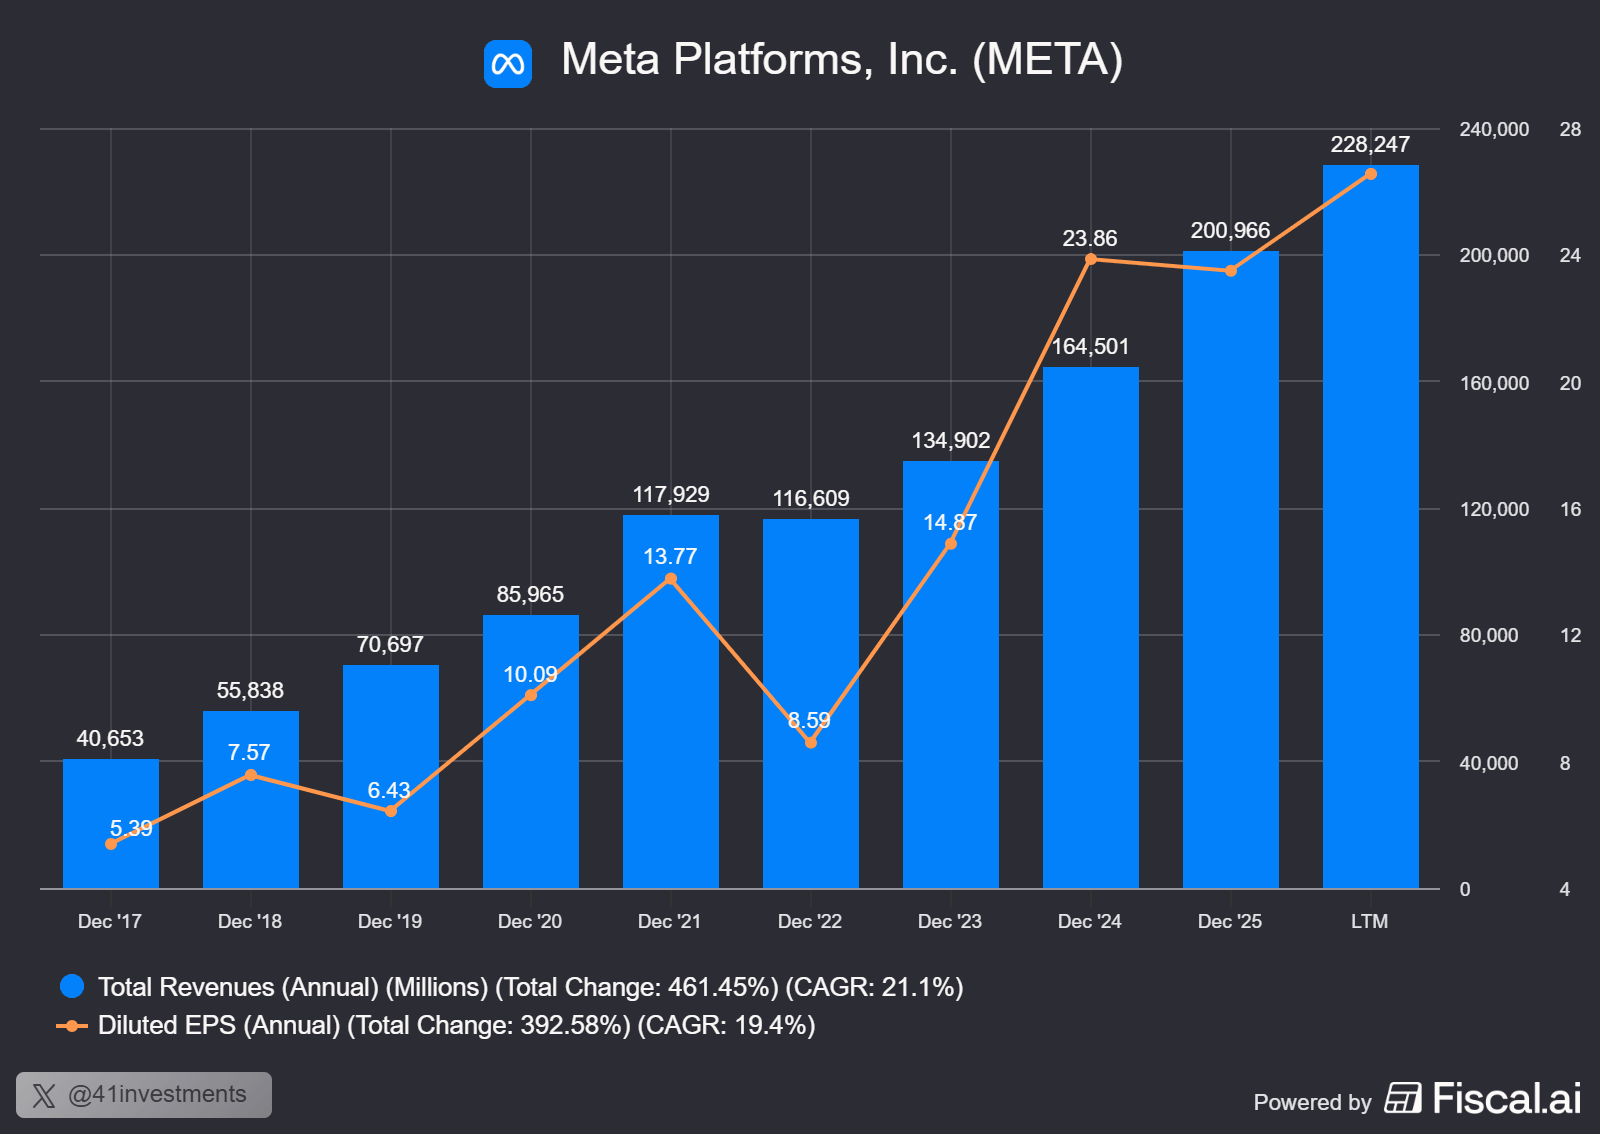
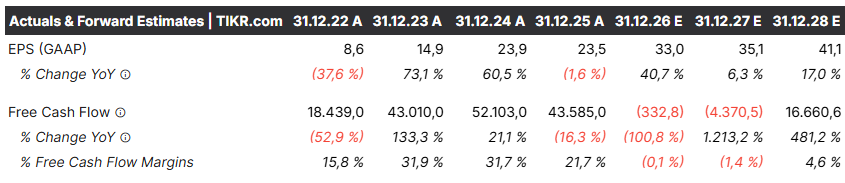
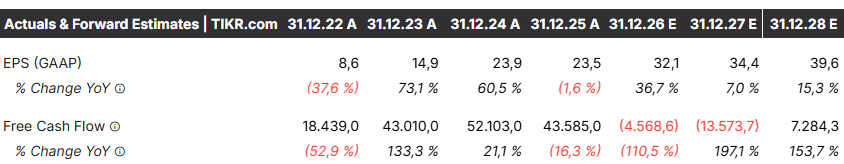
EPS growth is expected to continue to grow, but the Free Cash Flow is currently severely impacted by the large AI investments. We will see if it rebounds anytime soon.
These were the forward estimates before the release of the Q2 numbers.
These are the updated ones. The market does not believe the massive increase in Capex will lead to a proportionate increase in earnings.
If you want to invest in META, make sure to be comfortable with short-term pain. The capital expenditures must first prove to be value-generating and not just sunk costs on all those data centers.
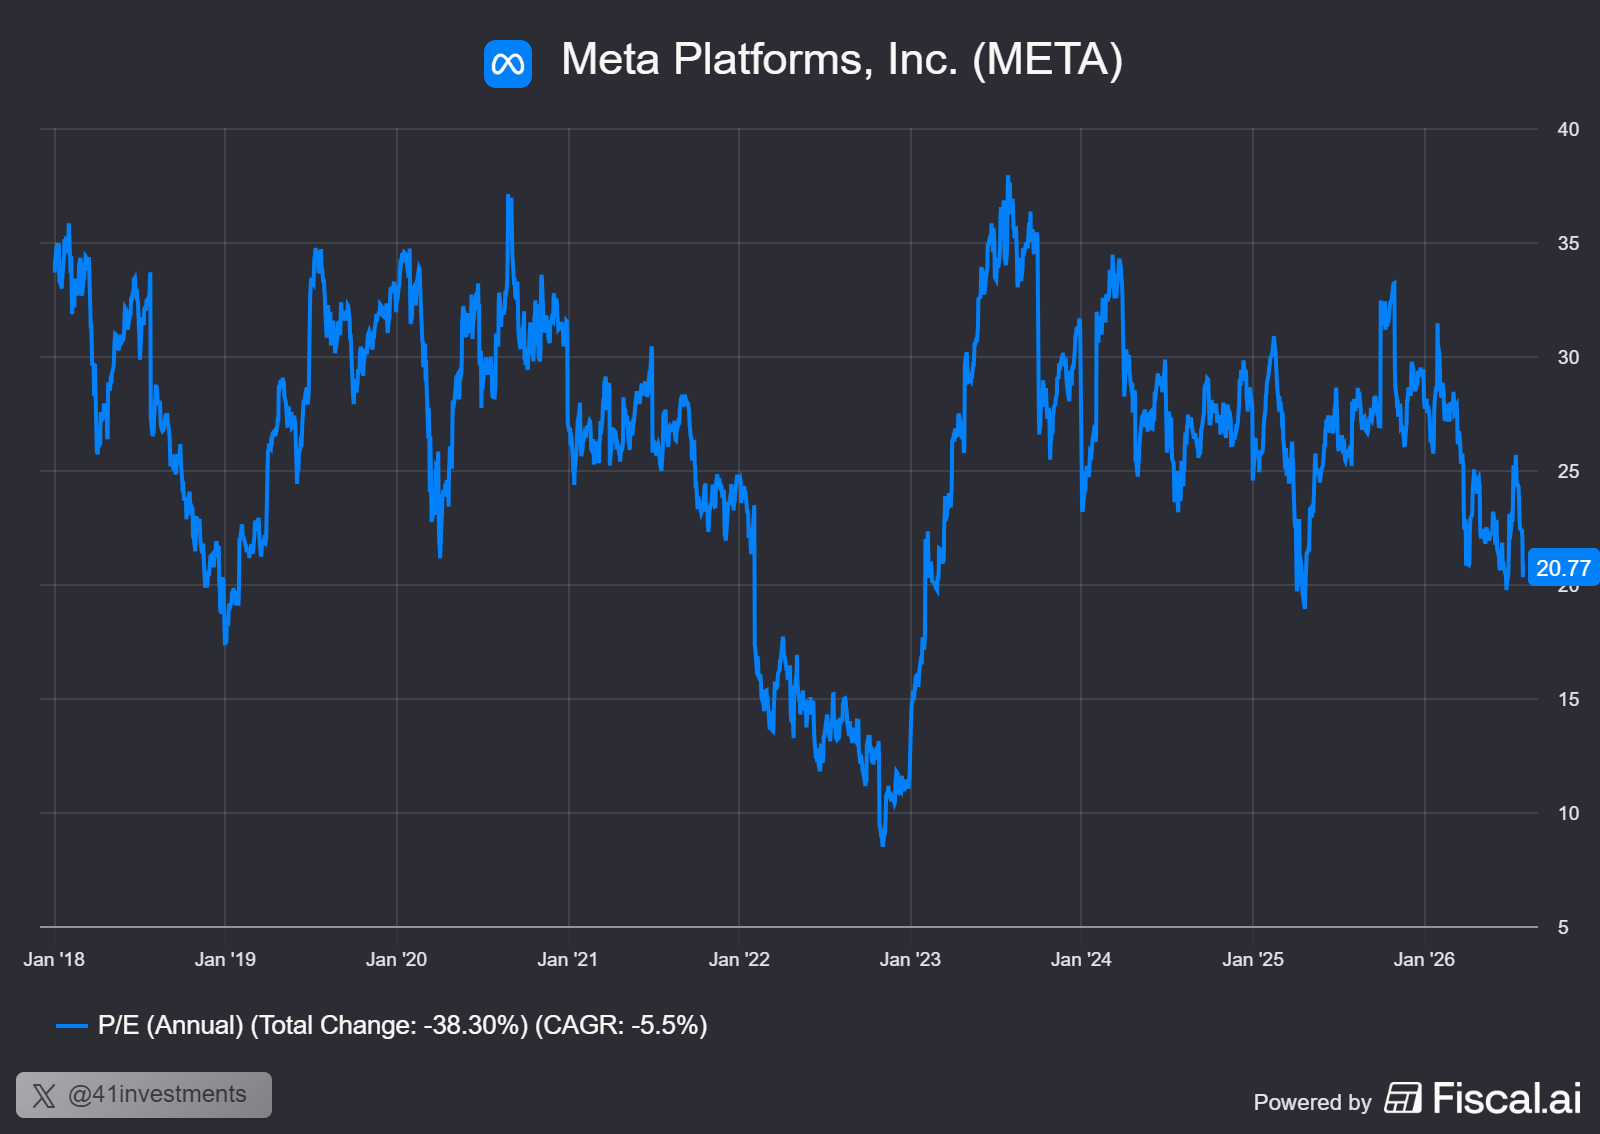
META’s P/E ratio is at the lower range of recent years (ignoring the insane sell-off in 2022)
The P/FCF ratio is currently high due to the enormous AI investments, but the P/OCF is quite low.
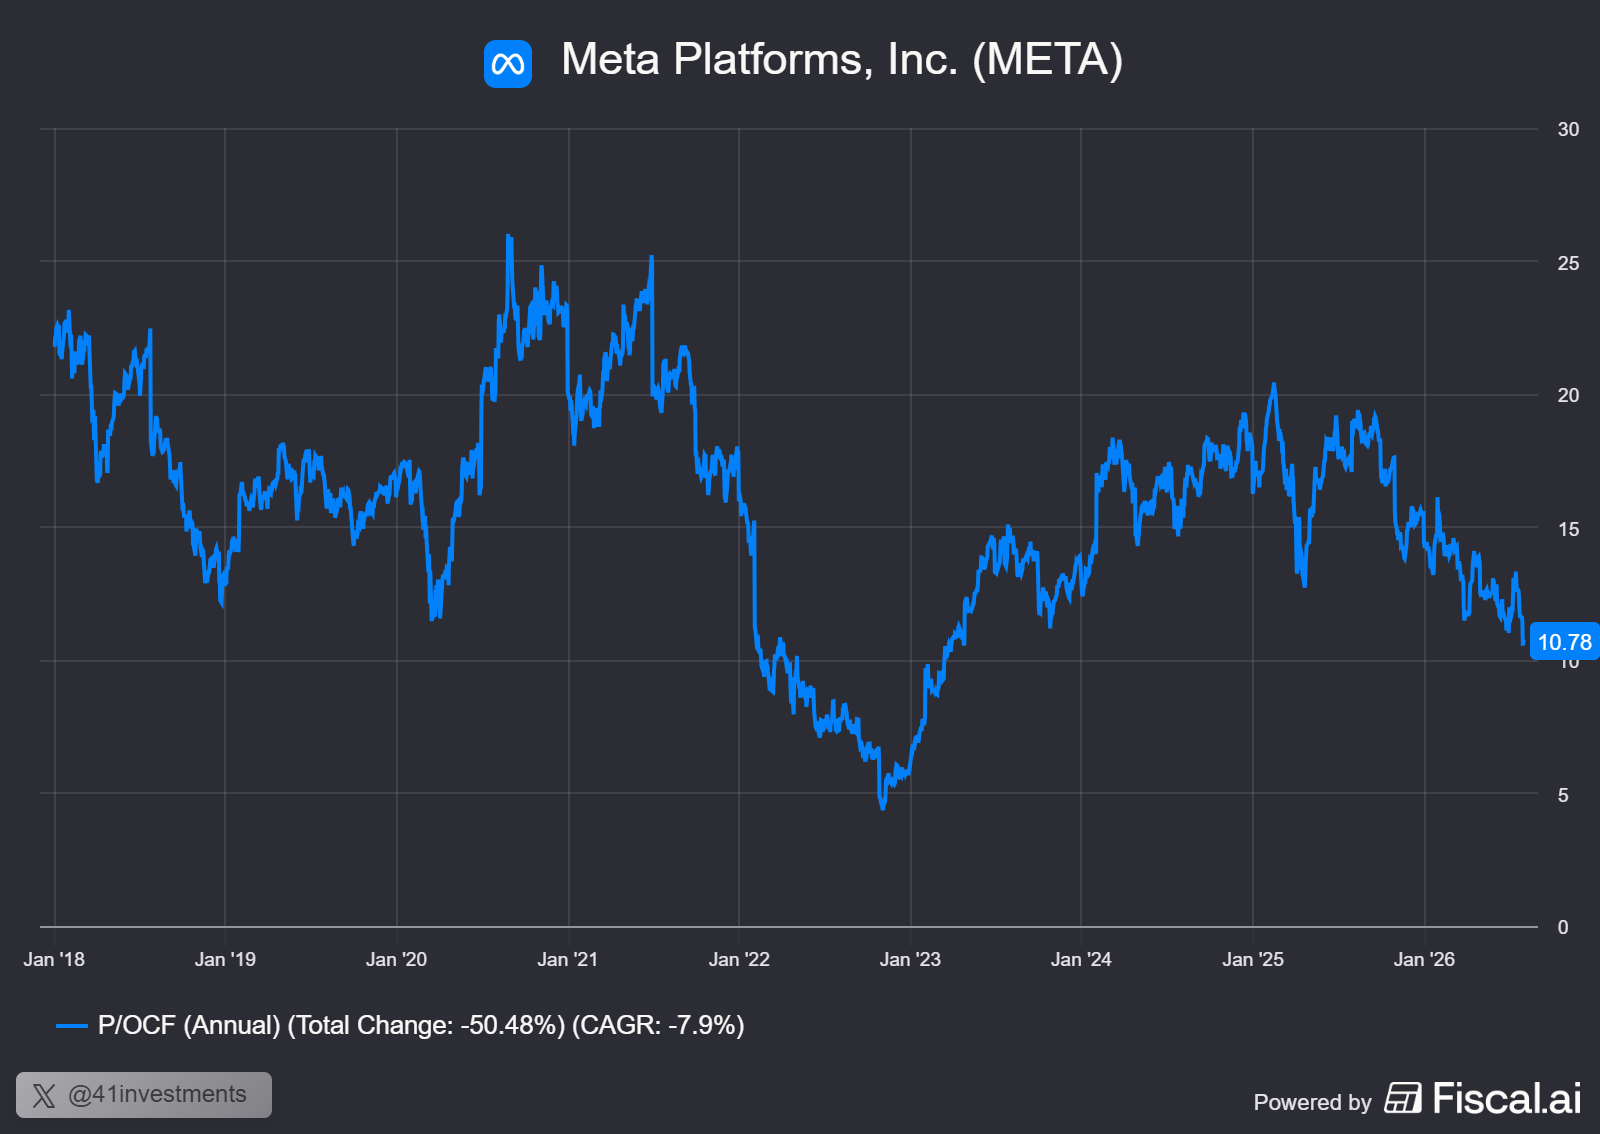
I believe META will be around for a long time, and we are looking at a great entry point. For the dividend guys out there. META is even paying a tiny dividend at 0.3%.
Microsoft
Timing is everything. I told friends and family in mid-July that I bought Microsoft. The reasoning is quite simple: Microsoft is a fantastic company that dominates distribution. Remember, distribution is everything.
While its own GenAI solution, Copilot, is far inferior to the newest Claude or ChatGPT versions, it is so well integrated through the whole Office365 suite. Many companies are not allowed to use Claude or Chinese models due to data protection rules, but Microsoft is already part of the enterprise and seen as a more trustworthy party.
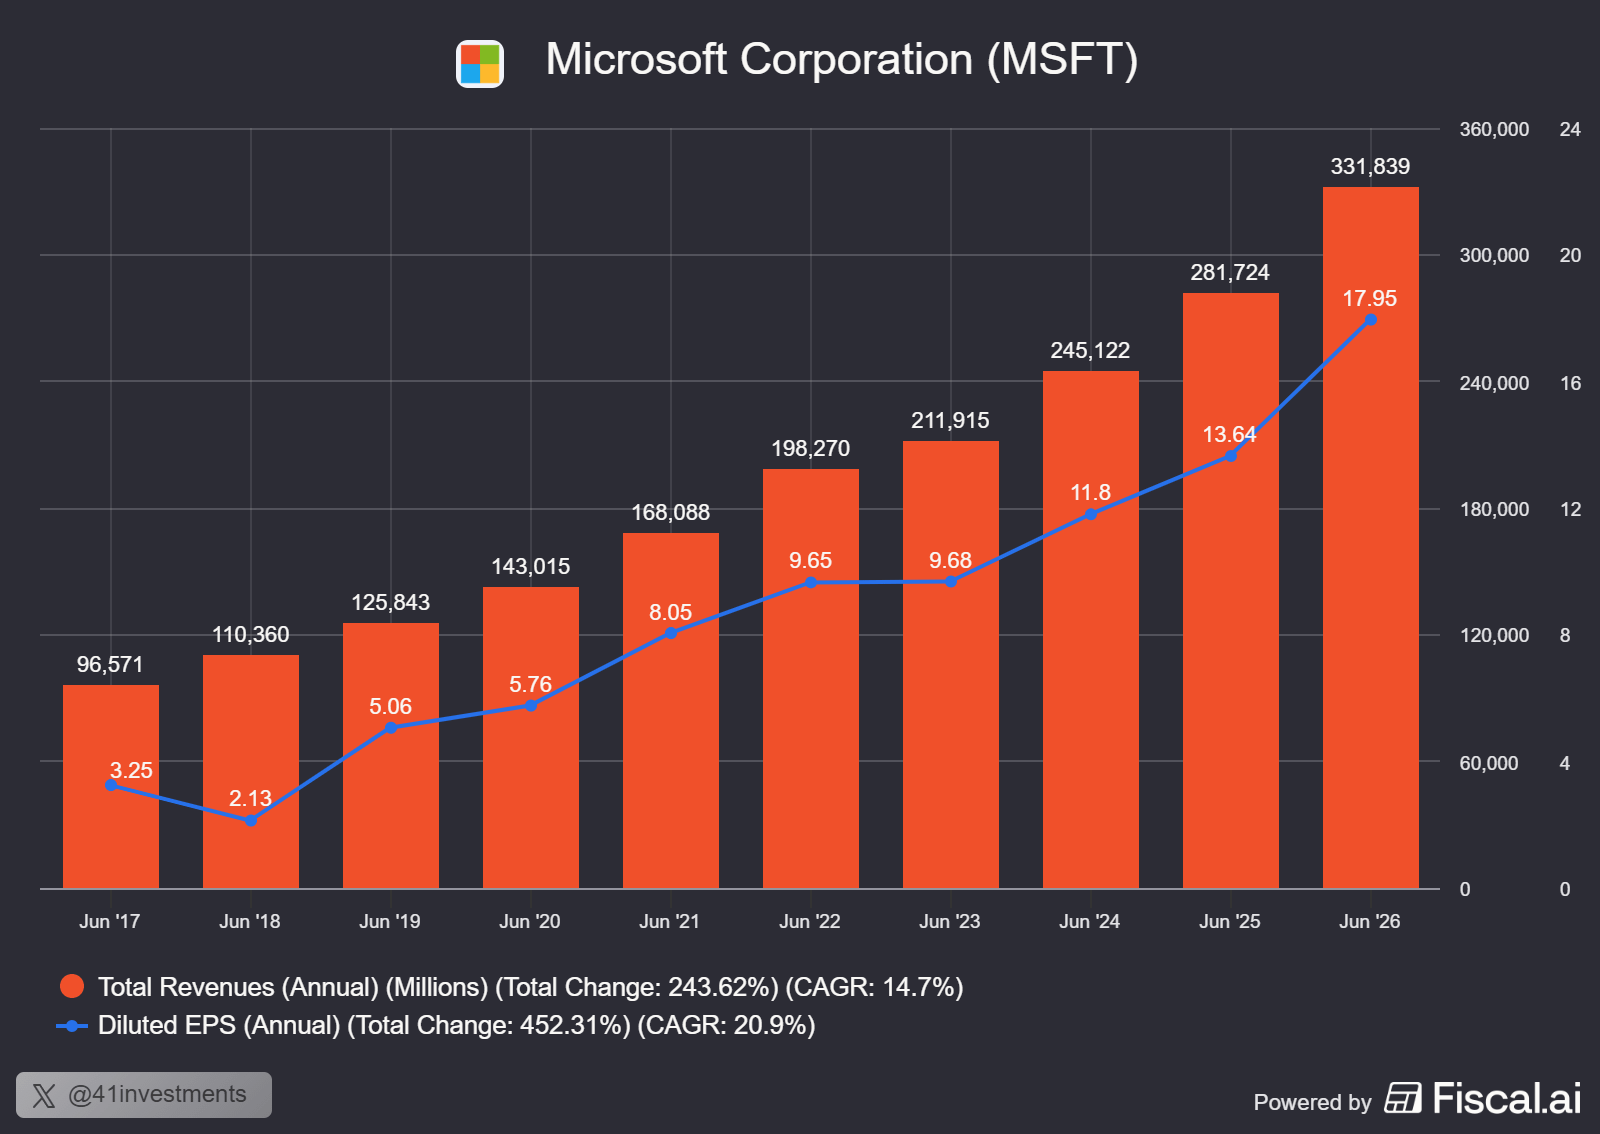
The overall revenue and EPS growth is fantastic. Keep in mind that in the long run stocks follow their EPS growth. A 20% CAGR will eventually lead to a 20% CAGR on the stock price. This will beat just about every index out there.
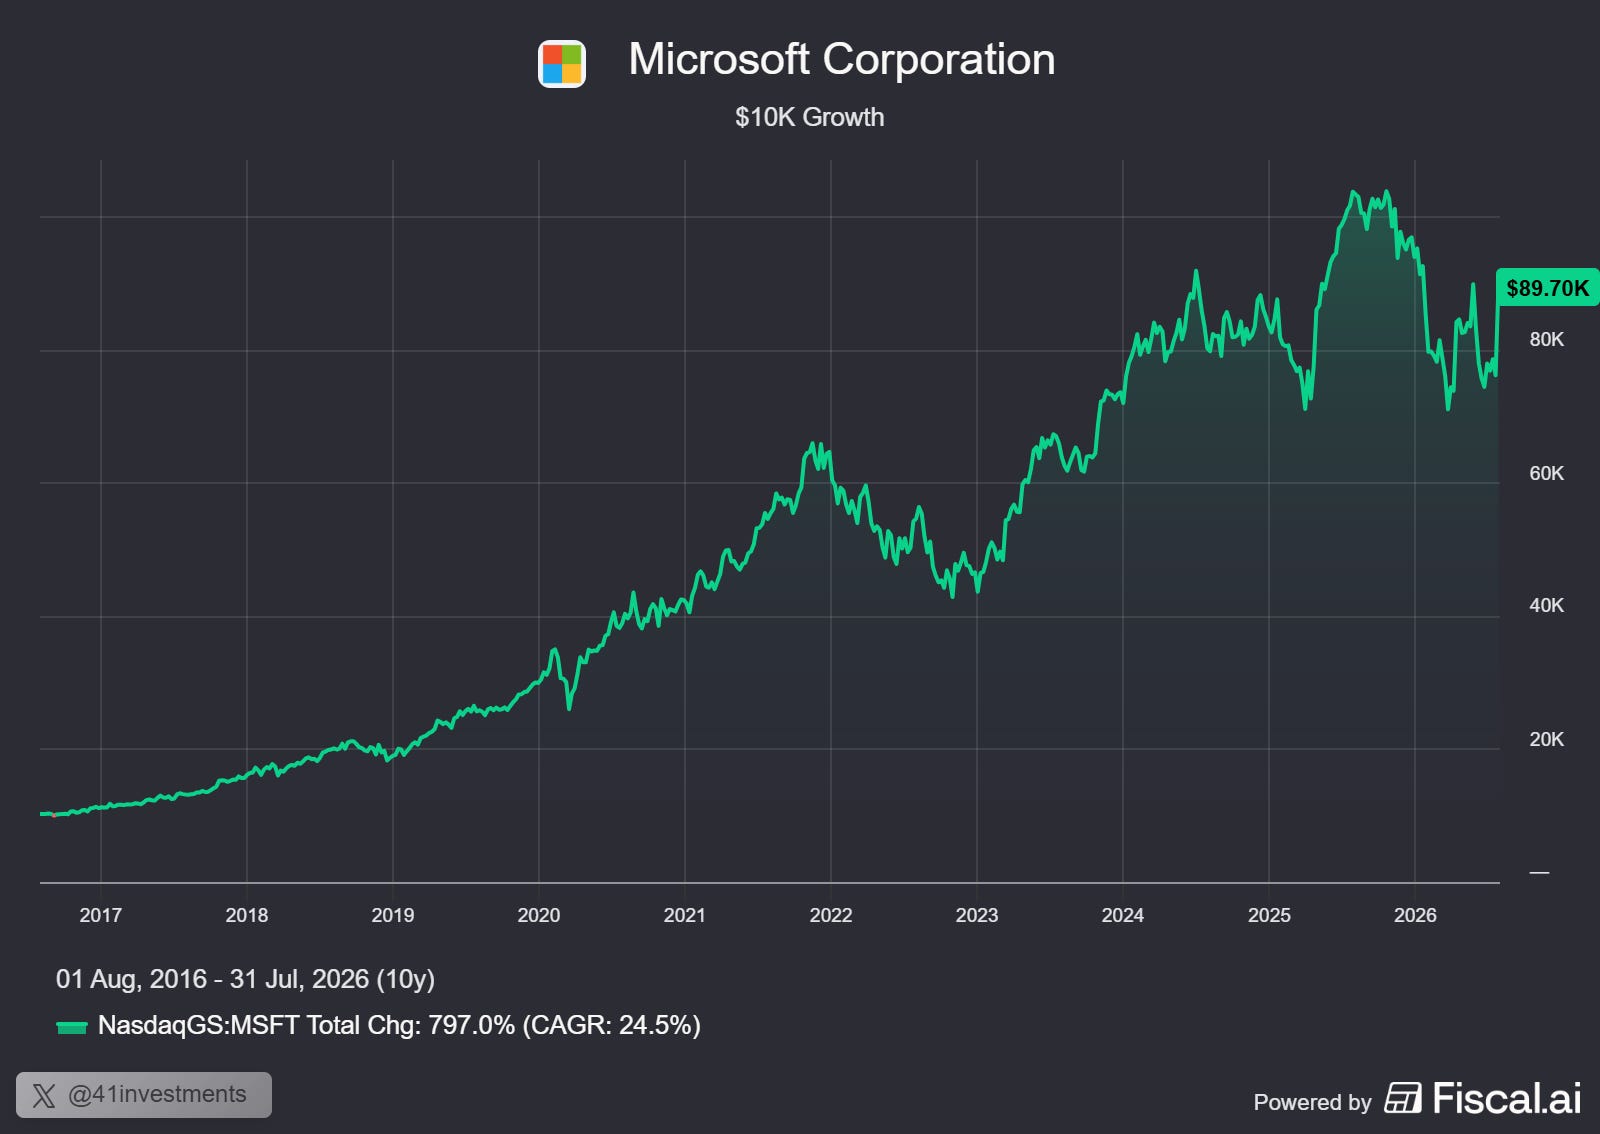
The result of this in real dollar terms is not surprising. $10k invested in August 2016 became $90k ten years later.
Microsoft CEO Satya Nadella made the following statements.
“We are advancing the frontier on the cost-to-outcome curve, ensuring every customer can turn tokens into business results,”
“This year, Azure revenue surpassed $100 billion for the first time, and Microsoft 365 Copilot reached over 30 million paid seats, reflecting the confidence customers are placing in us to power their AI transformation.”
The operational performance remains exceptional. The more difficult question—and the one investors need to answer—is whether Microsoft is still attractive at today's valuation.
This is the end of the free section. If you like what you read so far, and if you want to
✅ Why the OpenAI dependency concerns are overblown
✅ The position I reduced near the recent highs—and why I reallocated the capital elsewhere
✅ Full access to every previous Best Buys article and company deep dives
Or if you
✅ have profited from previous picks (ASML, Alphabet, Arista, AMD, and many more)
✅ and want to support me for my time and effort
Then, please become a paid subscriber. To all existing paid subscribers: You rock! 🙏
