
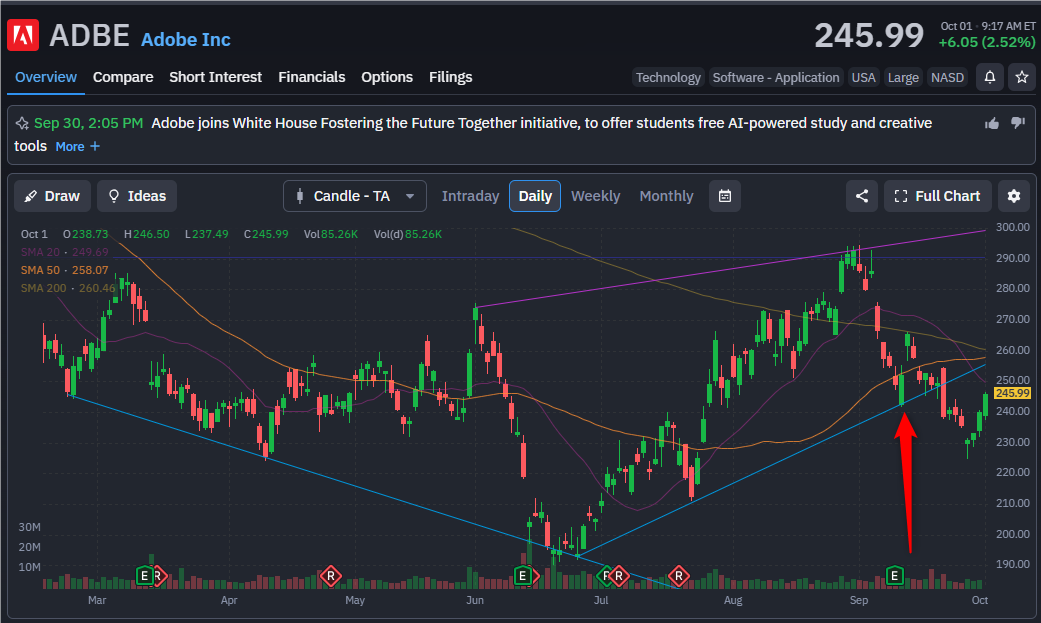
Adobe ($ADBE) reported fiscal Q3 2026 earnings on the 10th of September, beating estimates on both revenue and EPS. The stock initially jumped, then gave back the gains in the days that followed — shares remain down 64% from their all-time high and -26% year-to-date. Let's have a look at whether the company is as dead as many people claim.
Adobe Q3 2026: Key Takeaways
Revenue grew double digits, also driven by the Semrush acquisition
EPS rose 10.5%, helped by a 6.7% reduction in shares outstanding
Adobe named Anil Chakravarthy as CEO, passing over presumed frontrunner David Wadhwani
Full breakdown of cash flow, ARR & RPO trends, guidance, and valuation below
The reason why I haven’t published my article earlier is that Adobe takes quite some time to publish the official 10Q filing. In this quarterly SEC report, you can get a lot more information than by just reading the quarterly statement. Many companies file the 10Q with the earnings release; Adobe, unfortunately, takes quite some time to do so. Now we have all the information that we need. Let’s go!
Invest alongside me
I don’t just write about these companies — I invest in them. My Wikifolio is where I put the research and investment approach you read about here into practice, with a concentrated portfolio built for the long term.
Learn more here:
https://www.wikifolio.com/de/de/w/wfinvest41
Only available to investors in Germany, Austria and Switzerland. Not available to US persons. This is not investment advice. Past performance is not a reliable indicator of future results; total loss is possible.
Conflict of interest: the Wikifolio holds positions in companies discussed in this article.
About the title image
Adobe is a great company with a long track record of successes but is facing a long road to restore its name as a great company to invest in. We are not sure where the road will take us.
Before we get into the earnings, make sure to read my deep dive on Adobe and my take on the Q2/2026 earnings. You will find both articles here:


Invest at your own risk; this is not financial advice! This is not a recommendation to buy or sell any securities discussed in the article.
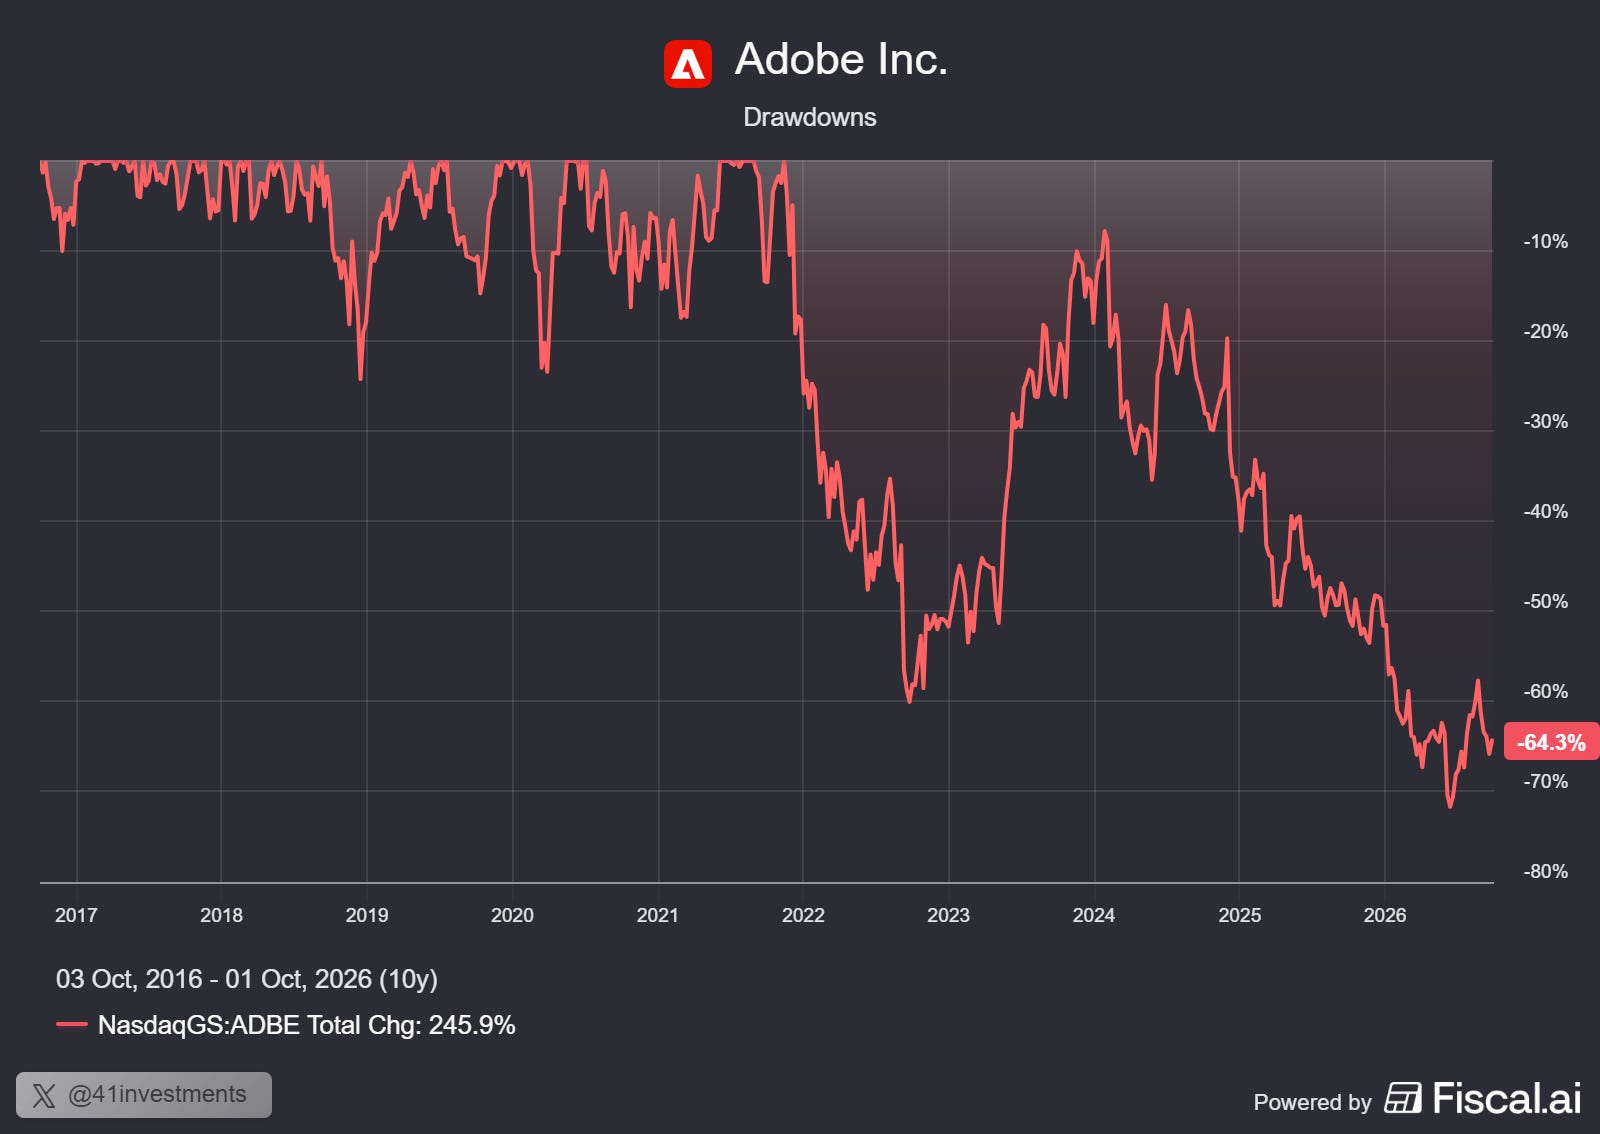
While Adobe’s share price has improved since the last earnings, the overall drawdown is still an (ugly) sight to behold. The shares are down 64% from the ATH. With a YTD performance of -26%, you will not win any awards with investors.
In case you are wondering about AI and the impact it has, make sure to learn the most important points in these two pieces:

I also shared my recent views on AI here:

Adobe has a new CEO
Adobe finally (!) named the successor to Shantanu Narayen, who has been the CEO of Adobe for the last 19 years. After it was clear that CFO Dan Durn left as well, the stage was set for two strong candidates:
David Wadhwani — President of Adobe’s Creativity & Productivity business
Anil Chakravarthy — President of Adobe’s Customer Experience Orchestration
David Wadhwani was seen as the likely successor, and Adobe surprised quite a few people when it named Anil Chakravarthy the new CEO. Particularly because Adobe’s customer experience does not have the best name. I am understating here, as shown by just one of too many Reddit posts:

I know some investors who decided to sell Adobe when the news broke, because they believed David would have done a better job than Anil. If your thesis is so strongly tied to the choice of a CEO, your thesis was not the strongest to begin with. I believe CEO changes are particularly important if one of the following two happens: The long-term founder and CEO leaves the company or a CEO with a criminal record has been appointed. Both are not the case here and I personally do not know either David or Anil. Therefore, I am neutral. Give this man a chance to turn Adobe around.
Regarding the CFO position: Steve Day is, as of today, the Interim Chief Financial Officer and Senior Vice President, Finance, Technology, Security and Operations. Wow, what a title. I wonder if that fits on a business card. I also hope that the CFO replacement will not take as long as the CEO search. Adobe must regain the trust of investors.
Management’s summary
That’s how the management described the results:
Adobe delivered record Q3 results, reflecting the strength of our AI innovation, expanding customer reach and leadership across creativity, productivity and customer experience. Reaching a landmark of more than one billion monthly active users is a defining moment for Adobe, and I have confidence that Anil will build on this momentum to drive Adobe's next chapter of growth and innovation in the AI era.
Adobe delivered double-digit revenue and EPS growth in Q3 and we're raising full year revenue and EPS targets. We are expanding our user base through a freemium strategy and deepening engagement with agentic experiences to deliver long-term durable growth.
Income Statement
There is another company in a somewhat similar boat as Adobe: Salesforce. I wrote about the most recent earnings of Salesforce here:

To make it clear right away: Adobe is not a broken company, but a broken stock. The company is still highly profitable and is growing.
Revenue kept growing at double digits (SemRush is the main driver of the acceleration), and gross profit followed. Operating expenses grew 15% YoY, and as a result, the operating income grew more slowly than the revenue and gross profit. Net income grew by “only” 3% vs. Q3/2025. Adobe explained that AI inference costs are adding to the overall cost of goods sold and therefore lowered the gross margin.
Cost of subscription revenue consists primarily of third-party hosting services and data center costs, including expenses related to operating our network infrastructure and AI inferencing costs
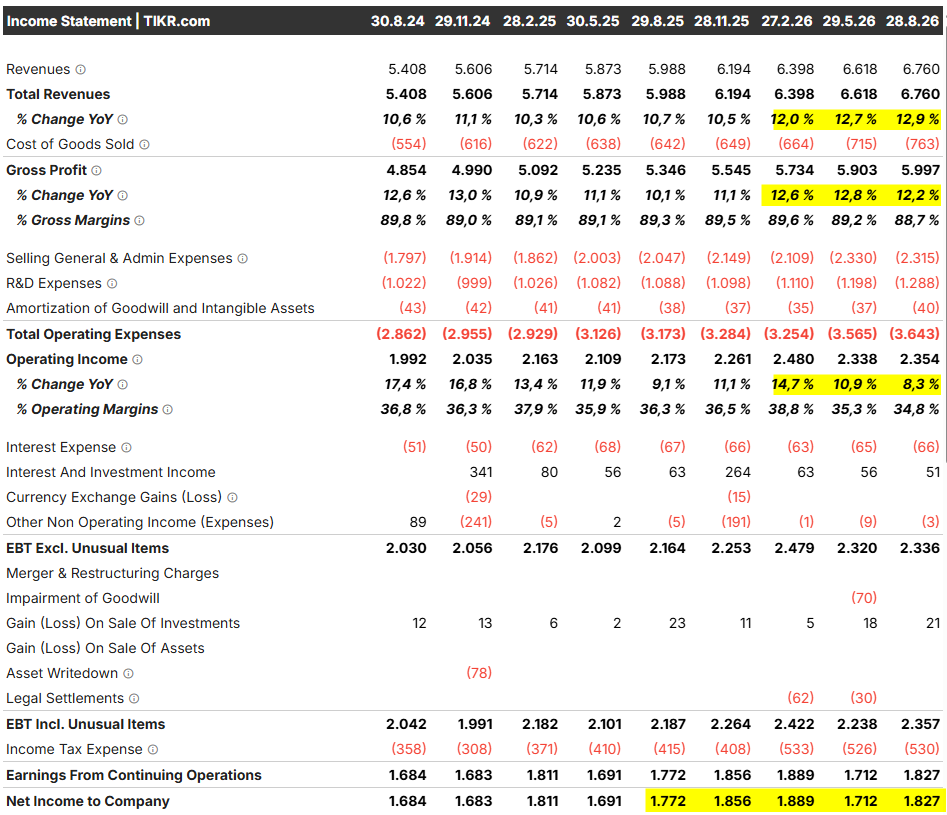
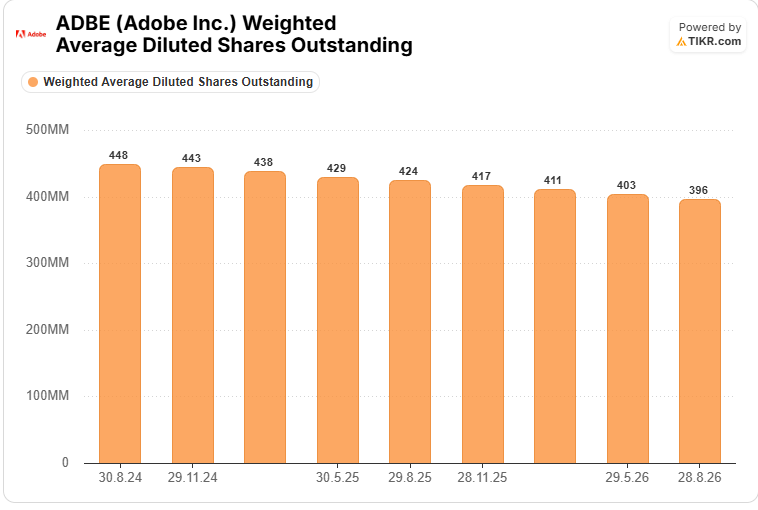
The earnings per share (EPS) still improved by 10.5% due to the large share buybacks. The number of outstanding shares dropped by 6.7% over the last 12 months.

Compared with Q3/24, Adobe reduced the number of outstanding shares by 12%. This is quite something and a big reason Adobe’s share price hasn't fallen even more.
Balance Sheet
B as in Booking: Learn all about Booking and why the company is so interesting here and not just another company getting disrupted by AI.

The balance sheet is still clean, with cash and short-term investments at $5.6 billion being slightly less than the outstanding debt at $6.4 billion. Goodwill increased due to the closing of the Semrush acquisition.
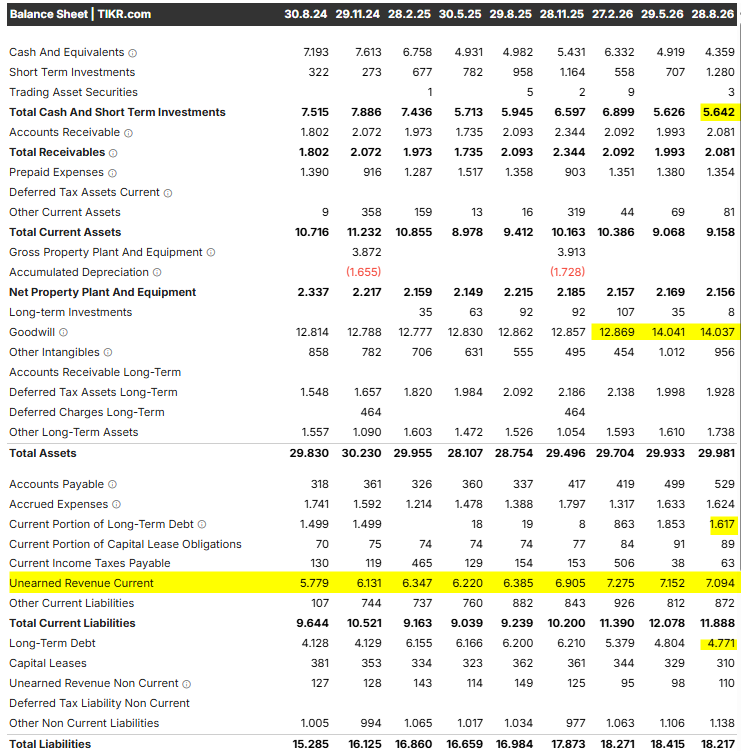
Current unearned revenue is still stable. The big jumps always occur in Q4 every year. This is an important metric that I will be closely monitoring next quarter. Today’s unearned revenue will be tomorrow’s revenue.
This is the end of the free section. If you want to
✅ The full cash flow breakdown — including the metric I'm watching most closely heading into Q4
✅ The real ARR growth rate once you strip out the Semrush acquisition — and why it's weaker than the headline number suggests
✅ My complete earnings call breakdown — what CFO Steve Day said about the RPO slowdown, and whether it's just timing or something worse
✅ Full valuation: EV/net income of 13, EV/(FCF-SBC) of 11.2, and my price target if the multiple re-rates
✅ My verdict — is Adobe actually cheap, or is this a value trap?
Then, please become a paid subscriber. To all existing paid subscribers: You make my day! 🙏
